
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
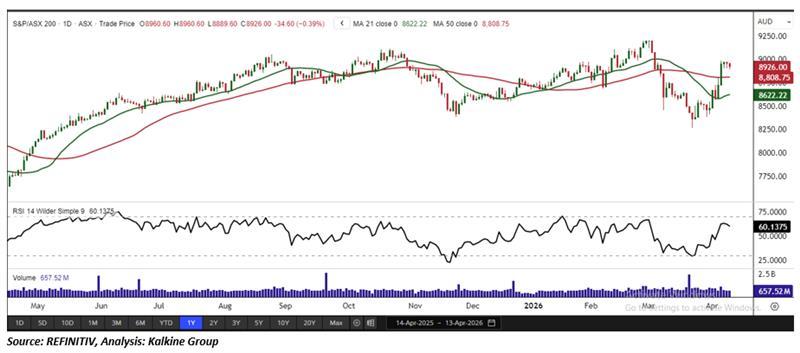
Index Update: Australian equities closed lower on Monday, with the S&P/ASX 200 declining 34.60 points or 0.39% to finish at 8,926.00, as cautious sentiment returned to the market. Despite the day’s pullback, the benchmark index has still gained 4.04% over the past five trading sessions and remains just 3.01% below its 52-week high, indicating underlying resilience in recent momentum.
Sector performance reflected a mixed yet negative bias, with eight of eleven sectors closing in the red. Information Technology emerged as a notable laggard, while Industrials and Consumer Discretionary also recorded declines. In contrast, Energy stood out as the top performer, rising 2.11% and rebounding from recent weakness, although it remains down 1.84% over the past five days.
The broader market weakness came amid rising geopolitical tensions, as oil prices surged after US President Donald Trump ordered a blockade of the Strait of Hormuz following unsuccessful peace talks with Iran over the weekend, adding a layer of uncertainty to global markets.
Macro Update: Global finance leaders are set to gather in Washington this week against the backdrop of escalating conflict in the Middle East, adding a fresh layer of uncertainty to the global economic outlook. The ongoing war is being viewed as a third major shock to the world economy, following the COVID-19 pandemic and Russia’s invasion of Ukraine in 2022.
Officials from the International Monetary Fund and World Bank have indicated that global growth forecasts will be revised downward, while inflation projections are expected to rise. The impact is likely to be more pronounced in emerging and developing economies, which remain vulnerable to elevated energy costs and ongoing supply disruptions.
Prior to the outbreak of the Iran conflict on February 28, both institutions had been considering upward revisions to growth forecasts, supported by continued economic resilience despite tariff measures introduced by U.S. President Donald Trump. However, the conflict has altered that trajectory, introducing new pressures that could slow recovery and complicate efforts to contain inflation.
Top Market Movers: Gains were led by healthcare and energy-linked names, with Telix Pharmaceuticals Limited (TLX) closing at AUD 15.690, up AUD 1.050 or 7.17% for the session. Karoon Energy Ltd (KAR) followed, rising AUD 0.110 or 5.53% to AUD 2.100, while New Hope Corporation Limited (NHC) advanced AUD 0.260 or 5.02% to AUD 5.440, reflecting buying interest across select resource and energy stocks.
On the downside, The A2 Milk Company Limited (A2M) recorded the steepest fall among the listed names, declining AUD 1.140 or 12.34% to AUD 8.100. Ora Banda Mining Ltd (OBM) dropped AUD 0.125 or 9.33% to AUD 1.215, while IDP Education Limited (IEL) fell AUD 0.350 or 8.77% to AUD 3.640, marking notable weakness across consumer and education-related stocks during the session.
Commodity Update: U.S. dollar rose to its strongest level in one week during early Asian trade on Monday after peace talks between the United States and Iran collapsed and the U.S. Navy prepared to blockade Iranian ports. Gold declined 0.99% to USD 4,739.80, silver dropped 2.78% to USD 74.35, and copper slipped 0.66% to USD 12,771.00. Meanwhile, Brent crude jumped 7.36% to USD 102.20, moving back above USD 100.00 per barrel again.
Our Stance: Australian equities eased on Monday, with the S&P/ASX 200 falling 0.39% to 8,926.00 as geopolitical tensions weighed on sentiment. Despite the decline, the index remains up 4.04% over five sessions and close to its 52-week high, reflecting underlying resilience. Sector performance was mixed, with Energy gaining on higher oil prices, while Technology and consumer-linked stocks lagged. Market direction was influenced by escalating Middle East tensions, which also drove commodity divergence, including a sharp rise in crude prices. Global macro signals point to softer growth and higher inflation expectations. Overall, near-term volatility may persist, though broader momentum remains supported.
The S&P/ASX 200 declined by 34.60 points in the latest session, forming a bearish candlestick. Despite this pullback, the broader technical outlook remains cautiously constructive, suggesting that a confirmed uptrend is still in the process of developing. The index continues to trade above its 21-period Simple Moving Average (SMA) on the daily chart, which is acting as a key dynamic support and helping to reinforce underlying strength in the overall price structure. Holding above this level is likely to support near-term stability and limit downside risks. However, immediate support is seen around the 8,830 level, and a sustained break below this zone could weaken market sentiment and potentially trigger a deeper corrective phase in the sessions ahead.


 Nov 12, 2026





 Please wait processing your request...