
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
index Update: Australian shares ended Friday lower, with the S&P/ASX 200 falling 61.0 points, or 0.70%, to 8,625.10, slipping below its 20-day Moving Average as weakness in iron ore prices weighed on market sentiment. Iron ore declined to a three-month low, pressuring major Mining stocks and dragging the materials sector down 2.31%, making it the day's worst performer. Over the past five trading sessions, the benchmark index has fallen 1.22% and is down 1.02% year-to-date. Despite the broader decline, eight of 11 sectors finished higher, led by health care, which surged 3.54% on Friday and gained 1.01% over the past week.
Macro Update: The escalating conflict in the Middle East has emerged as a key risk to the global economy, triggering an energy shock that is expected to increase inflationary pressures and weigh on growth, according to the latest Economic Outlook from the Organisation for Economic Co-operation and Development (OECD). The OECD outlined two potential scenarios: a temporary disruption in which Gulf energy production and trade gradually recover from mid-2026, and a prolonged disruption extending into 2027, keeping energy prices elevated and tightening financial conditions. Under its baseline forecast, global economic growth is projected at 2.8% in 2026, down from 3.4% recorded last year.
Top Market Movers: Among the top gainers, Megaport Limited (ASX:MP1) surged 15.19% to AUD 18.480, adding AUD 2.436 during the session. TUAS Limited (ASX:TUA) rose 12.16% to AUD 2.490, up AUD 0.270, while CSL Limited (ASX:CSL) advanced 5.75% to AUD 97.910, gaining AUD 5.320. On the losing side, Liontown Limited (ASX:LTR) fell 6.14% to AUD 2.140, shedding AUD 0.140. Pantoro Gold Limited (ASX:PNR) declined 5.72% to AUD 2.640, down AUD 0.160, while Bellevue Gold Limited (ASX:BGL) dropped 5.46% to AUD 1.385, losing AUD 0.080.
Commodity Update: Global commodity markets traded mixed on Friday as improving risk sentiment weighed on the U.S. dollar following a ceasefire agreement between Israel and Lebanon, raising hopes for broader diplomatic progress in the Middle East. Gold gained 0.77% to USD 4,502.90 per ounce, while silver advanced 0.17% to USD 73.82 per ounce. Copper edged down 0.06% to USD 13,788.90 per tonne. Brent Crude oil rose 0.30% to USD 95.29 per barrel after Hezbollah rejected the ceasefire, maintaining geopolitical concerns.
Our Stance: Australian equities remain under pressure as weaker iron ore prices continue to weigh on the resources sector, offsetting strength in defensive areas such as healthcare. The ASX 200's move below its 20-day moving average suggests near-term sentiment remains cautious, particularly as commodity-linked stocks face Earnings headwinds. At the macro level, escalating Middle East tensions and the OECD's downgraded global growth outlook reinforce concerns around slower economic activity and persistent Inflation risks. While improving healthcare performance and selective growth-stock strength provide some support, commodity Volatility, geopolitical uncertainty, and softer global growth expectations are likely to keep markets range-bound in the near term.
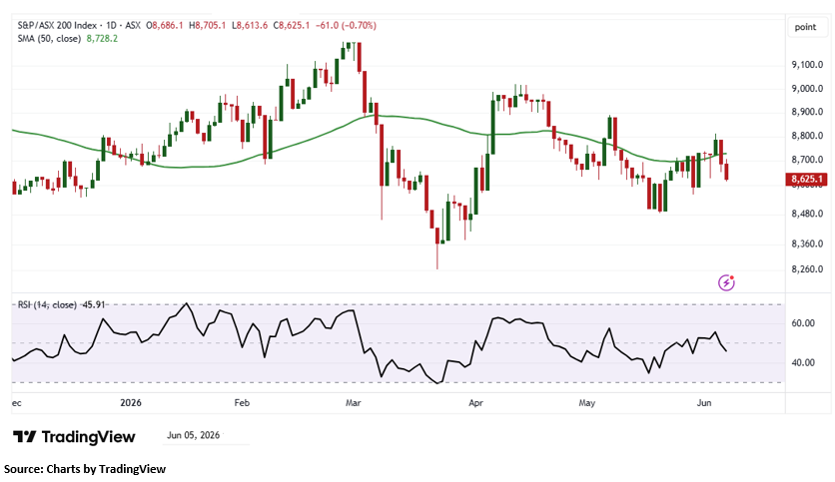
The S&P/ASX 200 fell 61.00 points in the latest Trading session, forming a bearish candlestick pattern that points to weakening short-term market sentiment and increased selling pressure. Technically, the index remains below its 50-day Simple Moving Average (SMA), which continues to act as a key dynamic resistance level and is restricting near-term upside momentum. Immediate support is situated near the 8,600 level, and maintaining this area could help stabilise sentiment and preserve the broader market structure. A decisive break below 8,540.60, however, would weaken the technical outlook and could trigger a deeper corrective move accompanied by higher volatility. While the index remains vulnerable to additional downside pressure below its key moving averages, sustained support above 8,540.60 may provide a platform for a potential recovery in the sessions ahead.


 Nov 12, 2026





 Please wait processing your request...