
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
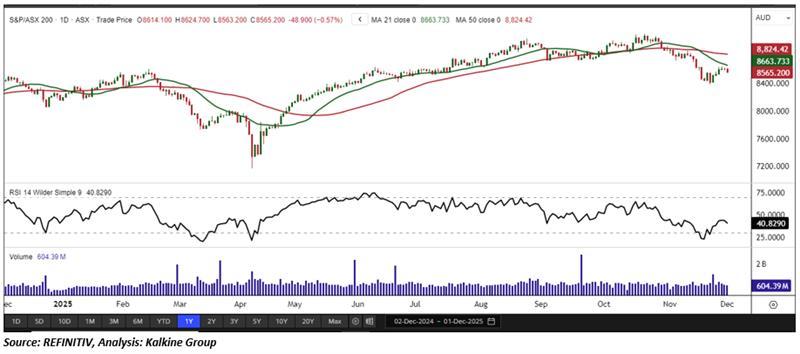
Index Update: The S&P/ASX 200 closed lower on Monday, declining 48.90 points or 0.57% to finish at 8,565.20, as weakness in US futures weighed on local sentiment even while markets positioned for a potential interest rate cut by the US Federal Reserve later this month. Despite the soft start to December, the index has still gained 0.47% over the past five sessions and remains up 4.98% year-to-date. Market breadth was negative, with eight of eleven sectors ending in the red. Energy sector was the best performer, rising 0.51% on the day and 0.70% across the week. Meanwhile, the Healthcare sector endured the sharpest pullback, falling 1.65%.
Macro Update: China spent years financing and developing Indonesia’s nickel sector, helping turn the country into the world’s largest producer. Now, Chinese electric vehicle makers are shifting away from nickel-based battery chemistries, prompting Beijing to reconsider how much of the metal it needs—and challenging Indonesia’s rapid build-out.
Fresh ABS figures show exploration activity continuing to climb. Seasonally adjusted mineral exploration expenditure rose 2.4%, while petroleum exploration saw a sharp 34.6% jump, signalling ongoing strength in resource investment.
Top Market Movers: Among Monday’s top performers, Greatland Resources Ltd (ASX:GGP) led the gains, climbing 10.20% to AUD 8.320. Tuas Limited (ASX:TUA) also advanced, rising 4.94% to AUD 6.800, while Capstone Copper Corp (ASX:CSC) added 4.32% to finish at AUD 13.760. On the declines side, AUB Group Ltd (ASX:AUB) posted the steepest fall, dropping 17.77% to AUD 30.630. Metcash Ltd (ASX:MTS) declined 9.19% to AUD 3.360, and Digico Infrastructure Ltd (ASX:DGT) slipped 8.22% to AUD 2.570.
Commodity Update: The dollar slipped at the start of December as markets positioned for a crucial month that may deliver the Fed’s final rate cut of the year and confirm a dovish successor to Jerome Powell. Commodities traded firmer, with gold up 0.51% at USD 4,276.40, silver rising 1.53% to USD 57.31, and copper edging 0.35% higher to USD 11,237. Brent crude jumped 1.51% to USD 63.32 after OPEC+ paused its planned output increases.
Our Stance: Market sentiment remained cautious on Monday as the S&P/ASX 200 fell 0.57%, pressured by weak US futures despite expectations of a Fed rate cut. Energy outperformed, while healthcare led declines, highlighting uneven sector dynamics. A softer US dollar supported gains in commodities, with gold, silver, copper, and Brent crude all rising. Domestic challenges emerged as the ASX faced a system outage, affecting around 80 stocks, even as exploration spending showed strong growth. Overall, markets reflect a measured but constructive environment, with selective opportunities amid ongoing volatility and global policy shifts.
In its latest session, the S&P/ASX 200 Index declined 48.90 points, forming a large bearish candlestick on rising volume a combination that signals heightened investor caution and reinforces the prevailing short-term bearish sentiment. Despite the pullback, the index continues to trade below its 50-period Simple Moving Average (SMA), which remains an important zone of immediate resistance. On the daily chart, key support is positioned near 8,500. Holding above this level will be essential for stabilizing price action and helping restore market confidence in the near term. From a broader weekly perspective, however, the index still trades above its 50-period SMA, a constructive long-term signal that suggests the potential for sustained upward momentum once current selling pressure begins to ease.


 Nov 12, 2026





 Please wait processing your request...