
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Image Source : Krish Capital Pty Ltd
Index Update: The S&P/ASX 200 Index ended lower on Monday, slipping 45.40 points or 0.51% to close at 8,927.70. The index is now 0.44% down over the past five sessions and trades 1.40% below its 52-week high. Sector performance was mixed, with seven of eleven sectors finishing in the red. Information Technology led losses, falling 2.65%, followed by Consumer Discretionary, which dropped 1.24%. Financials, Industrials, and Health Care also posted declines. On the upside, Consumer Staples outperformed with a 0.35% gain, rebounding from a recent five-day decline of 1.11%. Utilities and Telecommunications Services also managed modest gains of 0.30% and 0.31%, respectively.
Macro Update: Australia’s total number of dwelling approvals fell 8.2% in July 2025 to 15,769, according to seasonally adjusted data from the Australian Bureau of Statistics (ABS). The decline was mainly driven by a 22.3% drop in private dwellings excluding houses, reversing the 33.5% rise seen in June. Approvals for private sector houses, a more stable segment, rose slightly by 1.1%.
In other key June 2025 statistics, mineral exploration expenditure increased 2.3%, while petroleum exploration expenditure dropped 4.9%. Company gross operating profits fell 2.4% over the period, whereas wages and salaries recorded a 1.0% rise.
Top Market Movers: Capricorn Metals Ltd (ASX: CMM) led the gainers on Monday, rising 11.73% to close at AUD 11.43, followed by Genesis Minerals Ltd (ASX: GMD) up 11.53% at AUD 5.03 and Harvey Norman Holdings Ltd (ASX: HVN) gaining 8.56% at AUD 7.48. On the downside, Generation Development Group Ltd (ASX: GDG) fell 8.70%, Mesoblast Ltd (ASX: MSB) dropped 7.34%, and Bapcor Ltd (ASX: BAP) declined 6.78%.
Commodity Update: The U.S. dollar remained range-bound on Monday as investors awaited a series of key labour market data releases this week, which are expected to influence the scale of the Federal Reserve’s anticipated rate cut later this month. Gold rising 0.85% to USD 3,545.62, silver gaining 1.63% to USD 41.39, and copper edging slightly higher by 0.01% to USD 9,923.90. Brent crude slipped 0.36% to USD 67.25, as concerns over higher output and potential demand weakness from U.S. tariffs outweighed supply risks linked to escalating Russia-Ukraine airstrikes.
Our Stance: The S&P/ASX 200’s 0.51% drop reflects persistent investor caution as weakness in tech and consumer discretionary weighed on sentiment. The decline in dwelling approvals and falling company profits highlight macro headwinds that could pressure growth in the near term. However, resilience in Consumer Staples and gains in Utilities and the Telcom sector suggest selective buying. With gold and silver rallying, investors appear to be hedging against uncertainty. In such a context, market volatility may persist until clearer signals emerge from upcoming U.S. labour data and Fed rate decisions, making a defensive and selective sector approach is prudent in the short term.
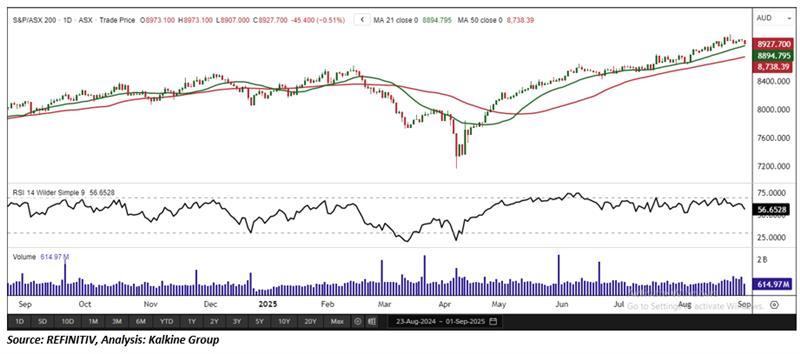
The S&P/ASX 200 Index closed lower by 45.40 points, forming a bearish candlestick pattern. Despite this pullback, the broader technical outlook remains constructive. On the daily chart, the index continues to trade above its 21-period Simple Moving Average (SMA), which serves as a key support level. A critical support zone lies near 8,880.70, and holding above this area could allow the index to consolidate recent gains and reinforce investor confidence in the prevailing uptrend. From a multi-timeframe perspective, the index also remains above its 21-period SMA on the weekly chart, underscoring the potential for sustained bullish momentum.


 Nov 12, 2026





 Please wait processing your request...