
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
index Update: The S&P/[ASX 200] closed lower on Tuesday, falling 34.20 points or 0.39% to 8,657.80, slipping below its 20-day Moving Average. Despite the decline, the benchmark index remains up 0.62% over the past five trading sessions and is broadly flat year to date.
Australian equities weakened as Crude Oil prices resumed their upward trend following US strikes in Iran, which reduced optimism surrounding a potential peace agreement that could reopen the Strait of Hormuz. The renewed geopolitical tensions weighed on broader market sentiment after recent gains.
Sector performance was largely negative, with 10 of the 11 sectors ending in the red. Materials emerged as the strongest-performing sector, rising 0.15% on the day and gaining 3.68% over the past five sessions.
Macro Update: New data from the Australian Bureau of Statistics shows that 72 per cent of Australian businesses have been negatively impacted by rising fuel prices and Supply shortages amid global Volatility and ongoing supply chain disruptions. Around 36 per cent of businesses reported lower Revenue in recent weeks, while 27 per cent expect further declines ahead. Half of all businesses faced higher operating costs, mainly due to fuel, freight and delivery expenses. In response, many businesses absorbed rising costs, increased prices, delayed production schedules, or introduced fuel surcharges. Workforce adjustments were also made, including reducing travel activities and cutting staff numbers.
Top Market Movers: Among the top gainers, Fisher & Paykel Healthcare Corporation Limited (ASX:FPH) led the market, rising AUD 2.520 or 9.153% to close at AUD 30.050. South32 Limited (ASX:S32) gained AUD 0.210 or 4.751% to AUD 4.630, while Austal Limited (ASX:ASB) advanced AUD 0.170 or 4.497% to finish at AUD 3.950.
On the losing side, ASX Limited (ASX:ASX) declined AUD 7.780 or 13.229% to AUD 51.030. PEXA Group Limited (ASX:PXA) fell AUD 0.680 or 5.924% to AUD 10.800, while Challenger Limited (ASX:CGF) dropped AUD 0.500 or 5.348% to close at AUD 8.850.
Commodity Update: The U.S. dollar remained under pressure on Tuesday as investors weighed hopes of a potential agreement to reopen the Strait of Hormuz and ease the three-month-long Iran conflict against fresh U.S. strikes on Iranian targets. Gold declined 0.74% to USD 4,570.90 per ounce, while silver dropped 1.77% to USD 77.01. Copper edged up 0.02% to USD 13,667.50 per tonne. Brent Crude oil advanced 1.10% to USD 97.32 per barrel as Middle East tensions continued to keep energy markets volatile.
Our Stance: The S&P/ASX 200 closed 0.39% lower at 8,657.80 on Tuesday as renewed geopolitical tensions in the Middle East and rising crude oil prices weighed on investor sentiment. Most sectors ended in negative territory, although Materials remained resilient. Meanwhile, fresh data from the Australian Bureau of Statistics highlighted mounting pressure on businesses from fuel costs and supply disruptions, with many firms facing weaker revenue and rising operating expenses. Among market movers, Fisher & Paykel Healthcare Corporation Limited outperformed, while ASX Limited led declines. Elevated energy prices and geopolitical uncertainty may continue driving cautious market sentiment in the near term.
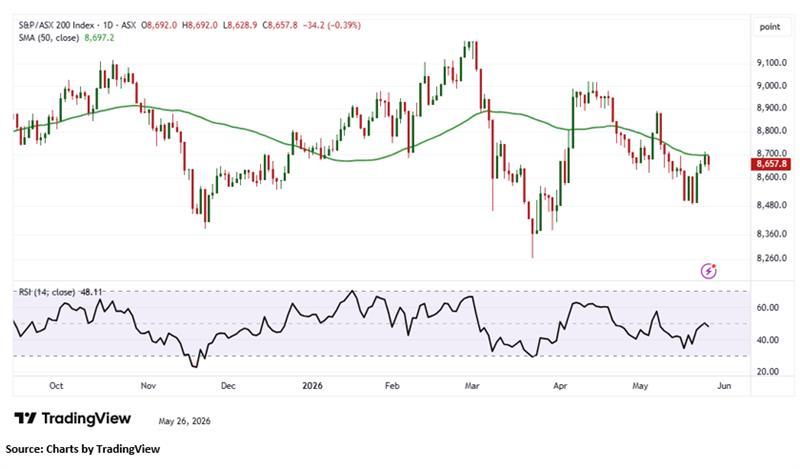
The S&P/ASX 200 declined 34.20 points in the latest Trading session, forming a bearish candlestick pattern that reflects weakening short-term sentiment. Despite intermittent recovery attempts, the index continues to trade below its 50-day Simple Moving Average (SMA), which remains a key dynamic resistance level and may continue to cap near-term upside momentum. Technically, immediate support is positioned near the 8,540.60 level, and holding above this zone would help preserve the broader short-term recovery structure while supporting further stabilisation in market sentiment. However, a decisive break below the 8,540.60 mark could weaken the current technical setup, increasing the likelihood of a deeper corrective phase accompanied by heightened volatility and a more cautious near-term outlook.


 Nov 12, 2026





 Please wait processing your request...