
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed lower on Tuesday, falling 9.30 points, or 0.10%, to 9,066.70. The index has declined 1.07% over the past five days and remains 2.47% below its 52-week high. Sector performance was mixed, with seven of 11 sectors ending lower. Energy led gains, rising 1.18% on Tuesday and 0.64% over five days. Materials and Health Care also advanced, while Consumer Discretionary and Telecommunications Services recorded notable declines.
Macro Update: The Australian Bureau of Statistics reported that Australia’s general government net operating balance fell by $3.6 billion to a $2.8 billion Deficit in the June quarter 2026. Taxation Revenue rose 9.3% to $241.3 billion, while general government borrowing reached $23.6 billion. Separately, total dwelling approvals fell 3.6% in July to 17,687. Private sector house approvals declined 4.2%, while private sector dwellings excluding houses fell 0.4%. The value of total building approved rose 3.3% to $21.19 billion, supported by a 14.4% increase in non-residential building approvals.
Top Market Movers: Judo Capital Holdings Limited (ASX:JDO) led the gainers, rising 6.896% to AUD 1.085, followed by Liontown Limited (ASX:LTR), which advanced 6.530% to AUD 1.305. Resolute Mining Limited (ASX:RSG) gained 5.839% to AUD 1.450. Among the decliners, Pinnacle Investment Management Group Limited (ASX:PNI) fell 10.137% to AUD 15.160. REA Group Ltd (ASX:REA) declined 4.209% to AUD 169.780, while Nextdc Limited (ASX:NXT) dropped 4.200% to AUD 13.230.
Commodity Update: The yen steadied near the 160-per-dollar mark on Tuesday as U.S. Treasury Secretary Scott Bessent increased pressure on the Bank of Japan to consider a rate hike later this month. Currency markets remained cautious amid renewed Middle East tensions. Gold gained 0.18% to USD 4,489.30, while silver rose 0.37% to USD 67.24. Copper advanced 1.06% to USD 14,405.10. Brent Crude climbed 0.60% to USD 91.05 as renewed U.S.-Iran fighting heightened concerns over potential disruptions to regional oil supplies.
Our Stance: The S&P/ASX 200 edged lower on Tuesday, extending its five-day decline to 1.07%, as seven of 11 sectors ended in negative territory. Energy provided support, while Consumer Discretionary and Telecommunications Services weighed on the index. Australian Bureau of Statistics data presented mixed signals, with the government net operating balance moving into a AUD 2.8bn deficit and dwelling approvals falling 3.6% in July, despite higher taxation revenue and building values. Judo Capital, Liontown and Resolute Mining led gains, while Pinnacle, REA Group and NextDC declined. Commodity prices advanced broadly, offering some support. Overall, cautious sentiment persists as weaker domestic indicators offset gains across key commodities and selected market sectors.
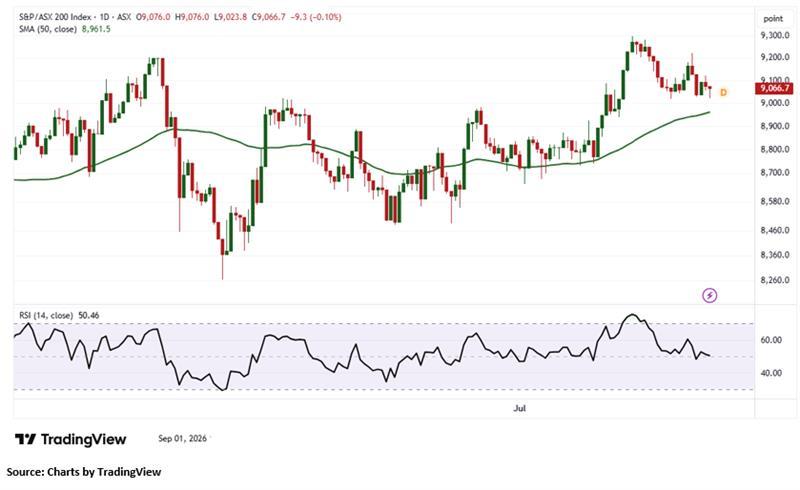
On the technical front, the S&P/ASX 200 Index declined by 9.30 points in the latest trading session. Despite the pullback, the index continues to hold above key support near 8,940.50, which remains crucial for maintaining the prevailing bullish bias. A sustained hold above this level could support a recovery towards recent highs, while a decisive break below 8,940.50 would weaken the technical setup and increase downside risk. On the upside, a decisive breakout above the recent swing high near 9,060 would reinforce bullish momentum and potentially pave the way for further gains towards the next target near 9,130.


 Nov 12, 2026





 Please wait processing your request...