
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
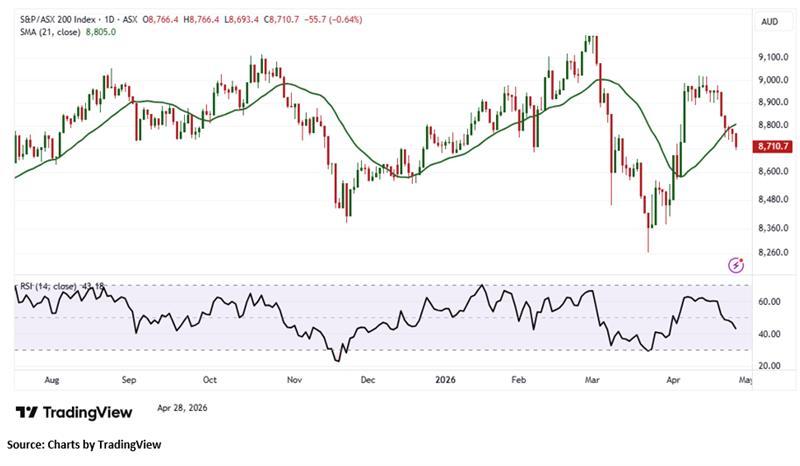
index Update: Australian equities retreated on Tuesday, with the S&P/ASX 200 falling 55.70 points, or 0.64%, to 8,710.70, pulling back after recent Volatility. The index is down 2.67% over the past five sessions, though it remains broadly flat year to date. Market Breadth was weak, with nine of eleven sectors finishing lower, while Energy stood out as the strongest-performing sector, rising 1.20% on the day and extending its five-day gain to 3.09%, offering a partial offset to broader market softness.
Macro Update: Global markets are closely watching a pivotal week for Monetary Policy, with major G7 central banks widely expected to leave interest rates unchanged as policymakers assess Inflation risks linked to the Iran conflict. According to media reports, central banks in the US, Canada, Japan, Britain and the eurozone may signal that persistent energy disruptions and Supply chain pressures could keep borrowing costs elevated for longer. The evolving geopolitical backdrop has heightened concerns that a prolonged conflict may intensify inflationary pressures for households and businesses, reinforcing a cautious policy stance.
Top Market Movers: Top gainers were Mineral Resources (ASX:MIN), up 4.00% to AUD 61.370, Liontown (ASX:LTR), rising 3.95% to AUD 2.370, and Whitehaven Coal (ASX:WHC), gaining 3.90% to AUD 8.000. On the downside, Pantoro Gold (ASX:PNR) fell 11.29% to AUD 3.380, Domino’s Pizza Enterprises (ASX:DMP) dropped 10.71% to AUD 15.850, and West African Resources (ASX:WAF) declined 6.88% to AUD 2.980.
Commodity Update: The Japanese yen held steady in Asian trade on Tuesday ahead of the Bank of Japan policy decision, while focus also remained on the Federal Reserve. Gold declined 0.15% to USD 4,686.40, silver slipped 0.61% to USD 74.56, and copper eased 0.19% to USD 13,191.80. Brent Crude rose 0.40% to USD 108.68 amid tensions around the Strait of Hormuz and comments from Donald Trump on Iran.
Our Stance: Australian equities extended their recent pullback on Tuesday, with the ASX 200 slipping 0.64% as weakness across most sectors outweighed gains in Energy, which continued to benefit from firmer oil prices and geopolitical risk. Broader sentiment remained cautious as investors balanced softer Market Breadth against rising Inflation concerns tied to the Iran conflict, while attention shifted to G7 central banks expected to hold rates steady but maintain a hawkish tone. Commodity markets were mixed, with higher crude prices contrasting with softer precious and base metals. Market leadership in resource names offered selective support, though sharp declines in several stocks reflected fragile risk appetite. The near-term stance remains cautious, with geopolitics, Inflation expectations and Central Bank signals likely to keep Volatility elevated.
The S&P/ASX 200 declined by 55.70 points in the latest session, forming a small bearish candlestick that reflects softening sentiment and a gradual increase in selling pressure. From a technical standpoint, the index continues to trade below its 21-period Simple Moving Average (SMA), which is acting as a key dynamic resistance and reinforcing the prevailing near-term bearish bias. While the index is attempting to stabilise around current levels, immediate support is seen near 8,620.40. Holding above this level may help limit downside risks in the short term. However, a decisive break below this zone could weaken sentiment further, potentially triggering an extended corrective phase and increasing near-term Volatility.


 Nov 12, 2026





 Please wait processing your request...