
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
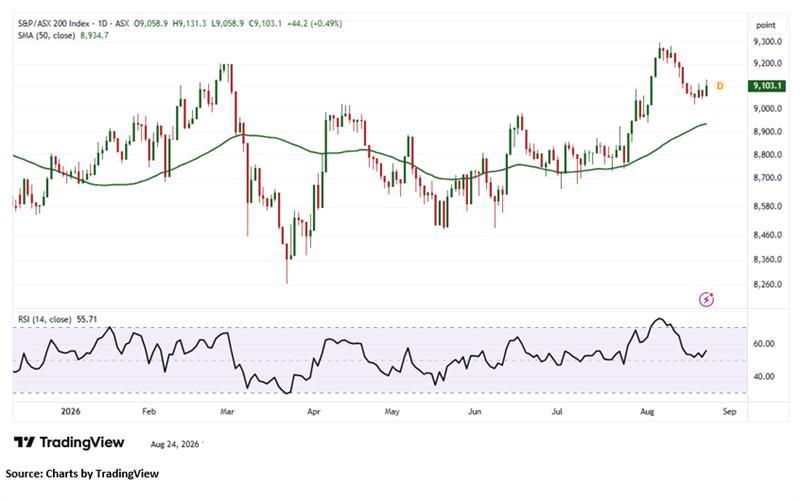
Index Update: The Australian sharemarket finished Monday in positive territory, with the S&P/ASX 200 gaining 44.20 points, or 0.49%, to close at 9,103.10. The benchmark has now advanced 0.33% over the past five sessions and remains 2.08% below its 52-week high.
Market breadth was constructive, with seven of the 11 sectors closing higher. Materials led the gains with a 2.43% rise, extending its five-day advance to 6.30%. Information Technology also added 0.97%, while Health Care gained 0.62% and Energy rose 0.47%. A-REITs, Industrials and Consumer Discretionary finished marginally higher.
Among the weaker sectors, Consumer Staples fell 0.95%, Financials declined 0.72%, Utilities slipped 0.48%, and Telecommunication Services eased 0.45%.
Macro Update: S&P Global Market Intelligence’s August 2026 outlook highlighted continued global economic resilience, with second-quarter growth generally exceeding expectations, particularly in Western Europe. Price pressures also moderated, while Core Inflation remained relatively stable across major economies. Global real GDP growth for 2026 is forecast at 2.4%. The global Manufacturing input price index fell almost 7 percentage points over two months to July. Monetary Policy paths remain divergent, with reduced near-term risk of US Federal Reserve tightening.
Top Market Movers: DATA#3 Limited (ASX:DTL) led the gainers, rising 17.853% or AUD 1.680 to AUD 11.090. Deep Yellow Limited (ASX:DYL) advanced 11.551% or AUD 0.175 to AUD 1.690, while Paladin Energy Ltd (ASX:PDN) climbed 10.586% or AUD 1.120 to AUD 11.700. Among the decliners, nib Holdings Limited (ASX:NHF) fell 9.055% or AUD 0.670 to AUD 6.730, Aussie Broadband Limited (ASX:ABB) dropped 6.535% to AUD 4.720, and Chorus Limited (ASX:CNU) declined 5.647% to AUD 7.520.
Commodity Update: The dollar hovered near multi-month lows on Monday as markets remained cautious following the U.S. Treasury’s plans to buy back longer-dated bonds. Investors also awaited details on potential Iran sanctions and key policy speeches from U.S. and Japanese officials. Gold rose 0.42% to USD 4,698, while silver declined 0.86% to USD 68.93 and copper fell 0.43% to USD 14,144.70. Brent Crude slipped 1.22% to USD 93.17 amid profit-taking and Supply concerns.
Our Stance: The ASX 200’s move above 9,100 was supported by relatively broad participation, with seven sectors advancing and Materials providing the clearest momentum. Gains in Technology, Health Care and Energy added some balance, although weakness across Financials and Consumer Staples kept the session from becoming more decisive. The improving global growth backdrop and moderating price pressures are mildly supportive, while softer commodities outside gold and ongoing policy uncertainty argue for some restraint. Overall, the market tone appears cautiously constructive, with the index holding near recent highs but still requiring broader follow-through to confirm a more durable upward move.
On the technical front, the S&P/ASX 200 Index gained 24.90 points in the latest trading session, reflecting renewed buying interest. The index continues to hold above key support near 9,020, which remains crucial for maintaining the prevailing bullish bias. A sustained hold above this level could support a recovery towards recent highs, while a decisive break below 9,020 would weaken the technical setup and increase downside risk. On the upside, a breakout above the recent swing high near 9,080 would strengthen bullish momentum and could pave the way for further gains towards the next target near 9,140.


 Nov 12, 2026





 Please wait processing your request...