
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Source: Krish Capital Pty Ltd
Index Update: The S&P/ASX 200 closed higher on Friday, gaining 28.30 points or 0.32% to 8,773.50, lifted by Wall Street’s S&P 500 hitting a record high last night. Despite the daily gain, the ASX 200 has fallen 1.03% over the past five trading days and remains 3.10% below its 52-week high. Seven of the 11 sectors ended in positive territory, led by health care (+0.91%), though the sector is still down 1.65% over the past week. Information technology (+0.85%), consumer discretionary (+0.61%), and financials (+0.58%) also rose, while telecommunications services (-0.74%) and consumer staples (-0.38%) dragged on the broader market.
Macro Update: According to the Federal Reserve, economic growth moderated in the first half of the year, with job gains slowing and unemployment edging higher, though still low. Inflation remains elevated. In response, the Committee lowered the federal funds rate target range by 0.25 percentage point to 4–4.25 percent. Policymakers signalled continued balance sheet reduction and stressed vigilance on risks to both employment and inflation, noting elevated uncertainty and a readiness to adjust policy if economic conditions warrant.
Top Market Movers: Top ASX gains in Friday’s session was led by Generation Development Group Limited (ASX:GDG), rising AUD 0.470 to close at AUD 7.40, up 6.78%. Telix Pharmaceuticals Limited (ASX:TLX) added AUD 0.870 to AUD 14.53, a 6.37% increase, while Clarity Pharmaceuticals Ltd (ASX:CU6) advanced AUD 0.210 or 5.95% to AUD 3.74. On the downside, Genesis Minerals Limited (ASX:GMD) fell AUD 0.250 to AUD 5.05 (-4.72%), followed by Iluka Resources Limited (ASX:ILU) down AUD 0.280 (-4.42%) to AUD 6.05, and Data#3 Limited (ASX:DTL) dropping AUD 0.400 or 4.16% to AUD 9.22.
Commodity Update: The U.S. dollar steadied in early Asian trade on Friday, edging up against the yen ahead of the Bank of Japan’s policy decision, as markets sought fresh direction after the Federal Reserve’s rate cut. Gold rose 0.11% to USD 3,682.30, silver gained 0.65% to USD 42.38, and copper advanced 0.33% to USD 9,982.30. Brent crude slipped 0.12% to USD67.36, pressured by concerns over U.S. fuel demand.
Our Stance: Markets remain cautiously optimistic following a modest rebound in the ASX 200, driven by record highs on Wall Street. However, underlying weakness persists, with the index still trailing its recent peak. Sector performance is mixed, and macroeconomic signals from the U.S.—including a rate cut and slower job growth—suggest increasing downside risks. Inflation remains sticky, prompting central banks to tread carefully. Commodity markets reflect this uncertainty, with metals inching higher while crude softens. Equities may see continued volatility as investors reassess growth prospects amid tightening financial conditions and evolving policy outlooks across major economies.
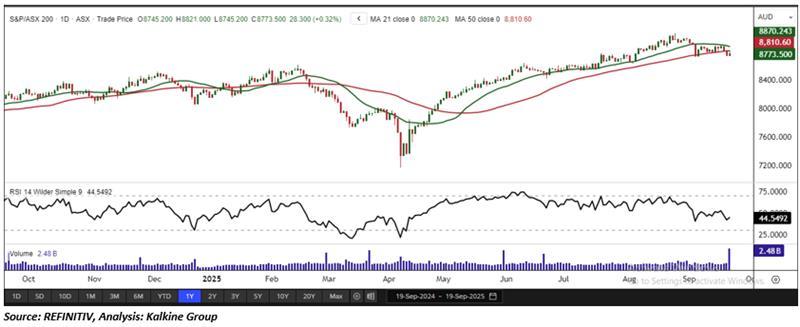
In its latest session, the S&P/ASX 200 Index advanced 28.30 points to close at 8,773.50, supported by a bullish candlestick formation and strong trading volumes clear signals of sustained investor confidence. On the daily chart, the index remains below its 21-period Simple Moving Average (SMA), which continues to act as dynamic resistance and prevailing negative short-term outlook. A key support zone sits near 8,700; holding above this level is critical to preserving the current uptrend structure. On the upside, a decisive breakout above the 21-SMA would provide strong bullish confirmation, potentially unlocking further upward momentum and shifting sentiment more firmly in favor of the bulls. From a broader perspective, the index’s sustained position above the 50-period SMA on the weekly chart highlights its resilient long-term bullish foundation, reinforcing strength across multiple timeframes.


 Nov 12, 2026





 Please wait processing your request...