
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed Wednesday 80.00 points, or 0.92%, higher at 8,789.30, as Australian equities rallied following softer-than-expected August Inflation data. The inflation reading eased concerns around the prospect of a more aggressive tightening cycle from the Reserve Bank of Australia, supporting broad-based gains across the market. The benchmark has now advanced 0.27% over the past five sessions, while remaining virtually unchanged year to date.
Ten of the 11 sectors finished in positive territory. A-REITs led the advance, climbing 3.60%, followed by Consumer Discretionary at 2.27%, Telecommunication Services at 1.94%, Industrials at 1.65% and Energy at 1.56%. Healthcare gained 0.71%, Materials rose 0.67%, Consumer Staples added 0.57%, Utilities advanced 0.48% and Financials edged 0.27% higher. Information Technology was the sole sector in the red, declining 0.41%.
Macro update: Australia’s Consumer Price index (CPI) rose 4.0% in the 12 months to August 2026, accelerating from 3.5% in July, according to the Australian Bureau of Statistics. Housing was the largest contributor, rising 5.7%, as new dwelling and electricity costs increased. Transport prices climbed 5.6%, with automotive fuel prices jumping 14.8% during August amid higher global oil prices and the unwinding of fuel excise relief. Meanwhile, trimmed mean inflation remained steady at 3.6% for the third consecutive month.
Top Market Movers: Lendlease Group (ASX:LLC) led the gainers, rising 11.30% to AUD 2.66, followed by Karoon Energy Ltd (ASX:KAR), which advanced 8.97% to AUD 1.58. Charter Hall Group (ASX:CHC) gained 6.43% to AUD 18.86. Among the decliners, Develop Global Limited (ASX:DVP) fell 10.00% to AUD 4.50, while Deep Yellow Limited (ASX:DYL) declined 5.26% to AUD 1.17. Pinnacle Investment Management Group Limited (ASX:PNI) dropped 4.87% to AUD 13.28.
Commodity Update: The Dollar Index remained elevated on Wednesday as pressure in the U.S. Treasury Bond Market eased somewhat. Currency markets stayed cautious, although expectations for further Federal Reserve rate hikes softened following a positive remark from a policymaker. The Australian dollar fell to a two-month low, while sterling hovered near a three-month low. Gold advanced 0.80% to USD 4,213.00, silver rose 0.49% to USD 61.46, and copper gained 0.33% to USD 14,505.00. Brent Crude increased 0.60% to USD 103.16.
Our Stance: The ASX 200 ended Wednesday on a broadly positive footing, with gains across ten of 11 sectors signalling improved market sentiment. A-REITs led the advance, while Consumer Discretionary, Telecommunication Services, Industrials and Energy also contributed to the index rise. Inflation remains a key consideration, with annual CPI accelerating to 4.0% in August while trimmed mean inflation held at 3.6%. Meanwhile, gains across gold, silver, copper and Brent crude provided a supportive Commodity backdrop. Overall, the session reflected broad buying interest, although persistent inflation and currency weakness remain important factors for investors to monitor.
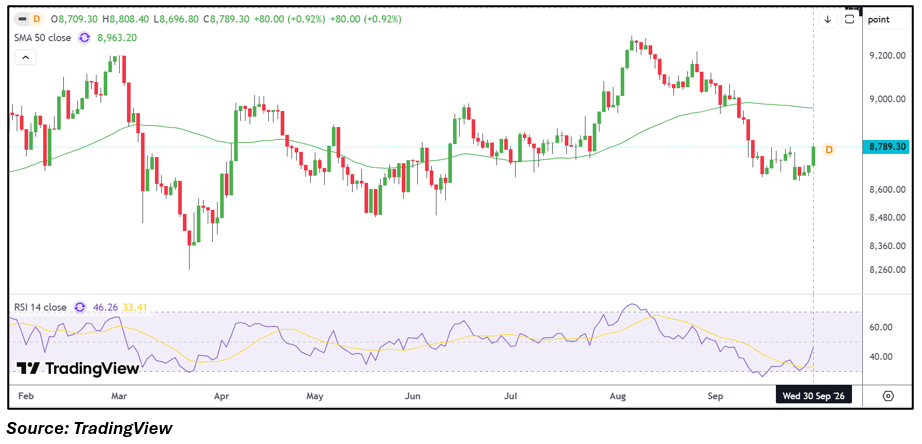
The S&P/ASX 200 Index closed at 8,789.30, gaining 0.92% in the latest Trading session and recovering from recent weakness. The index remains below its 50-day Simple Moving Average of 8,963.20, keeping the broader short-term structure subdued. The 14-day Relative Strength Index stood at 46.26, reflecting neutral momentum. Support is positioned near 8,680, while resistance is around 8,880. A sustained move above 8,880 could improve the near-term structure, while continued trading below this area may keep the index within its recent range.


 Nov 12, 2026





 Please wait processing your request...