
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Image Source : Krish Capital Pty Ltd
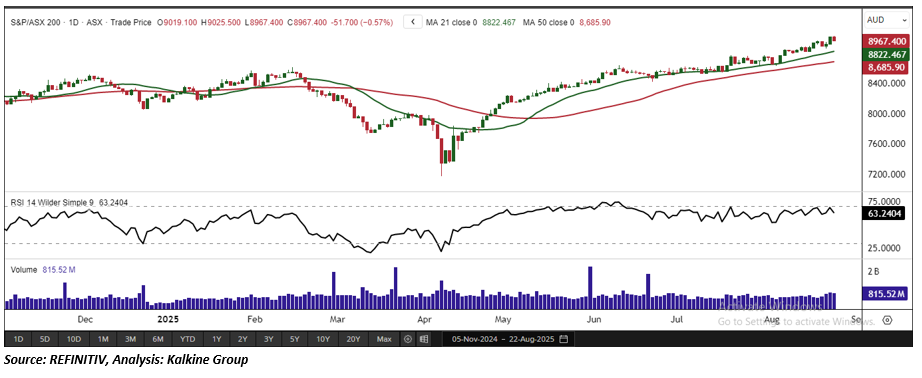
Index Update: The S&P/ASX 200 retreated from record highs on Friday, closing down 51.70 points, or 0.57%, at 8,967.40, after hitting a fresh 100-day peak earlier in the session. Despite the drop, the index has gained 0.32% over the past five sessions and remains just 0.64% below its 52-week high. Sector performance was mixed, with seven of eleven sectors ending lower. Health Care (-2.35%) and Consumer Staples (-2.02%) led the declines, while Energy (+0.34%) and Information Technology (+0.29%) posted gains. Markets now await comments from the U.S. Federal Reserve Chair for direction.
Macro Update: Ukraine’s President Zelensky has urged allies to intensify pressure on Russia after one of the war’s largest overnight bombardments, which damaged homes, factories, and gas infrastructure. Meanwhile, in Gaza, Palestinians have fled parts of Gaza City after Israel has begun the first stages of a planned ground offensive. Prime Minister Netanyahu has said Israel will negotiate to free all hostages and end the war on terms acceptable to Israel, following Hamas’s acceptance of a ceasefire proposal, while 27 countries have called for independent foreign media access. Judge Frank Caprio has died this week.
Top Market Movers: On the ASX, Zip Co Limited (ASX: ZIP) led the gainers, surging 20.19% to AUD 3.75 after a strong rally. Codan Limited (ASX: CDA) followed with an 8.17% rise to AUD 28.34, while Boss Energy (ASX: BOE) advanced 5.85% to AUD 1.72. On the downside, Inghams Group (ASX: ING) slumped 20.28% to AUD 2.83, marking the sharpest fall of the session. Guzman y Gomez (ASX: GYG) tumbled 18.19% to AUD 23.70, and Regis Resources (ASX: RRL) slipped 8.95% to AUD 4.07.
Commodity Update: The U.S. dollar stayed firm on Friday, on track for a strong weekly close ahead of Fed Chair Jerome Powell’s Jackson Hole speech that may shape rate outlook. Gold slipped 0.15% to USD 3,376.60, silver edged up 0.03% to USD 38.09, and copper eased 0.02% to USD 9,731.55. Brent crude fell 0.20% to USD 67.51 but was still set for weekly gains as stalled Russia-Ukraine peace talks heightened supply concerns.
Our Stance: The ASX ended the week softer, with the S&P/ASX 200 slipping 0.57% from record levels as investors turned cautious ahead of the Fed Chair’s Jackson Hole remarks. While Energy and IT eked out modest gains, sharp losses in Health Care and Consumer Staples weighed on sentiment. Stock-specific moves were volatile, with Zip Co’s 20% surge contrasting against a 20% plunge in Inghams Group. Globally, geopolitical risks remain elevated, from renewed Russian bombardments in Ukraine to escalating ground operations in Gaza. Commodities reflected the uncertainty, with gold edging lower and oil steady, underscoring investor caution in a fragile macro backdrop.
The S&P/ASX 200 Index endured a challenging session, closing down 51.70 points and forming a bearish candlestick pattern on elevated trading volume. Despite the pullback, the index continues to hold above its 50-period Simple Moving Average (SMA) on the daily chart—a key support level closely monitored by market participants. A crucial support zone is identified near 8,880.70. Sustaining this level could help consolidate recent gains and reinforce confidence in the index’s upward trajectory. On a broader view, the index also trades above its 21-period SMA on the weekly chart, signaling the potential for sustained bullish momentum. The alignment of these technical signals across multiple timeframes underscores the index’s underlying resilience, supporting a broadly positive outlook despite near-term volatility.


 Nov 12, 2026





 Please wait processing your request...