
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
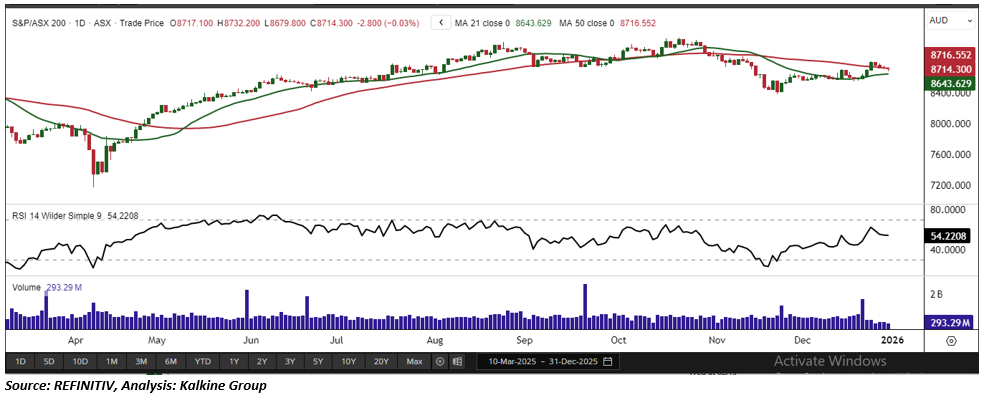
Index Update: The S&P/ASX 200 edged down 2.80 points on Wednesday to close at 8,714.30, as late-year selling pressure pushed the Australian sharemarket toward its weakest annual increase in three years. Mining stocks provided some support, particularly those leveraged to higher precious metals prices, while healthcare and technology shares weighed on overall performance. The benchmark has fallen 0.55% over the past five days and remains 4.40% below its 52-week high. Sector performance was mixed, with five sectors ending higher and six lower, as energy led the market, gaining 0.75% on the day and rising 0.76% over the past week. The benchmark index posted a gain of 6.8% in 2025 lead by Materials.
Macro Update: Minutes from the Federal Reserve’s December policy meeting showed that most officials considered additional interest-rate reductions appropriate if inflation continues to decline, though views differed on the timing and scale of any cuts. The record of the Dec. 9–10 Federal Open Market Committee gathering, released Tuesday in Washington, highlighted the challenges policymakers faced in reaching their decision and modestly reinforced expectations that the central bank will keep rates unchanged when it meets again in January.
Top Market Movers: On the Australian market, Silex Systems Limited (ASX:SLX) led gains, rising AUD 0.320 or 3.85% to close at AUD 8.63, followed by IDP Education Limited (ASX:IEL), which added AUD 0.150 or 2.66% to AUD 5.78. DigiCo Infrastructure REIT (ASX:DGT) advanced AUD 0.070 or 2.60% to AUD 2.76. On the downside, Telix Pharmaceuticals Limited (ASX:TLX) fell AUD 0.420 or 3.62% to AUD 11.20, while Deterra Royalties Limited (ASX:DRR) declined AUD 0.120 or 2.86% to AUD 4.07. Mesoblast Limited (ASX:MSB) eased AUD 0.080 or 2.86% to AUD 2.72.
Commodity Update: Major currencies traded in narrow ranges on Wednesday amid thin year-end volumes, as investors awaited Federal Reserve meeting minutes for policy cues into 2026. Regional FX activity stayed muted. Gold fell 0.49% to USD 4,364.65, silver dropped 5.26% to USD 73.82, and copper eased 0.68% to USD 12,549.00. Brent crude slipped 0.20% to USD 61.23, with oil down over 10% in 2025 amid supply-demand imbalances.
Our Stance: Australian equities ended the session modestly lower as late-year positioning and mixed sector performance kept the S&P/ASX 200 near recent lows, with support from miners offset by weakness in healthcare and technology. Market moves reflected cautious sentiment rather than a single dominant driver, while energy stocks provided relative stability. Offshore, US policy signals remained a key macro influence, as Federal Reserve minutes pointed to openness toward future rate cuts but no urgency to adjust policy in January, reinforcing a wait-and-see backdrop. Stock-specific moves in Australia were pronounced, with gains in industrials and education contrasted by declines in healthcare and resources. In commodities, softer precious metals and subdued oil prices highlighted lingering demand and supply uncertainties, suggesting markets may enter the new year with a measured and selective tone.
In its latest session, the S&P/ASX 200 Index declined 2.80 points, forming a small bearish candlestick on rising trading volume a combination that signals increased investor caution and reinforces the prevailing short-term bearish tone. On the daily chart, the index continues to trade above its 21-period Simple Moving Average (SMA), which remains a key area of immediate support. Immediate support is positioned near the 8,640 level, and holding above this zone will be crucial for stabilising recent price action and restoring near-term confidence. From a broader weekly perspective, however, the index continues to trade above its 50-period SMA, a constructive long-term signal that points to the potential for renewed upside momentum once short-term selling pressure begins to ease.


 Nov 12, 2026





 Please wait processing your request...