
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 retreated sharply on Tuesday, pulling back from record territory as escalating tensions in the Middle East dampened investor risk appetite and surging oil prices revived inflation concerns. The benchmark index fell 123.60 points, or 1.34%, to close at 9,077.30. Despite the decline, the index remains up 0.61% over the past five sessions and sits 1.36% below its 52-week high, suggesting recent gains have partially cushioned the pullback. Market breadth was broadly negative, with nine of the 11 sectors finishing lower alongside the broader index. Energy was the standout performer, rising 1.41% on the day and 7.31% over the past five sessions as higher crude prices supported buying interest, while the worst-performing sector, materials, slumped 3.09%.
Macro Update: Oil markets extended their advance for a third consecutive session on Tuesday as escalating U.S.–Israeli hostilities with Iran intensified concerns over potential supply disruptions in the Middle East. Brent crude climbed nearly 2% to trade above USD 79.82 per barrel, building on a rally in the previous session, as investors weighed the growing risk of shipping constraints or a possible shutdown of the Strait of Hormuz — a critical artery for global energy flows. The conflict broadened overnight, with Israeli strikes reported in Lebanon and Iran retaliating with attacks targeting Gulf energy infrastructure and tankers transiting the region, amplifying fears of a prolonged disruption. Meanwhile, gold prices surged to around USD 5,382.40 per ounce, following upon previous day rally.
Top Market Movers: Top gainers on the ASX were led by Magellan Financial Group Ltd (ASX:MFG), which surged to AUD 10.310, up AUD 1.850 (21.867%). New Hope Corporation Limited (ASX:NHC) rose to AUD 5.100, gaining AUD 0.350 (7.368%). Yancoal Australia Limited (ASX:YAL) rose to AUD 6.490, increasing by AUD 0.300 (4.846%).
On the downside, Life360 Inc. (ASX:360) dropped to AUD 20.360, dropping AUD 4.36 (17.638%). Pro Medicus Limited (ASX:PME) fell to AUD 114.280, down AUD 11.340 (9.028%). Liontown Resources Limited (ASX:LTR) slipped to AUD 1.565, losing AUD 0.155 (9.012%).
Commodity Update: Gold extended its advance in Asian trade, marking a fourth consecutive gain as escalating Middle East tensions supported safe-haven demand, though a firmer U.S. dollar limited sharper upside. Gold climbed 1.32% to USD 5,382.40, silver rose 1.68% to USD 90.35, and copper added 1.01% to USD 13,242.00. Brent crude advanced 2.00% to USD 79.28, following a prior 7% surge amid Strait of Hormuz supply concerns.
Our Stance: The Australian share market retreated sharply from record territory, with the S&P/ASX 200 falling 1.34% to 9,077.30 as escalating Middle East tensions dampened investor risk appetite and reignited inflation concerns through higher oil prices. While the index remains modestly higher over the past five sessions and only 1.36% below its 52-week high, market breadth weakened significantly, with nine of 11 sectors closing lower and Materials tumbling 3.09%. Energy provided the lone area of strength, climbing 1.41% on the day and more than 7% over the week as Brent crude pushed toward USD 80 per barrel amid fears of supply disruption through the Strait of Hormuz. Safe-haven demand also intensified, with gold extending gains, underscoring a shift toward defensive positioning. The current backdrop suggests the market’s resilience is being tested, with near-term direction increasingly tied to geopolitical developments, commodity price momentum, and evolving inflation expectations.
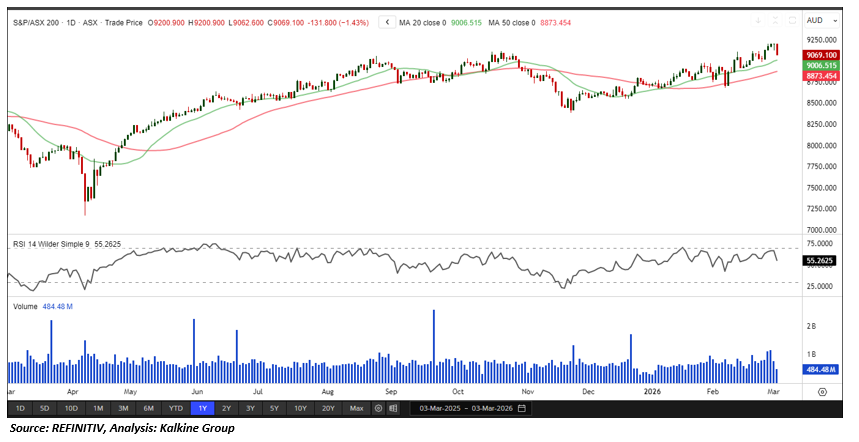
The S&P/ASX 200 fell 131.80 points in its latest session, printing a bearish candlestick on increased volume—an indication of rising investor caution and sustained short-term weakness. Despite the pullback, the index continues to hold above its 50-period Simple Moving Average (SMA) on the daily chart, which remains a crucial near-term support level. Immediate support is seen around 9,000, and maintaining this zone will be vital to stabilise sentiment and prevent deeper downside. From a broader perspective, the index remains above its 50-period SMA on the weekly timeframe, signalling that the longer-term trend remains constructive and that renewed upside momentum could emerge once short-term selling pressure subsides.


 Nov 12, 2026





 Please wait processing your request...