
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 ended flat on Friday, slipping just 3.20 points to close at 8,614.10. Global optimism continued to build on expectations that the US Federal Reserve may cut interest rates next month. Despite the muted finish, the index advanced 2.35% over the past five sessions and is up 5.58% year-to-date. Market performance was mixed, with eight of 11 sectors finishing higher. Consumer Staples emerged as the strongest performer, rising 1.25% on the day and 1.81% across the week. In contrast, the financial sector registered the steepest decline, falling almost 0.72% as Commonwealth Bank, National Australia Bank, and ANZ each retreated by around 1%.
Macro Update: Expectations of further U.S. monetary easing next month pushed the dollar toward its poorest weekly performance since July. On Friday, the currency market faced even greater illiquidity, already thinned by the Thanksgiving holiday, after a CME Group outage suspended trading in several currency pairs.
Top Market Movers: Among Friday’s top performers, HMC Capital Ltd (ASX:HMC) led the gains, advancing 9.01% to AUD 3.870. Temple & Webster Group Ltd (ASX:TPW) followed with a rise of 7.40% to AUD 15.520, while Flight Centre Travel Group Ltd (ASX:FLT) added 6.54% to close at AUD 13.530. On the declines side, Eagers Automotive Ltd (ASX:APE) recorded the sharpest drop, falling 3.72% to AUD 28.480. Suncorp Group Ltd (ASX:SUN) declined 3.57% to AUD 17.560, and Centuria Capital Group (ASX:CNI) eased 3.48% to AUD 2.220.
Commodity Update: The U.S. dollar headed for its weakest week since July as expectations grew for a Fed rate cut next month amid thin Thanksgiving trading. Gold rose 0.76% to USD 4,221.65, silver gained 1.98% to USD 54.23, and copper added 0.60% to USD 11,006. Brent crude held steady at USD 63.34, with markets awaiting updates from Russia-Ukraine peace efforts and Sunday’s OPEC+ meeting for supply cues.
Our Stance: Market conditions continue to reflect cautious optimism, supported by expectations of near-term U.S. monetary easing. Equity performance remains resilient despite sector-level divergence, with defensives showing relative strength while financials face pressure. Currency weakness in the U.S. dollar signals shifting rate expectations, though recent illiquidity highlights ongoing volatility risks. Commodity markets appear broadly constructive, with gains in precious metals and stable energy prices ahead of key geopolitical and OPEC+ developments. Overall, the environment suggests a constructive but measured outlook, with opportunities emerging in selective sectors while maintaining awareness of global policy and liquidity dynamics.
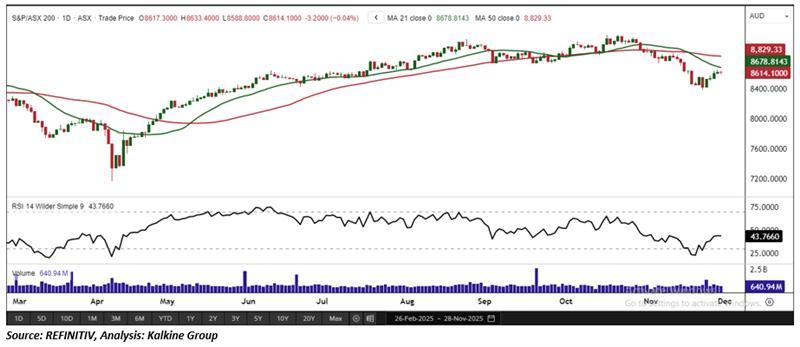
In its latest session, the S&P/ASX 200 Index slipped 3.20 points, forming a small bearish candlestick on rising trading volume—a combination that signals heightened investor caution and reinforces the prevailing short-term bearish tone. The index continues to trade below its 50-period Simple Moving Average (SMA) on the daily timeframe, keeping this indicator as a key zone of immediate resistance. Key support remains positioned near 8,540, and holding above this level will be essential for stabilizing recent price action and helping rebuild market confidence. From a broader weekly perspective, however, the index continues to trade above its 50-period SMA, a constructive long-term signal that suggests the potential for sustained upward momentum once near-term selling pressure begins to ease.


 Nov 12, 2026





 Please wait processing your request...