
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The Australian sharemarket surged to a new intraday high on Thursday, with financials, healthcare, and real estate stocks leading the rally following a surprisingly weak jobs report that fueled expectations of an imminent Reserve Bank rate cut. The S&P/ASX 200 closed up 77.50 points, or 0.86%, at 9,068.40, marking a fresh 100-day high. Over the past five trading days, the index has risen 1.10% and remains just 0.45% below its 52-week peak. Nine of the 11 sectors closed higher, with A-REITs outperforming, climbing 2.82% on the day and 2.42% over the week.
Macro Update: Australia’s unemployment rate unexpectedly jumped to 4.5% in September, prompting bond investors to swiftly anticipate a potential interest rate cut by the Reserve Bank of Australia next month. Economists had forecast a smaller rise from 4.2% to 4.3%, but the stronger-than-expected figure, the highest in four years, led to a fall in the Australian dollar, a surge on the ASX, and the largest single-day drop in bond yields since early August.
Meanwhile, the ongoing two-week U.S. federal government shutdown could cost the economy as much as USD 15 billion per week in lost output, according to the Treasury Department. The revised estimate corrected an earlier statement suggesting a daily loss. Treasury Secretary Scott Bessent noted that while investment momentum, particularly in artificial intelligence, remains strong, the shutdown poses growing risks. He added that the 2025 fiscal deficit was smaller than last year’s USD 1.833 trillion shortfall.
Top Market Movers: The ASX saw notable movers today, with HUB24 Limited (ASX: HUB) leading gains, surging 10.53% to AUD 112.64, followed by AMP Limited (ASX: AMP), up 8.52% to AUD 1.91, and Genesis Minerals Limited (ASX: GMD), which climbed 8.00% to AUD 7.02. On the downside, Iluka Resources Limited (ASX: ILU) fell 10.56% to AUD 8.30, IperionX Limited (ASX: IPX) dropped 7.36% to AUD 8.43, and HMC Capital Limited (ASX: HMC) declined 5.80% to AUD 3.41.
Commodity Update: The U.S. dollar weakened on Thursday amid concerns over the Sino-U.S. trade tensions and growing expectations of a Federal Reserve rate cut this year. Precious metals gained, with gold up 1.24% to USD 4,243.70 and silver advancing 2.80% to USD 52.80. Copper edged higher by 0.16% to USD 10,637.15. Brent crude rose 1.10% to USD 62.57, supported by expectations of tighter supplies after President Trump said India would halt oil imports from Russia.
Our Stance: Thursday’s market action highlights the delicate balance between domestic economic surprises and global macro pressures. The unexpected jump in Australia’s unemployment to 4.5% spurred hopes of a Reserve Bank rate cut, lifting the ASX 200 to a fresh 100-day high, led by financials, healthcare, and A-REITs. While top gainers like HUB24 (ASX: HUB) reflect investor optimism, declines in Iluka (ASX: ILU) and IperionX (ASX: IPX) suggest sector-specific pressures remain. Globally, the U.S. shutdown and Fed rate expectations continue to influence commodity prices. Overall, markets appear to be pricing in supportive policy, but volatility may persist as macro uncertainties unfold.
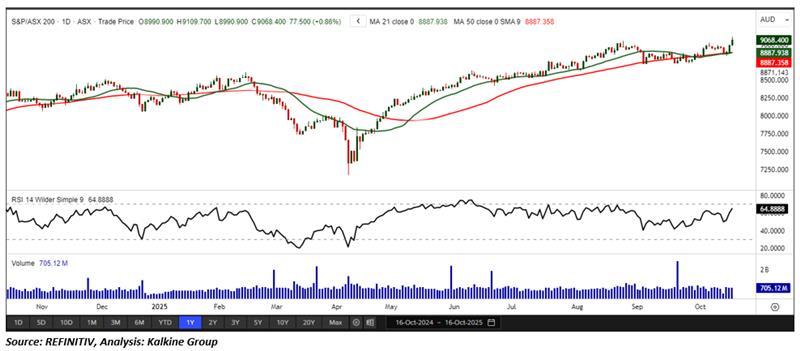
In its latest session, the S&P/ASX 200 Index advanced 77.50 points to close at 9,068.40, supported by a bullish candlestick and strong trading volumes clear indicators of sustained investor confidence. On the daily chart, the index remains above its 50-period Simple Moving Average (SMA), which continues to act as dynamic support. A key support zone is identified near 8,960.50, and maintaining levels above this threshold is crucial for preserving the current uptrend. Sustaining this support could enable the index to consolidate recent gains and further reinforce confidence in the broader upward trend. From a weekly perspective, the index also remains above its 21-period SMA, a constructive technical setup that suggests the potential for continued momentum over the longer term, provided near-term support levels hold firm.


 Nov 12, 2026





 Please wait processing your request...