
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed higher on Thursday, adding 23.20 points or 0.27% to finish at 8,618.40. Over the past five sessions, the index has been largely flat, while it remains up 5.63% year to date. Despite the positive close, more sectors declined than advanced. Materials was the best-performing sector, rising +0.95% and extending its five-day gain to +2.71%. In contrast, A-REITs registered the weakest performance with a decline of –2.16%.
The broader market was supported by gains in mining stocks as copper prices surged, though this was partly offset by pressure on the real estate sector after stronger-than-expected monthly household spending data increased the likelihood of an interest rate hike in early 2026.
Macro Update: Household spending increased by 1.3 per cent in October, based on seasonally adjusted data released by the Australian Bureau of Statistics (ABS). This follows a 0.3 per cent rise in September and marks the largest monthly increase since January 2024. Overall household spending is now 5.6 per cent higher compared with the same period last year.
In the September 2025 quarter, residential mortgage values increased by AUD 1.5 billion (1.0%) to reach AUD148.2 billion. Additionally, the value of asset-backed long-term debt securities issued domestically rose by AUD 2.6 billion (1.4%) to AUD185.4 billion.
Top Market Movers: Capstone Co. (ASX:CSC) led the gainers, climbing to AUD 14.250 after an increase of 8.036%. HMC Capital Ltd (ASX:HMC) advanced to AUD 3.570, up 5.000%. Rio Tinto Limited (ASX:RIO) rose 3.917% to AUD 140.580. On the declines side, Liontown Resources Ltd (ASX:LTR) slipped 5.971% to AUD 1.260. Regis Resources Ltd (ASX:RRL) fell to AUD 7.000, down 5.021%, while Iluka Resources Ltd (ASX:ILU) edged lower by 4.827% to AUD 6.310.
Commodity Update: The U.S. dollar weakened after soft data reinforced expectations of a Fed rate cut next week, lifting the yen and pushing the euro to a nearly seven-week high. Gold down 0.23% to USD 4,222.70, silver gained 0.17% to USD 58.735, and copper inched up 0.06% to USD 11,487.00. Brent crude up 0.43% to USD 62.94 as geopolitical risks from Ukrainian strikes on Russian oil sites supported prices, though fragile fundamentals capped upside.
Our Stance: The S&P/ASX 200 closed higher on Thursday, though the modest gain came alongside broad sector softness. Materials provided the key support as copper-driven momentum lifted major miners, while A-REITs weakened amid renewed rate-hike expectations following stronger-than-expected October household spending. Macro data showed rising consumer activity and steady credit expansion through the September quarter, adding to speculation around tighter policy ahead. Globally, a softer U.S. dollar aided commodity, with silver and copper inching up despite a slight dip in gold. Overall, sentiment remains balanced, with investors navigating firmer domestic spending and commodity resilience against the prospect of higher interest rates early next year.
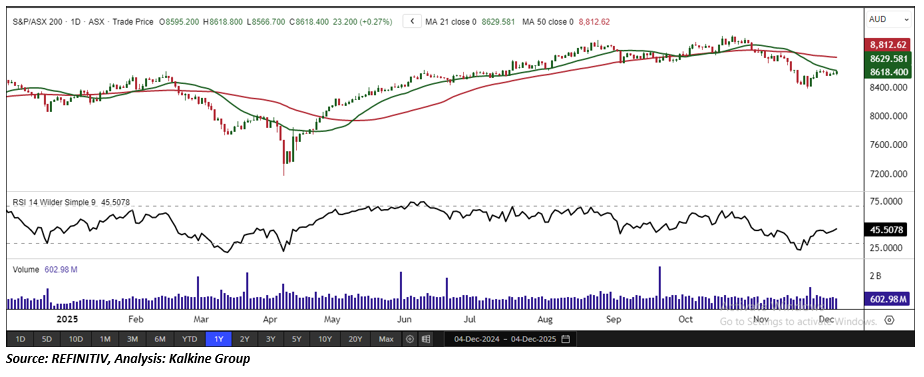
In its latest session, the S&P/ASX 200 Index advanced 23.20 points to close at 8,618.40, supported by a small bullish candlestick formation and strong trading volumes, both signaling sustained investor confidence. On the daily chart, the index continues to trade below its 21-period Simple Moving Average (SMA), which remains a key dynamic resistance level. A critical support zone is located near 8,530.50, and holding above this area is essential for maintaining the current bullish structure. Successfully defending this level would allow the index to consolidate recent gains while strengthening confidence in the broader upward trajectory. From a weekly perspective, the index trades comfortably above its 50-period SMA, reinforcing a constructive longer-term outlook. Overall, the technical setup points to the potential for continued upside momentum, provided near-term support levels remain intact.


 Nov 12, 2026





 Please wait processing your request...