
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
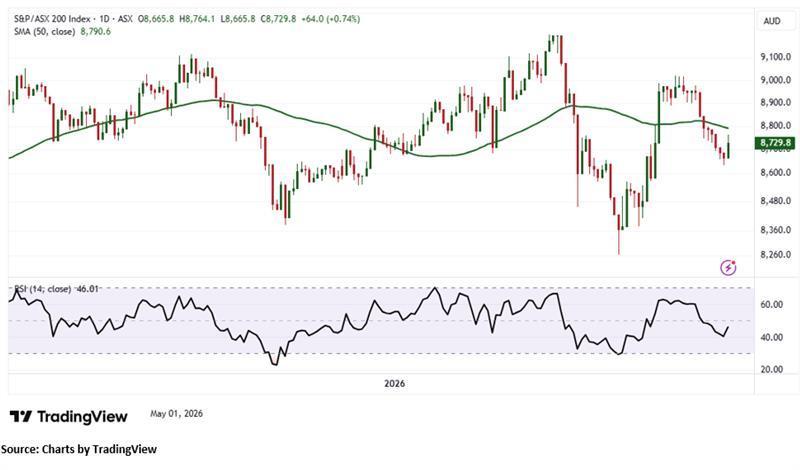
Index Update: The S&P/ASX 200 closed higher on Friday, rising 64.00 points or 0.74% to 8,729.80, marking its first gain in nine sessions. Australian equities advanced as the new month began, with easing oil prices and US corporate earnings supporting sentiment. The index is down 0.65% over the past five days and remains broadly flat year to date. Ten of eleven sectors ended higher, led by materials, which gained 2.09%.
Macro Update: According to data released by the Australian Bureau of Statistics, final demand (excluding exports) rose 0.4% in the March quarter and 3.0% over the year. Manufacturing output increased 2.1%, while building construction rose 1.0%. Education and training prices also increased, with higher education export fees up 5.4%. Growth was driven by construction and services demand, with property operators (+1.0%), petroleum refining (+10.1%), and tertiary education (+2.2%) contributing to the quarterly rise.
Top Market Movers: Among gainers, Liontown Limited (ASX:LTR) rose to AUD 2.640, up AUD 0.290 or 12.34%. IperionX Limited (ASX:IPX) advanced to AUD 4.500, gaining AUD 0.400 or 9.756%. NexGen Energy (Canada) Ltd (ASX:NXG) increased to AUD 17.350, up AUD 1.030 or 6.311%. Among decliners, ResMed Inc (ASX:RMD) fell to AUD 28.730, down AUD 1.050 or 3.526%. ANZ Group Holdings Limited (ASX:ANZ) dropped to AUD 35.610, losing AUD 1.040 or 2.838%, while SiteMinder Limited (ASX:SDR) declined to AUD 2.960, down AUD 0.080 or 2.632%.
Commodity Update: The Japanese yen slipped slightly against the U.S. dollar on Friday but remained on track for its sharpest weekly gain in over two months, supported by intervention from Japanese authorities after touching near two-year lows. Gold edged up 0.02% to USD 4,630.40, silver advanced 0.84% to USD 74.64, and copper gained 0.47% to USD 13,075.60. Brent crude climbed 1.08% to USD 111.59 amid stalled Iran conflict negotiations and continued Strait of Hormuz disruptions.
Our Stance: Australian equities snapped a prolonged losing streak, with the S&P/ASX 200 posting a modest rebound supported by easing oil prices and steady US earnings sentiment. Broad-based sector gains, led by materials, indicate improving risk appetite despite recent weakness. Economic data points to stable domestic demand, driven by construction and services, alongside rising education-related exports. However, mixed commodity signals and ongoing geopolitical tensions continue to cloud the outlook. Strength in select resource stocks highlights resilience, while declines in healthcare and financials suggest uneven momentum. Near-term direction may remain cautious as markets balance macro stability with external uncertainties and commodity price volatility.
The S&P/ASX 200 gained 64.00 points in the latest session, forming a bullish candlestick that signals short-term buying interest. Despite this upward move, the index continues to trade below its 50-period Simple Moving Average (SMA), which is acting as a dynamic resistance level and maintaining a cautious near-term outlook. This suggests that the broader trend remains under pressure, even as prices attempt to stabilise. Immediate support is seen near the 8,630 level, which may help limit downside risks in the short term if it holds firm. However, a decisive break below this support could trigger increased selling pressure, potentially leading to a more pronounced corrective phase and a rise in market volatility in the sessions ahead.


 Nov 12, 2026





 Please wait processing your request...