
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
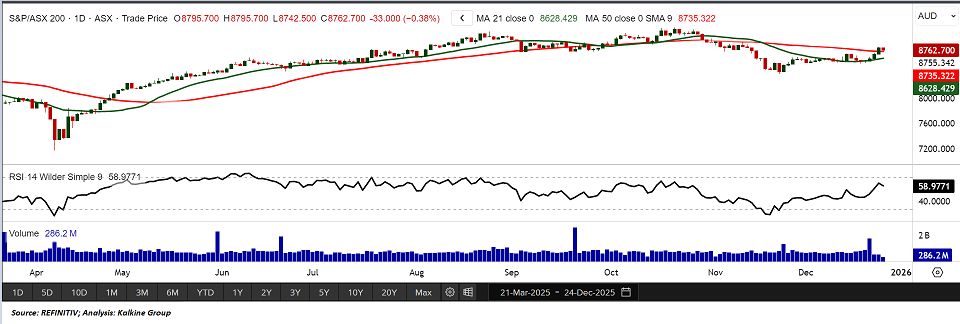
Index Update: The S&P/ASX 200 closed lower on Wednesday, falling 33.00 points, or 0.38%, to 8,762.70 after touching a new 20-day high earlier in the session. Despite the decline, the benchmark has risen 2.07% over the past five trading days and remains 3.87% below its 52-week high. The Australian share market eased in a shortened trading session as local stocks failed to mirror gains on Wall Street and across Asia, following data showing the US economy expanded at its fastest pace in two years.
Market performance was mixed, with 10 of the 11 sectors ending in negative territory alongside the index. Materials was the only sector to finish higher, edging up 0.29% and lifting its five-day gain to 2.93%, while healthcare recorded the largest sector decline, down 1.60%.
Macro Update: Driven by a surge in consumer demand and a significant recovery in exports, the U.S. economy achieved its most rapid expansion in two years during the third quarter. According to data from the Commerce Department, this better-than-anticipated GDP growth was further bolstered by increased government defense spending and corporate investment in equipment and artificial intelligence. While households ramped up spending on international travel, vehicles, and recreational goods at the fastest rate in nearly a year, the economy faced downward pressure from declining inventories and a sluggish housing market. Despite these gains, overall momentum suggests a recent slowdown as the market grapples with the impact of a government shutdown and an escalating cost of living.
Top Market Movers:
Australian equities delivered mixed results in the latest session. Treasury Wine Estates (ASX:TWE) topped the gainers, climbing 7.58% to AUD 5.390, followed closely by IperionX Limited (ASX:IPX), which advanced 7.54% to AUD 5.560, and PLS Group Limited (ASX:PLS), up 6.31% to AUD 4.380. On the downside, Imdex Limited (ASX:IMD) fell 3.61% to AUD 3.470, Charter Hall Group (ASX:CHC) slipped 3.20% to AUD 24.520, and IDP Education (ASX:IEL) declined 2.82% to AUD 5.850.
Commodity Update: The U.S. dollar moved toward its weakest annual performance in over 20 years as investors bet the Federal Reserve could cut rates further in 2026, while some global peers eye hikes. Commodities strengthened, with gold rising 0.12% to USD 4,513.15, silver up 1.28% to USD 72.05, and copper gaining 0.40% to USD 12,101. Brent crude edged 0.10% higher to USD 62.42, supported by U.S.–Venezuela tensions and resilient U.S. growth, despite thin holiday trading volumes.
Our Stance: The pullback in the ASX 200 reflects consolidation rather than a shift in trend, following recent gains and a test of short-term highs. Broad-based sector weakness suggests investors are locking in profits amid mixed global signals, despite resilient macro data from the United States. Strength in materials and commodities highlights ongoing support from resource demand, while healthcare and defensives face near-term pressure. With U.S. growth strong but momentum moderating and policy uncertainty lingering, markets appear cautious rather than risk-off. Near-term direction is likely to remain range-bound, with volatility driven by global data, currency moves, and sector rotation.
In the latest session, the S&P/ASX 200 Index declined 33.00 points to close at 8,762.70, forming a bearish candlestick on strong volumes, indicating active market participation despite the pullback. On the daily chart, the index continues to trade above its 50-period SMA, which remains an important short-term dynamic support. Immediate support is seen near 8,550.70, and holding above this level is crucial to preserve the near-term positive structure. On a weekly basis, the index stays comfortably above its 50-period SMA, reinforcing a constructive medium- to long-term outlook. Overall, the broader technical setup suggests the potential for further upside as long as key support levels remain intact.


 Nov 12, 2026





 Please wait processing your request...