
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed lower on Friday, falling 58.40 points or 0.65% to 8,869.10. Over the past five days, the index remained largely unchanged but stood 2.70% below its 52-week high. Six of eleven sectors ended higher, led by Health Care, which rose 1.05% and gained 0.11% over the week. The market recorded its sharpest fall in nearly two weeks as gold miners sold off after bullion prices slumped.
Macro Update: According to data released today by the Australian Bureau of Statistics, final demand (excluding exports) rose 0.8% in the December 2025 quarter and increased 3.5% over the past twelve months. Final demand measures price changes for goods and services consumed without further processing. The rise was driven mainly by growth across services and construction, with higher residential rental and house construction demand lifting prices. Seasonal strength and major sporting events also supported higher short-term accommodation prices.
Top Market Movers: Among top gainers, IDP Education Limited (ASX:IEL) rose 5.87% to AUD 6.31, followed by Nine Entertainment Co. Holdings Limited (ASX:NEC), which added 5.05% to AUD 1.145. Flight Centre Travel Group Limited (ASX:FLT) climbed 3.71% to AUD 16.20. On the downside, Ora Banda Mining Ltd (ASX:OBM) fell 11.73% to AUD 1.28, Genesis Minerals Limited (ASX:GMD) declined 9.86% to AUD 7.59, and Silex Systems Limited (ASX:SLX) dropped 9.70% to AUD 6.98.
Commodity Update: The U.S. dollar was set for a second consecutive weekly decline on Friday, as new tariff threats against countries trading with Cuba heightened global uncertainty and weighed on demand for U.S. assets. Commodities weakened, with gold down 1.60% to USD 5,269.00, silver lower by 2.36% to USD 111.65, and copper sliding 2.84% to USD 13,370.00. Meanwhile, Brent crude eased 0.20% to USD 70.50, despite rising Middle East tensions linked to a potential U.S. strike on Iran, a key OPEC producer.
Our Stance: Australian equities ended the week slightly softer, with the ASX 200 retreating amid sharp selling in gold miners, despite most sectors finishing higher. Health care led gains, reflecting resilience in domestic demand and sector-specific strength. Macro data showed firm underlying price momentum, with final demand rising both quarterly and annually, driven by services and construction. Stock-specific moves dominated trading, as education, media, and travel names outperformed while mining lagged. Global factors, including weaker commodities and a softer U.S. dollar, added caution. Overall, markets appear poised for consolidation near recent highs, with selective sector strength offering opportunities amid heightened sensitivity to commodity and policy developments.
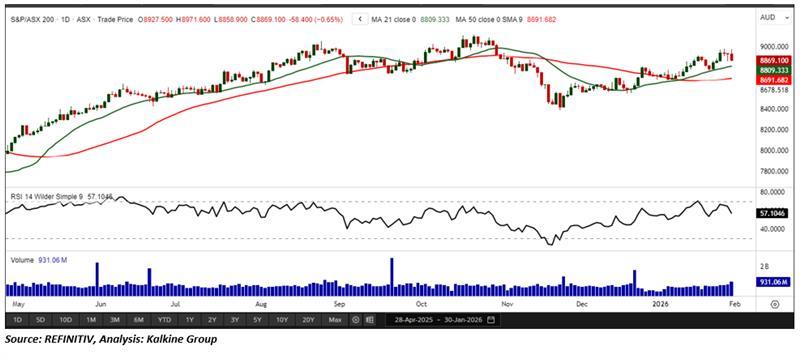
In its latest session, the S&P/ASX 200 Index declined 58.40 points, forming a small bearish candlestick on rising trading volume, which signals increased investor caution and reinforces the prevailing short-term bearish bias. On the daily chart, the index remains above its 21-period Simple Moving Average (SMA), which continues to serve as a key near-term support zone. Immediate support is located near 8,810, and maintaining this level will be critical to stabilizing recent price action and restoring near-term confidence. From a broader perspective, the index continues to trade above its 50-period SMA on the weekly chart, a constructive longer-term signal. This suggests that once short-term selling pressure eases, the S&P/ASX 200 could regain momentum and potentially resume its upward trajectory.


 Nov 12, 2026





 Please wait processing your request...