
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
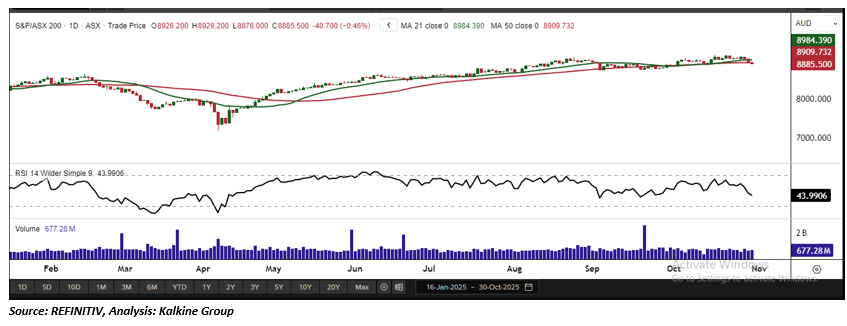
Index Update: The S&P/ASX 200 finished lower on Thursday, slipping 40.70 points or 0.46% to close at 8,885.50, marking a move below its 50-day moving average. The benchmark has declined 1.63% over the past five sessions and now sits 2.52% below its 52-week high. Market performance was mixed, with seven of eleven sectors ending in the red. Health Care led the gains, rising 1.87% as it rebounded from recent losses, though the sector remains down 9.56% over the week. Market sentiment was buoyed across the lithium space after JPMorgan raised its long-term lithium price forecasts, driving sharp gains in Pilbara Minerals and Mineral Resources—Australia’s notable pure-play lithium producers.
Macro Update: The U.S. Federal Reserve has cut interest rates by 25 basis points on Wednesday, lowering its benchmark range to 3.75%–4.00% in a closely watched 10–2 decision. The move, aimed at supporting a slowing job market and stabilising liquidity, also included a plan to restart limited Treasury purchases. Fed Chair Jerome Powell noted that while the rate cut was appropriate, another reduction in December is not guaranteed, emphasising a data-dependent approach going forward.
Top Market Movers: Among the top gainers on Thursday, Mineral Resources Limited (ASX: MIN) surged 13.73% to close at AUD 48.20, followed by Liontown Resources Limited (ASX: LTR), which advanced 11.17% to AUD 1.15. Champion Iron Limited (ASX: CIA) also climbed 9.90% to AUD 5.44. On the downside, Wesfarmers Limited (ASX: WES) fell 7.05% to AUD 86.13, Data#3 Limited (ASX: DTL) declined 6.93% to AUD 8.87, and Block, Inc. (ASX: XYZ) slipped 4.96% to AUD 115.27.
Commodity Update: The U.S. dollar weakened on Thursday after the Fed cut interest rates but said another reduction in December was less likely. The greenback’s earlier strength faded during Asian trading. Gold slipped 1.35% to USD 3,946.70 per ounce, silver fell 1.34% to USD 47.26, and copper declined 0.85% to USD 11,065.00. Brent crude eased 0.05% to USD 64.89 as markets awaited U.S.-China trade talks for clarity on growth prospects.
Our Stance: Australian equities ended weaker as global rate shifts and commodity price swings weighed on sentiment. The benchmark has now fallen 1.63% over five sessions and sits 2.52% below its yearly peak. Despite a strong rebound in lithium and Health Care stocks, overall performance remained uneven, with seven of eleven sectors closing lower. The cautious tone followed the U.S. Fed’s modest rate cut and data-dependent guidance. As of now, market direction may hinge on macro clarity and sustained strength in select resource names.
In its latest session, the S&P/ASX 200 Index declined 40.70 points, forming a bearish candlestick pattern accompanied by rising trading volume a combination that reflects short-term caution among investors and reinforces a prevailing bearish bias. Despite this pullback, the index continues to trade above its 50-period Simple Moving Average (SMA), which acts as immediate support and a key reference point for near-term trend direction. On the daily chart, a key support level is observed near 8,820, and maintaining closes above this zone could help consolidate recent gains and restore confidence in the broader uptrend. Meanwhile, on the weekly timeframe, the index remains positioned above its 21-period SMA, a constructive longer-term signal that suggests the potential for sustained upward momentum once short-term selling pressure subsides.


 Nov 12, 2026





 Please wait processing your request...