
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
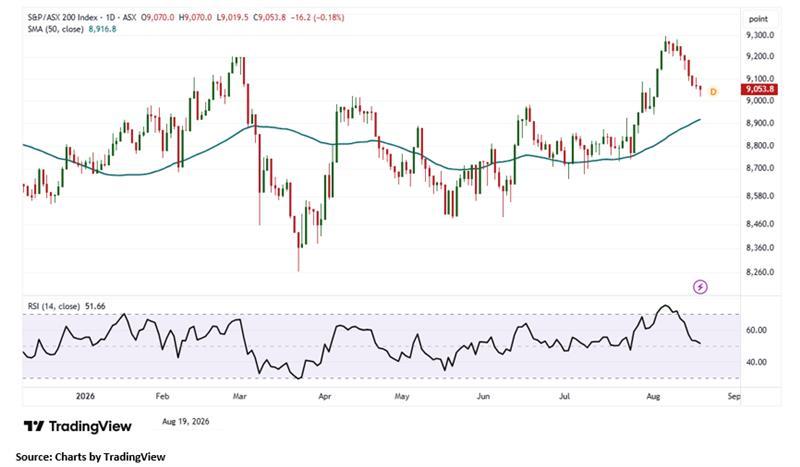
Index Update: The Australian share market extended its decline on Wednesday, with the S&P/ASX 200 falling 16.20 points, or 0.18%, to close at 9,053.80. The benchmark slipped below its 20-day Moving Average and has now fallen 1.69% over the past five sessions, leaving it 2.61% below its 52-week high.
Selling pressure was concentrated in several heavyweight sectors. Information Technology led the declines, dropping 3.15%, while A-REITs fell 1.15%, Financials slipped 0.64%, and Consumer Discretionary declined 0.58%. Despite the softer headline index, Market Breadth was more constructive, with six of the 11 sectors finishing higher. Health Care led the gains with a 2.60% rise, extending its five-day advance to 9.12%. Energy added 0.77%, Utilities gained 0.35%, and Consumer Staples rose 0.31%.
Macro Update: Australia’s Wage Price index rose 0.8% in the June quarter 2026 and 3.2% over the year, according to the Australian Bureau of Statistics. Annual wage growth eased from 3.4% a year earlier but remained above pre-pandemic levels. Public sector wages increased 0.9% quarterly and 3.4% annually, continuing to outpace private sector growth, which reached 0.7% and 3.1%, respectively. Total wages and salaries paid by employers rose 5.7% annually to AUD 109.23 billion in June, covering 15.5 million employee jobs.
Top Market Movers: Stockland (ASX:SGP) led the gainers today, rising 12.35% to AUD 4.55, followed by Fletcher Building Limited (ASX:FBU), which gained 8.77% to AUD 3.35. Superloop Limited (ASX:SLC) advanced 6.73% to AUD 3.33. On the downside, WiseTech Global Limited (ASX:WTC) fell 8.70% to AUD 39.58, while IperionX Limited (ASX:IPX) dropped 7.93% to AUD 3.02. Life360 Inc. (ASX:360) declined 6.89% to AUD 20.94, rounding out the three largest losses for Wednesday’s trading session.
Commodity Update: The U.S. dollar remained near multi-month lows as Treasury yields eased, with investors awaiting the Federal Reserve meeting minutes for interest-rate signals. Gold declined 0.30% to USD 4,407.80, while silver fell 1.41% to USD 63.13. Copper slipped 0.13% to USD 13,975.70. Brent Crude oil advanced 0.73% to USD 91.67 as the prolonged U.S.-Iran standoff around the Strait of Hormuz continued to raise concerns over global Supply conditions and tighter crude availability in the coming months.
Our Stance: The Australian market remains influenced by sector rotation, with recent weakness concentrated in technology and rate-sensitive areas despite broader market participation improving across several sectors. Wage growth continues to moderate while remaining above pre-pandemic levels, suggesting ongoing pressure on costs but a gradual easing in inflationary conditions. Commodity markets remain supported by supply concerns, particularly in crude oil, while precious metals continue to reflect shifting expectations around global monetary policy. Investors may continue to monitor interest-rate signals, Earnings trends and sector-specific catalysts amid a cautious near-term market environment.
On the technical front, the S&P/ASX 200 Index declined by 16.20 points in the latest trading session. Despite the pullback, the broader technical structure remains constructive, with the index holding above the key support level near 9,030, which remains crucial for maintaining the prevailing bullish outlook. A sustained hold above this level could attract renewed buying interest and support a recovery towards recent highs. Conversely, a decisive break below 9,000 would weaken the near-term technical setup and increase downside risk. On the upside, a breakout above the recent swing high near 9,100 could reinforce bullish momentum and potentially open the door for further gains towards the 9,160 level.


 Nov 12, 2026





 Please wait processing your request...