
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
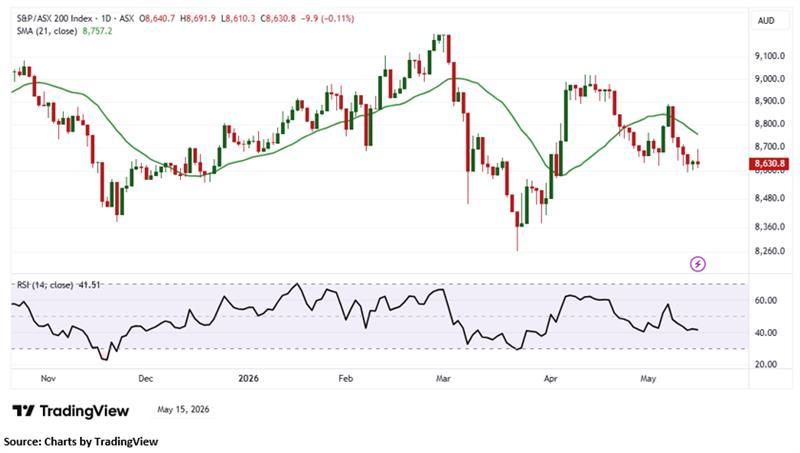
index Update: Australian shares extended their losing streak to a fourth session on Friday, with the S&P/ASX 200 edging lower by 9.90 points or 0.11% to close at 8,630.80. The benchmark has now fallen 1.30% over the past five trading days, although it remains virtually unchanged year to date. Despite the modest decline, Market Breadth was relatively strong, with 9 of the 11 sectors finishing higher. Information Technology led gains, jumping 3.20% as it rebounded from recent weakness, though it is still down 2.30% over the past week. In contrast, materials was the worst-performing sector, slipping 2.85% amid continued profit-taking pressures, which weighed on the broader index.
After an early burst of optimism in morning trade, sentiment cooled through the session, leaving the market to close weaker despite a more upbeat lead from Wall Street overnight, where the Dow Jones rose 0.75% to 50,063.46 and the Nasdaq Composite gained 0.88% to 26,635.22.
Macro Update: US President Donald Trump departed Beijing on Friday after concluding a two-day state visit to China, where he held high-level talks with Chinese President Xi Jinping. The meetings between the leaders of the world’s two largest economies covered a broad range, but no specific agreements or deals were announced at the conclusion of the visit.
Top Market Movers: Among the top gainers, 4DMedical Limited (ASX:4DX) climbed AUD 0.340 or 8.877% to close at AUD 4.170, while Xero Limited (ASX:XRO) advanced AUD 5.990 or 8.129% to AUD 79.670. EVT Limited (ASX:EVT) rose AUD 0.650 or 5.731% to finish at AUD 11.990. On the losing side, IperionX Limited (ASX:IPX) fell AUD 0.520 or 9.075% to AUD 5.210, Mineral Resources Limited (ASX:MIN) dropped AUD 5.390 or 7.683% to AUD 64.770, and Predictive Discovery Limited (ASX:PDI) declined AUD 0.075 or 7.463% to AUD 0.930.
Commodity Update: The U.S. dollar strengthened on Friday after stronger-than-expected U.S. Inflation and retail sales data increased expectations that the Federal Reserve could keep interest rates elevated for longer. Investor focus also remained on President Donald Trump’s China visit, where discussions around trade, artificial intelligence, and geopolitical tensions involving Iran stayed in focus. Gold declined 1.26% to USD 4,625.90, silver dropped 3.89% to USD 82.01, and copper fell 1.40% to USD 13,783.50. Brent Crude rose 0.57% to USD 106.32 amid ongoing concerns over Strait of Hormuz shipping disruptions.
Our Stance: Australian equities closed marginally lower on Friday, marking a fourth consecutive session of declines as weakness in the materials sector offset gains in technology stocks. Although most sectors ended higher, cautious investor sentiment persisted amid profit-taking and mixed global cues. Attention also remained on developments from the US-China meetings, where no major agreements were announced, limiting broader market optimism. Stronger US inflation and retail sales data further supported expectations of prolonged higher interest rates, strengthening the US dollar and pressuring commodity prices. Meanwhile, gains in Brent crude reflected ongoing geopolitical concerns surrounding Middle East shipping disruptions and global energy Supply risks.
The S&P/ASX 200 gained 9.90 points in the latest session, but formed a negative candlestick pattern, indicating some hesitation among buyers near current levels. From a technical standpoint, the index remains below its 21-day Simple Moving Average (SMA), which continues to act as dynamic resistance and limit near-term upside momentum. Immediate support is located near 8,570.60. Holding above this level could help stabilize the market and preserve the broader short-term uptrend, while a decisive break below it would weaken the technical structure and increase the risk of a deeper corrective phase accompanied by elevated Volatility.


 Nov 12, 2026





 Please wait processing your request...