
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
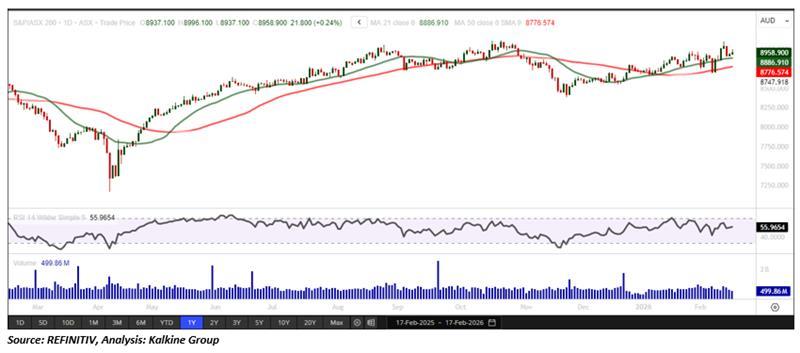
Index Update: The S&P/ASX 200 closed higher on Tuesday, rising 21.80 points or 0.24% to 8,958.90, finishing comfortably in positive territory despite an afternoon dip. The benchmark has now advanced 1.03% over the past five sessions and sits 1.71% below its 52-week high. Market breadth was weaker, with more sectors declining than advancing, although strong gains in Materials, up 1.28% on the day and 1.41% over five days, helped lift the index. Consumer Discretionary (+0.54%) and Consumer Staples (+0.30%) also edged higher, while Health Care (+0.07%) posted a modest rise. Losses were led by A-REITs (-1.05%), with Energy (-0.41%), Information Technology (-0.36%), Industrials (-0.36%), and Telecommunications Services (-0.27%) also in the red, alongside a slight fall in Utilities (-0.11%).
Macro Update: A study by the Federal Reserve Bank of New York shows most of the 2025 Trump tariffs were paid by Americans rather than foreign exporters. About 94% of import taxes initially fell on U.S. firms and households, easing to 86% by November. The Tax Foundation estimates the measures raised household costs by roughly $1,000 in 2025, with another $1,300 expected in 2026. Researchers say exporters cut prices only marginally, leaving businesses and consumers to absorb the bulk of the tariffs’ economic impact.
Top Market Movers: JB Hi-Fi (ASX:JBH) led the market’s advancers on Tuesday, climbing 8.131% to AUD 89.100, followed by Pro Medicus (ASX:PME), which surged 7.685% to AUD 125.960, and The a2 Milk Company (ASX:A2M), up 6.263% to AUD 9.670. On the downside, Reliance Worldwide Corporation (ASX:RWC) dropped 9.091% to AUD 3.500, Lynas Rare Earths (ASX:LYC) fell 5.525% to AUD 15.050, and Treasury Wine Estates (ASX:TWE) declined 4.628% to AUD 4.740.
Commodity Update: The U.S. dollar held firm on Tuesday as investors looked ahead to signals later this week on the potential timing of Federal Reserve rate cuts. Precious metals retreated, with gold falling 0.74% to USD 4,978.90 and silver down 1.51% to USD 75.40, while copper eased 0.58% to USD 12,781.75. Geopolitical focus remained on Iran’s naval drills near the Strait of Hormuz ahead of nuclear talks with the U.S. in Geneva.
Our Stance: The S&P/ASX 200’s 0.24% rise to 8,958.90 masks fragile breadth, with gains concentrated in Materials while rate-sensitive A-REITs and cyclicals lag, suggesting the rally lacks full conviction despite the index nearing its 52-week high. Standout moves in JB Hi-Fi, Pro Medicus and a2 Milk highlight stock-specific momentum, contrasting with sharp falls in Reliance Worldwide, Lynas and Treasury Wine Estates. A firm U.S. dollar and weaker precious metals signal cautious global liquidity conditions, while tariff evidence showing higher costs for U.S. consumers reinforces persistent inflation risks.
The S&P/ASX 200 Index advanced 21.80 points to close at 8,958.90, forming a small bullish candlestick on elevated volume—signalling solid investor confidence and healthy market participation. On the daily chart, the index remains comfortably above its 21-period SMA, which continues to act as key dynamic support and reinforce the short-term uptrend. Immediate support is located near 8,880.30; holding above this level would preserve the bullish structure and allow for consolidation or further upside, while a decisive break could introduce short-term volatility. On the weekly chart, the index remains well above its 21-period SMA, underscoring a robust medium- to long-term trend and a broadly positive market bias despite near-term fluctuations.


 Nov 12, 2026





 Please wait processing your request...