
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 extended its recent softness on Tuesday, slipping 16.60 points or 0.19% to close at 8,680.50, marking a fresh 20-day low. The benchmark has struggled to build upward momentum in recent sessions, as a hawkish Reserve Bank of Australia stance has kept financial conditions tight. Over the past five sessions, the index has edged 0.35% lower, while remaining broadly flat on a year-to-date basis. Market breadth, however, painted a more mixed picture, with seven of the eleven sectors finishing higher. Energy led the gains, rising 0.89% on the day and advancing 1.43% over the five-day period, partially offsetting broader index weakness.
Macro Update: The Reserve Bank of Australia raised its cash rate by 25 basis points to 4.35%, citing persistent inflation pressures and rising global risks. Inflation strengthened in late 2025, with capacity constraints and higher fuel prices—linked to Middle East tensions—adding to price pressures and lifting inflation expectations. Updated forecasts suggest inflation will peak higher before easing as demand slows under tighter policy. While financial conditions have firmed, credit remains available. The Board flagged heightened uncertainty, noting risks of prolonged inflation if energy prices stay elevated, and affirmed a data-driven approach to future decisions.
Top Market Movers: Among the top gainers, Capricorn Metals Ltd (ASX:CMM) rose to AUD 13.010, up AUD 1.110 or 9.327%, Ventia Services Group Limited (ASX:VNT) advanced to AUD 5.890, gaining AUD 0.320 or 5.745%, and WiseTech Global Limited (ASX:WTC) climbed to AUD 45.750, up AUD 2.270 or 5.220%. On the downside, Codan Limited (ASX:CDA) fell to AUD 39.800, down AUD 4.120 or 9.381%, IDP Education Limited (ASX:IEL) declined to AUD 2.900, losing AUD 0.220 or 7.052%, while Magellan Financial Group Limited (ASX:MFG) dropped to AUD 9.630, down AUD 0.710 or 6.867%.
Commodity Update: On Tuesday, the U.S. dollar strengthened as safe-haven demand increased amid renewed Middle East tensions, including attacks on vessels in the Strait of Hormuz and a strike on a key energy facility in the UAE. Gold rose 0.36% to USD 4,549.60, silver edged up 0.01% to USD 73.53, while copper declined 0.56% to USD 12,896.60. Brent crude fell 0.50% to USD 113.85 as Iran-related conflict resolution stalled and maritime blockades disrupted oil flows.
Our Stance: The S&P/ASX 200 extended its decline, closing at a 20-day low as policy signals from the Reserve Bank of Australia weighed on sentiment. While index-level weakness persisted, underlying breadth showed resilience with most sectors advancing, led by Energy, reflecting ongoing commodity and geopolitical influences. The RBA’s rate hike to 4.35% reinforces a restrictive policy backdrop as inflation risks remain elevated, particularly amid Middle East tensions driving fuel costs. Commodity markets reflected this uncertainty, with gold firming and oil volatility persisting. Our stance: the market remains range-bound in the near term, with macro headwinds offset by sectoral support; sustained upside may depend on clearer inflation moderation and easing policy expectations.
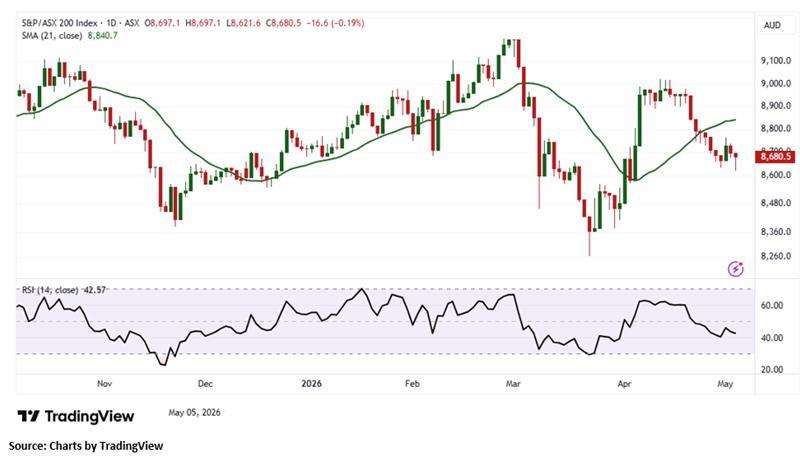
S&P/ASX 200 declined by 16.60 points in the latest session, forming a small bearish candlestick that reflects softening sentiment and a gradual build-up in selling pressure. From a technical standpoint, the index continues to trade below its 21-period Simple Moving Average (SMA), which is acting as a key dynamic resistance and reinforcing the near-term bearish bias. While the index is attempting to stabilise around current levels, immediate support is seen near 8,610.50. Holding above this level may help limit downside risks in the short term. However, a decisive break below this zone could weaken sentiment further, potentially triggering an extended corrective phase and increasing near-term market volatility.


 Nov 12, 2026





 Please wait processing your request...