
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity

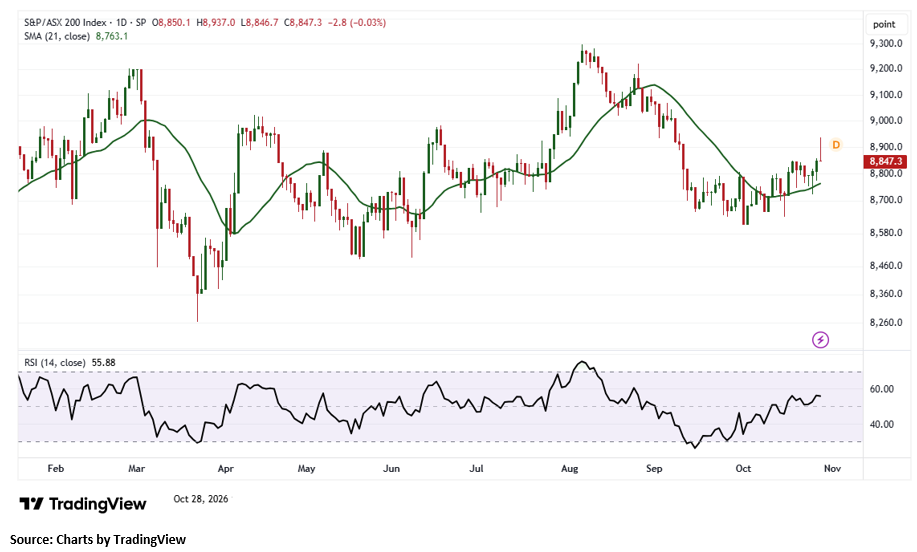
Index Update: The S&P/ASX 200 slipped 2.80 points on Wednesday to close at 8,847.30, reversing earlier gains as higher-than-expected quarterly Inflation data heightened expectations of a Reserve Bank of Australia Interest Rate hike next week. The index remained virtually unchanged over five sessions and stood 4.83% below its 52-week high. Eight of 11 sectors finished lower, with Energy declining 2.45% and Consumer Discretionary losing 1.53%. Information Technology led gains, advancing 2.36%, followed by Materials at 1.07%, highlighting mixed market sentiment.
Macro Update: Australia’s annual inflation accelerated to 4.3% in September 2026, compared with 4.0% in August, reflecting persistent price pressures across the economy. Housing costs increased 5.2%, driven by higher new dwelling and electricity prices, while transport inflation reached 8.7% amid rising automotive fuel costs. Fuel prices climbed 9.4% during September. Quarterly headline inflation stood at 1.3%, while the quarterly trimmed mean rose 1.0%. Annual underlying inflation reached 3.6%, highlighting continued inflationary pressures across Australian households.
Top Market Movers: NEXTDC Limited (ASX:NXT) led gainers, rising 9.391% or AUD 0.540 to AUD 6.290, followed by Perseus Mining Limited (ASX:PRU), which advanced 8.671% or AUD 0.470 to AUD 5.890. IperionX Limited (ASX:IPX) gained 8.247% to AUD 2.100. Among decliners, Reece Limited (ASX:REH) fell 8.815% or AUD 1.510 to AUD 15.620, while 4DMedical Limited (ASX:4DX) declined 4.987% to AUD 3.430. Lendlease Group (ASX:LLC) dropped 4.584% or AUD 0.110 to AUD 2.290, completing the three largest declines.
Commodity Update: The US dollar held near a two-week high on Wednesday as markets awaited policy decisions from major central banks, particularly the Federal Reserve’s guidance on future interest rates. Gold fell 0.32% to USD 4,060.70, while silver declined 0.62% to USD 55.17. Copper slipped 0.27% to USD 14,474.80. Brent Crude oil rose 1.50% to USD 115.60 after renewed Houthi attacks on Saudi Arabia heightened regional tensions and threatened diplomatic efforts to ease the Middle East conflict.
Our Stance: The S&P/ASX 200 edged lower to 8,847.30 as persistent inflation pressures clouded market sentiment and strengthened expectations of an RBA rate hike. Annual inflation reaching 4.3% reinforced concerns over tighter monetary conditions, despite gains in technology and materials stocks. NEXTDC and Perseus Mining delivered strong advances, while Reece and 4DMedical faced selling pressure. Meanwhile, gold, silver, and copper declined as the US dollar remained firm, while Brent crude gained amid Middle East tensions. With inflation risks elevated and Central Bank decisions approaching, market Volatility could persist, suggesting a cautious near-term outlook despite selective strength across Australian equities.
From a technical perspective, the S&P/ASX 200 Index recorded a marginal decline in the latest trading session, while maintaining a cautiously constructive near-term outlook. The index continues to hold above key support at 8,800, which remains critical to preserving the broader bullish structure. Sustained trading above this level could help stabilise market sentiment and support a recovery towards recent highs. On the upside, immediate resistance is positioned near 8,870, and a decisive breakout above this level could strengthen bullish momentum and open the way towards the next target of 8,920. Conversely, a sustained break below 8,800 could weaken the technical outlook and expose the index to further downside pressure.


 Nov 12, 2026





 Please wait processing your request...