
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Source: Krish Capital Pty Ltd
Index Update: The S&P/ASX 200 ended Monday’s session down 11.90 points, or 0.13%, at 8,853.00, leaving the benchmark 2.23% below its 52-week peak and nearly flat over the past five trading days. Market breadth was relatively strong, with seven of the 11 sectors finishing in positive territory despite the index decline. Energy led gains, climbing +0.64% as oil prices steadied, snapping a five-day losing streak that left the sector down -3.84% for the week. While lithium stocks rebounded today, gold stocks witnessed profit booking. Financials (-0.20%) and Materials (-0.54%) dragged the benchmark index lower, while Health Care was the weakest performer, dropping -0.84% amid selling pressure in key large-cap names.
Macro Update: The US economy is sending worrying signals as talk of stagflation, a mix of slowing growth and rising prices, re-emerges. Consumer prices climbed 0.4% in August, pushing annual inflation to 2.9%, the highest level since January and up from 2.7% in July. At the same time, first-time unemployment claims rose sharply to 263,000, the highest in four years, signalling weakening labour market momentum. Normally, slower growth eases price pressures, but this time inflation continues to rise, creating a troubling scenario for policymakers and investors concerned about a prolonged period of economic stagnation paired with persistent price increases.
Top Market Movers: Pilbara Minerals Limited (ASX: PLS) led the session on Monday, jumping 9.09% to AUD 2.160, followed by Boss Energy Ltd (ASX: BOE) up 7.89% at AUD 1.845. IDP Education Limited (ASX: IEL) also gained 7.01% to AUD 5.650. On the losing side, Evolution Mining Limited (ASX: EVN) fell 5.25% to AUD 9.380, Washington H. Soul Pattinson & Co. (ASX: SOL) dropped 5.15% to AUD 40.320, and Brickworks Limited (ASX: BKW) declined 4.90% to AUD 33.020.
Commodity Update: The dollar remained steady on Monday ahead of key central bank decisions, led by the Federal Reserve. The euro showed little reaction to Fitch’s downgrade of France’s credit rating. In commodities, gold slipped 0.21% to USD 3,678.90, silver eased 0.02% to USD 42.82, while copper edged up 0.25% to USD 10,097.25. Brent crude dipped 0.01% to USD 67.02 as markets weighed Ukrainian drone strikes on Russian refineries and U.S. fuel demand growth.
Our Stance: The ASX 200 slipped 0.13% to 8,853.00, remaining 2.23% below its 52-week high despite gains in seven of 11 sectors, led by Energy’s 0.64% rebound. Consumer sectors and Utilities added stability, offset by declines in Health Care and Materials. Globally, stagflation concerns in the US, rising inflation alongside weaker job data, are clouding sentiment. Commodities were mixed, with Brent crude flat and gold easing slightly. The index might stay range-bound in the near-term as market participants weigh growth risks and policy tightening.
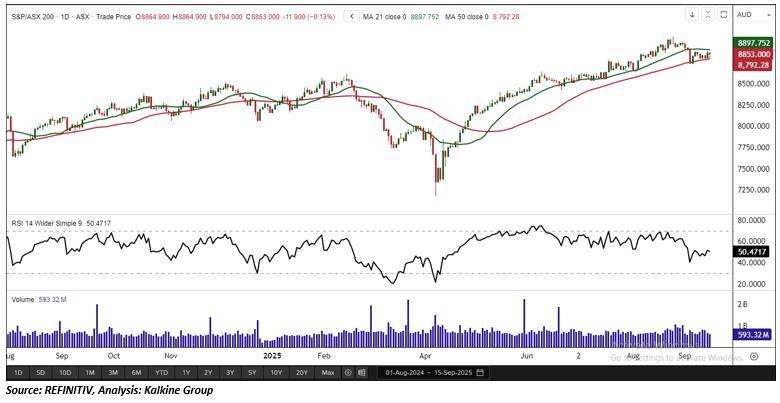
The S&P/ASX 200 Index slipped 11.90 points in the latest session, closing with a bearish candlestick formation that highlights short-term selling pressure. Despite this pullback, the broader technical structure remains constructive, with the market still showing resilience at higher levels. On the daily chart, the index is currently trading below its 21-period Simple Moving Average (SMA), which has emerged as a key resistance level and a near-term hurdle for bullish continuation. A decisive close back above this SMA would strengthen buying conviction and improve the short-term outlook. Immediate support is identified near 8,720.50. Sustaining price action above this zone could allow the index to consolidate recent gains, stabilize sentiment, and maintain investor confidence in the prevailing uptrend. Conversely, a breakdown below this support could invite further selling pressure, potentially exposing the index to deeper retracement levels.


 Nov 12, 2026





 Please wait processing your request...