
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
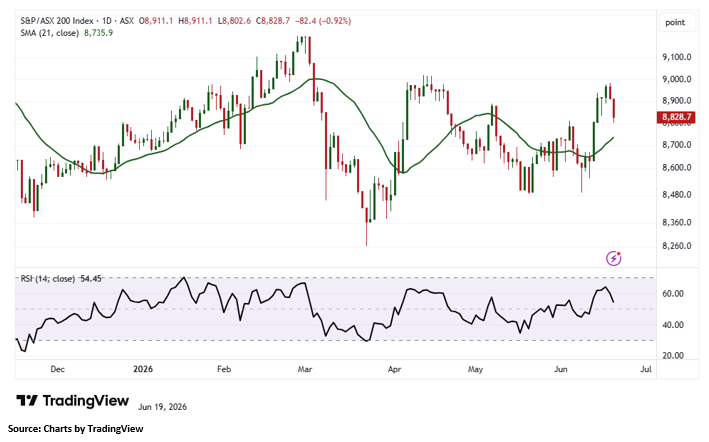
Index Update: Australian equities ended lower on Friday, with losses in mining stocks weighing on the benchmark index. The S&P/ASX 200 fell 82.40 points, or 0.92%, to close at 8,828.70 after reaching a new 20-day high earlier in the session. Over the last five days, the index has gained 0.28% and is currently 4.07% below its 52-week high. Sector performance was mixed, with six of the 11 sectors finishing in negative territory. Materials led the declines, falling nearly 4.03%, while Health Care was the standout performer, rising 3.51% on the day and 4.84% over the past five sessions. Consumer Staples also posted gains of 1.27%, while Energy advanced 0.49%.
Macro Update: Markets continued to monitor developments in the Middle East after the United States and Iran signed a peace agreement aimed at ending hostilities and reopening the Strait of Hormuz. In the United States, stocks rallied overnight, with the Nasdaq gaining 1.9%, driven by strength in semiconductor shares and easing inflation concerns. However, uncertainty surrounding the geopolitical outlook remained after Switzerland said planned talks between U.S. and Iranian negotiators would not proceed on Friday, following Vice President JD Vance's decision to cancel a proposed trip to Geneva. Meanwhile, the Israeli military said it carried out overnight strikes and continued operations against Hezbollah-linked targets and infrastructure in southern Lebanon, underscoring persistent tensions in the region.
Top Market Movers: Among the top gainers, 4DMedical (ASX: 4DX) surged AUD 0.680, or 17.62%, to AUD 4.540. The a2 Milk Company (ASX: A2M) climbed AUD 0.600, or 9.82%, to AUD 6.710, while CSL (ASX: CSL) advanced AUD 8.240, or 7.62%, to AUD 116.320. On the losing side, Deep Yellow (ASX: DYL) fell AUD 0.170, or 9.88%, to AUD 1.550. Alcoa Corporation (ASX: AAI) declined AUD 6.140, or 6.88%, to AUD 83.140, while Newmont Corporation (ASX: NEM) dropped AUD 10.240, or 6.66%, to AUD 143.470.
Commodity Update: The U.S. dollar index climbed to a one-year high on Friday after the Federal Reserve’s hawkish stance strengthened expectations of additional interest rate increases this year. In the commodities market, gold declined by 1.23% to USD 4,194.20, silver dropped 2.48% to USD 64.66, and copper eased 0.59% to USD 13,621.00. Meanwhile, Brent crude oil fell 1.10% to USD 79.01 amid easing supply concerns following progress in U.S.-Iran peace discussions and the reopening of the Strait of Hormuz.
Our Stance: Australian equities closed lower as weakness in mining and commodity-linked stocks outweighed gains in defensive sectors. The sharp decline in materials reflects pressure from softer precious and base metal prices, while easing concerns around Middle East supply disruptions weighed on resource sentiment. However, strength in healthcare and consumer staples suggests investors continue to favour quality and defensive exposures amid an uncertain macro backdrop. Progress in U.S.-Iran relations has reduced immediate energy market risks, but ongoing geopolitical tensions in the region warrant caution. Near-term market direction is likely to remain influenced by commodity price movements, central bank policy expectations, and geopolitical developments.
The S&P/ASX 200 declined 82.40 points in the latest session, forming a bearish candlestick pattern that reflects some near-term weakness in market sentiment. However, the broader outlook remains constructive, with the index continuing to trade above its 21-day Simple Moving Average (SMA), a key dynamic support level that reinforces the prevailing uptrend. Immediate support is located near 8,750.60, and holding above this level should help preserve the current bullish structure. A sustained defence of support could attract renewed buying interest and support further upside, while a decisive break below 8,750.60 may increase selling pressure and raise the risk of a deeper short-term correction.


 Nov 12, 2026





 Please wait processing your request...