
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
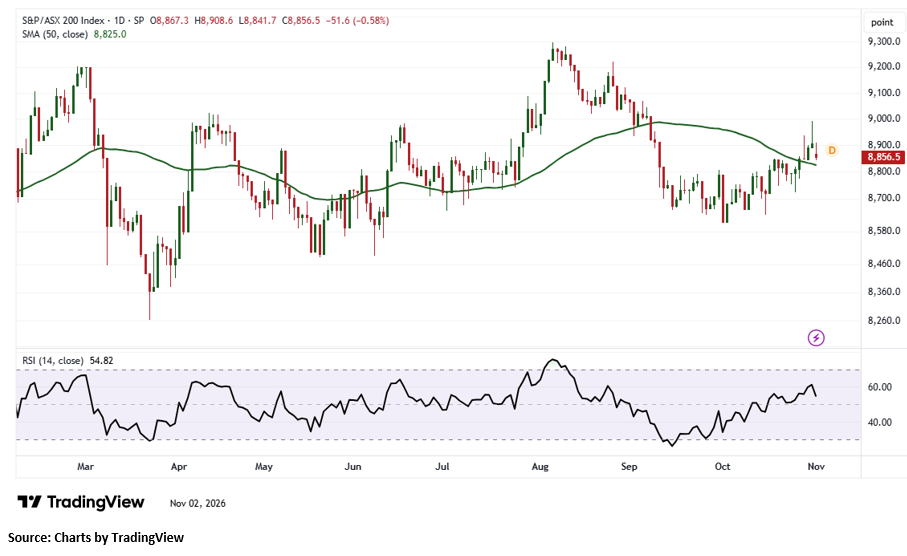
Index Update: The S&P/ASX 200 ended Monday, 2 November 2026, down 51.60 points (0.58%) at 8,856.50, despite reaching a fresh 20-day high. The index remained 0.53% higher over five sessions but stood 4.74% below its 52-week peak.
Eight of 11 sectors declined, with Consumer Staples (-1.39%) and Materials (-1.35%) leading losses. Industrials (+0.76%) topped the gainers, followed by Consumer Discretionary (+0.65%).
Australian shares weakened ahead of the Reserve Bank of Australia's policy decision, amid expectations of a rate increase to an 18-year high. Investors remained cautious over whether recent gains in beaten-down ASX stocks could be sustained.
Macro Update: Australia’s total dwelling approvals increased 5.1% in September 2026 to 17,948 units, according to seasonally adjusted figures released by the Australian Bureau of Statistics on 2 November. Approvals for private dwellings excluding houses surged 16.6%, recovering from a 21.7% decline in August. However, private sector house approvals fell 5.3% to 10,432 dwellings, reversing August’s 5.4% increase. The figures highlighted contrasting trends across residential construction segments during September.
Top Market Movers: Among the top gainers, 4DMedical Limited (ASX:4DX) rose 6.557% or AUD 0.160 to AUD 2.600, followed by Reece Limited (ASX:REH), which gained 5.968% or AUD 1.020 to AUD 18.110. Silex Systems Limited (ASX:SLX) advanced 4.804% to AUD 3.490. On the losing side, Elsight Limited (ASX:ELS) declined 9.393% to AUD 1.640, while Helia Group Limited (ASX:HLI) dropped 7.934% to AUD 4.990. Amp Limited (ASX:AMP) fell 7.481% or AUD 0.190 to AUD 2.350, rounding out the three biggest decliners.
Commodity Update: The US dollar and major currencies remained largely steady as investors awaited the US midterm elections, which could influence congressional control and fiscal policy. Gold gained 0.20% to USD 3,907.00, silver advanced 1.16% to USD 49.86, and copper rose 0.35% to USD 14,198.00. Meanwhile, Brent Crude oil declined 1.80% to USD 111.43 as hopes of diplomatic progress towards ending the US-Israeli conflict with Iran eased concerns over potential Supply disruptions.
Our Stance: The S&P/ASX 200 closed 0.58% lower at 8,856.50 on 2 November 2026, as eight sectors declined ahead of the RBA’s policy decision. Consumer Staples and Materials led losses, while Industrials outperformed. September dwelling approvals rose 5.1%, signalling mixed housing sector momentum as private house approvals weakened. Among individual stocks, 4DMedical (ASX:4DX) gained 6.557%, while Elsight (ASX:ELS) declined 9.393%. Gold, silver and copper advanced, while Brent crude retreated. Despite selective gains and improving dwelling approvals, broader market weakness suggests investors may remain cautious, with the RBA’s Interest Rate decision likely to shape near-term sentiment.
From a technical perspective, the S&P/ASX 200 Index declined in the latest Trading session but continues to hold above key support at 8,810.40, which remains crucial to maintaining the broader bullish structure. Sustained trading above this level could help stabilise market sentiment and support a potential recovery towards recent highs. On the upside, immediate resistance is positioned near 8,890, and a decisive breakout above this level could strengthen buying momentum, potentially driving the index towards the next target of 9,030.50. Conversely, a sustained break below 8,810.40 could weaken the positive technical outlook and expose the index to further downside risks.


 Nov 12, 2026





 Please wait processing your request...