
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
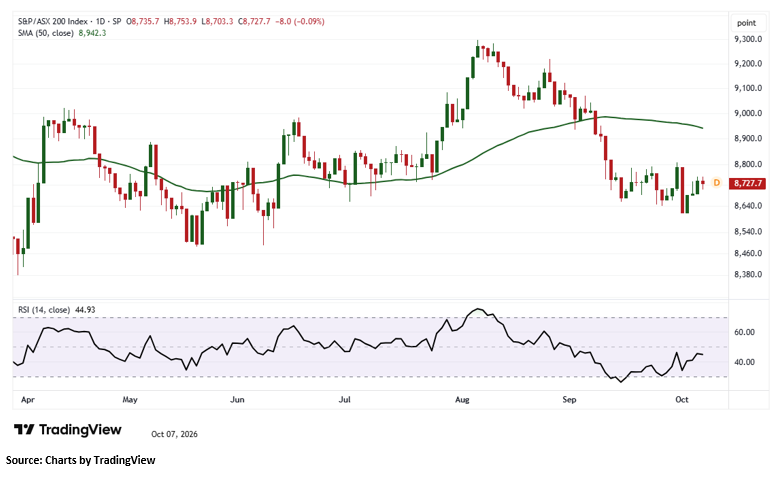
Index Update: The Australian sharemarket edged lower on Wednesday, ending a four-session winning streak despite Wall Street’s record high. The S&P/ASX 200 slipped 8 points to 8,727.70. Six of 11 sectors still finished higher. Health Care led gains, rising 1.09%, followed by A-REITs at 0.80%. Financials fell 0.59%, while Materials and Industrials also declined. The benchmark has lost 0.70% over five sessions and remains broadly flat year to date.
Macro Update: Australian housing construction strengthened in the June quarter, with total dwelling commencements rising 7.0% to 52,201 and completions increasing 5.8% to 47,168. Private house commencements jumped 11.6%. However, August building approvals weakened, falling 6.1% to 16,953 dwellings as approvals for private dwellings excluding houses plunged 21.2%. Private house approvals rose 3.7%, while residential building value slipped 0.6% and non-residential building value dropped 44.8%.
Top Market Movers: ARENA REIT (ASX:ARF) led the top gainers, surging 12.98% or AUD 0.270 to AUD 2.350. Deep Yellow Limited (ASX:DYL) gained 4.61% to AUD 1.135, while Domino’s Pizza Enterprises Limited (ASX:DMP) rose 4.47% to AUD 21.280. Among the top losers, Elsight Limited (ASX:ELS) dropped 5.57% to AUD 4.410. Sims Limited (ASX:SGM) declined 4.78% to AUD 23.120, while Minerals 260 Limited (ASX:MI6) fell 4.68% to AUD 0.815.
Commodity Update: The US dollar remained lower on Wednesday as stress in European bond markets eased, while attention shifted to Federal Reserve minutes and upcoming policymaker speeches for signals on future interest-rate policy. Gold declined 0.40% to USD 4,167.10, silver fell 0.81% to USD 61.06, and copper decreased 0.28% to USD 14,381.40. Brent Crude oil gained 0.92% to USD 101.51 as markets assessed Supply risks from a storm approaching US oil-producing regions and ongoing geopolitical tensions in the Middle East.
Our Stance: The Australian market’s modest decline appears more like a pause after four consecutive gains than a decisive shift in momentum. Broad participation remained relatively constructive, with six sectors advancing and Health Care providing notable support despite weakness in Financials. Housing data presented a mixed backdrop: stronger construction activity contrasted with softer building approvals, pointing to uneven momentum ahead. Sharp moves among individual stocks also highlighted selective opportunities and risks. Meanwhile, weaker precious metals and copper signalled some caution, although firmer oil prices reflected persistent supply concerns. Overall, the session suggests investors remain selective as macroeconomic and policy signals evolve.
On the technical front, the S&P/ASX 200 index declined in the latest trading session, indicating continued near-term selling pressure and maintaining a cautious technical bias. However, the index continues to hold above key support near 8,670, which remains critical for preserving the broader bullish structure. Sustained trading above this level could support a recovery toward recent highs, while a decisive break below 8,670 would weaken the technical setup and increase downside risk. On the upside, a sustained breakout above the recent swing high near 8,760 would strengthen bullish momentum and potentially open the path toward the next resistance level near 8,820.


 Nov 12, 2026





 Please wait processing your request...