
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed lower on Tuesday, shedding 17.10 points or 0.19% to finish at 8,818.80. Despite the dip, eight of eleven sectors advanced, highlighting mixed market sentiment. Utilities led the gains, rising 1.70% and up 3.20% over the past five sessions. Energy and A-REIT sectors followed with gains of 1.33% and 1.17%, respectively. Financials weighed most on the index, falling 1.97%, with Bendigo and Adelaide Bank Limited and Commonwealth Bank of Australia among the weakest performers of the session. Overall, the benchmark remains 3.25% below its 52-week high.
Macro Update: Gold prices surged nearly 3% on Monday, reaching their highest level in more than two weeks, as weaker U.S. economic data fueled expectations of an upcoming Federal Reserve rate cut. Spot gold rose 2.8% to USD 4,111.39 per ounce as of 2:21 p.m. ET (1921 GMT), after touching its strongest level since October 24. U.S. gold futures for December delivery also gained 2.8%, settling at USD 4,122.00 per ounce. Recent data showed that the U.S. economy shed jobs in October, with notable losses in the government and retail sectors. Additionally, consumer sentiment declined sharply in early November, as households expressed concerns about potential economic fallout, further reinforcing the dovish outlook for U.S. monetary policy.
Top Market Movers: Light & Wonder Inc. (ASX:LNW) led the gainers on Tuesday, surging 10.99% to close at AUD 138.82. The rise was followed by Liontown Resources Limited (ASX:LTR), which climbed 7.83% to AUD 1.24 amid renewed optimism in the lithium sector. Pilbara Minerals Limited (ASX:PLS) also advanced, gaining 7.50% to finish at AUD 3.44, extending its recent upward momentum.
On the downside, Bendigo and Adelaide Bank Limited (ASX:BEN) was the biggest decliner, falling 8.49% to AUD 11.64 after a sharp drop in financial sector sentiment. Commonwealth Bank of Australia (ASX:CBA) slipped 6.59% to AUD 163.40, while Life360 Inc. (ASX:360) declined 5.22% to AUD 45.80, rounding out the session’s top three laggards.
Commodity Update: The yen slid to its weakest level since February as hopes grew for a resolution to the U.S. government shutdown, lifting risk currencies. Gold rose 0.55% to USD 4,145, silver gained 0.44% to USD 50.52, while copper was slightly lower at USD 10,818. Brent crude dipped 0.30% to USD 63.89 amid concerns of a potential supply glut, despite support from U.S. political progress and refinery disruptions.
Our Stance: The S&P/ASX 200 ended slightly lower on Tuesday, down 0.19% at 8,818.80, as weakness in major banks outweighed gains across most sectors. Utilities, Energy, and A-REITs led the upward move, while Financials dragged the index lower. Gold’s sharp rally—up nearly 3%—underscored rising global caution as weak U.S. jobs data and softer consumer sentiment fueled rate cut expectations from the Federal Reserve. While the ASX showed resilience in defensive and resource-linked sectors, banking weakness signals continued sensitivity to domestic rate outlook and credit pressures. Overall, market sentiment remains cautious amid global uncertainty and shifting commodity dynamics.
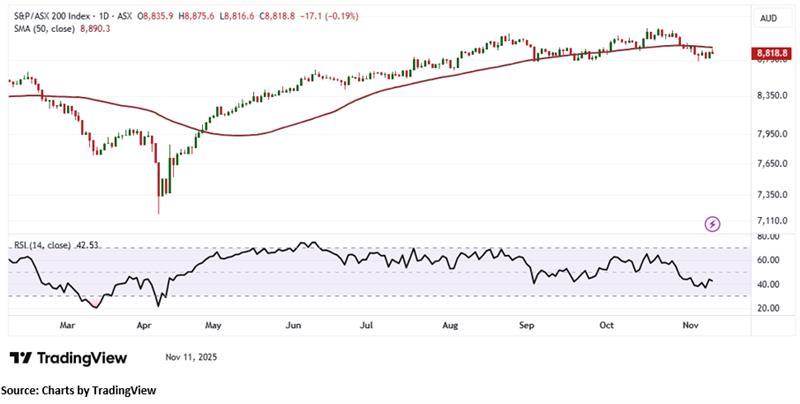
In its latest session, the S&P/ASX 200 Index slipped 17.10 points, forming a small bearish candlestick pattern on rising trading volume a combination that reflects short-term investor caution and reinforces the prevailing bearish sentiment. Despite this minor decline, the index remains below its 50-period Simple Moving Average (SMA), which continues to act as immediate resistance. On the daily chart, a key support level is situated near 8,740, and maintaining closes above this zone could aid in consolidating recent gains and rebuilding market confidence. From a broader weekly perspective, the index continues to trade above its 21-period SMA a constructive long-term indicator that suggests the potential for sustained upward momentum once short-term selling pressure subsides.


 Nov 12, 2026





 Please wait processing your request...