
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
index Update: The S&P/ASX 200 slipped 5.0 points on Tuesday to close at 8,724.40 as investors weighed mixed signals over diplomatic efforts to end the conflict between the US and Iran. The benchmark remains up 0.77% over the past five trading sessions and is largely unchanged for the year.
Sector performance was mixed, with 6 of 11 sectors finishing lower. Information Technology led the gains, surging 4.71% and extending its five-day advance to 12.40%. Materials (+1.25%) and Telecommunications Services (+1.07%) also outperformed.
Meanwhile, retail-related stocks came under pressure after stronger-than-expected wage growth data raised concerns about rising labour costs. A-REITs (-1.52%), Consumer Staples (-1.31%), Health Care (-1.21%) and Financials (-1.00%) were among the weakest sectors, while Consumer Discretionary fell 0.60%.
Macro Update: Australia's latest economic data painted a mixed picture for the March 2026 quarter, with company gross Operating profits falling 1.3% while wages and salaries increased 1.2%. Inventories rose 0.5%, and sales of goods and services increased across ten industries, though five sectors recorded declines. Government finance figures showed the general government net operating balance improved by AUD 1.3 billion to a Deficit of AUD 0.4 billion, despite a 4.5% drop in taxation Revenue to AUD 220.6 billion. Meanwhile, mineral exploration expenditure climbed 6.3%, highlighting ongoing Investment in the resources sector, while petroleum exploration spending fell 4.8%.
Top Market Movers: SRG Global Limited (ASX: SRG) led the market higher, surging 16.56% to AUD 3.66. Northern Star Resources Ltd (ASX: NST) followed with a 13.61% gain to AUD 21.03, while Life360 Inc. (ASX: 360) climbed 13.25% to AUD 23.07. On the downside, TPG Telecom Limited (ASX: TPG) was the session’s biggest loser, falling 7.50% to AUD 3.70. Paladin Energy Ltd (ASX: PDN) declined 5.93% to AUD 10.63, while 4DMedical Limited (ASX: 4DX) dropped 5.87% to AUD 3.85.
Commodity Update: The U.S. dollar remained steady on Tuesday as investors adopted a cautious stance amid ongoing Middle East peace discussions. Lebanon announced a limited ceasefire between Hezbollah and Israel, offering some relief to regional tensions, though broader geopolitical risks continued to weigh on market sentiment. Gold rose 0.26% to USD 4,518.10, silver gained 0.37% to USD 75.62, and copper advanced 0.43% to USD 13,878.90. Meanwhile, Brent Crude slipped 0.40% to USD 94.58 as the Strait of Hormuz remained closed, maintaining uncertainty over global energy Supply routes.
Our Stance: The ASX 200 closed marginally lower as investors balanced easing geopolitical tensions against ongoing uncertainty surrounding Middle East developments. While gains in technology, materials, and telecommunications supported the market, weakness in retail-linked sectors reflected concerns that rising wage growth could pressure operating costs and margins. Domestic economic data highlighted a mixed backdrop, with softer corporate profits offset by higher wages, inventory growth, and continued strength in resource-sector investment. Commodity markets remained resilient, with precious and base metals advancing despite a steady U.S. dollar. Overall, market sentiment remains cautious as investors assess geopolitical risks and the evolving domestic economic outlook.
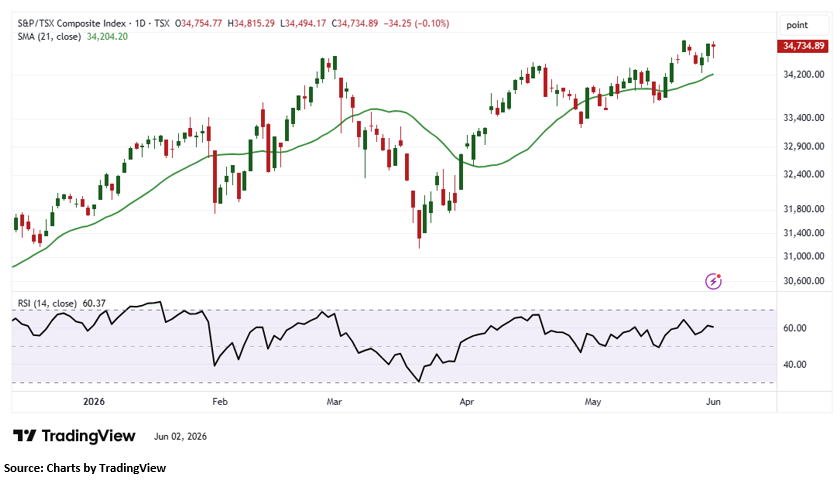
The S&P/TSX Composite Index slipped 32.25 points, or 0.10%, on Monday to close at 34,734.89, pausing after its recent advance. Despite the modest decline, the broader technical outlook remains constructive, with the index continuing to trade above its 21-day Simple Moving Average (SMA), which is acting as a key dynamic support level and reinforcing the prevailing bullish trend. Momentum indicators also remain supportive, with the 14-day Relative Strength Index (RSI) holding near 60.37, signalling healthy underlying buying interest while still leaving room for further gains before overbought conditions are reached. Immediate support is located around the 34,600 level, and a sustained move below this area could trigger a period of short-term consolidation, potentially exposing the 34,300 region as the next downside target. On the upside, resistance is positioned near the 34,900 zone. A decisive breakout above this level would strengthen bullish sentiment and could pave the way for a move towards the 35,100 mark in the near term. Overall, the index remains favourably positioned while it continues to hold above key support levels.


 Nov 12, 2026





 Please wait processing your request...