
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 finished slightly higher on Tuesday, adding 14.50 points or 0.17% to close at 8,579.70. The index has risen 0.50% over the past five sessions and is now up 5.15% year to date. Despite the overall uptick, most sectors ended the day in negative territory. Energy stood out as the best performer, gaining +1.07%, supported by a steady five-day rise of +1.14%. Other pockets of strength included Materials (+0.74%), Consumer Staples (+0.46%), and A-REITs (+0.43%). Meanwhile, Information Technology was the weakest sector, falling –1.55%, alongside modest declines in Consumer Discretionary, Utilities, Industrials, Telecommunications Services, and Financials.
Macro Update: Gold prices climbed to a six-week high on Monday, lifted by expectations of potential U.S. interest rate reductions and a weaker dollar, while silver reached a fresh record ahead of key economic data releases. Spot gold rose 0.3% to USD 4,241.27 per ounce at 1:44 p.m. ET, marking its strongest level since October 21. U.S. gold futures for February delivery closed 0.5% higher at USD 4,274.80.
In Australia, new data from the Australian Bureau of Statistics (ABS) showed a notable pullback in housing approvals. Total dwelling approvals dropped 6.4% in October to 15,832 on a seasonally adjusted basis. The September quarter 2025 also reflected heightened fiscal pressures, with the general government net operating balance falling AUD 34.8bn to –AUD 32.2bn since the June quarter. Taxation revenue slipped 11.6% to AUD 200.0bn, while general government borrowing stood at AUD 42.7bn. The ABS noted that total public demand is expected to contribute 0.4 percentage points to quarterly GDP growth. Australia’s external position also weakened. The nation’s current account balance recorded a AUD 0.5bn deterioration in the September quarter, reaching a AUD 16.6bn deficit on a seasonally adjusted, current-price basis.
Top Market Movers: Yancoal Australia Limited (ASX:YAL) led the gainers, rising to AUD 5.550 after a AUD 0.180 or 3.35% increase. AUB Group Limited (ASX:AUB) advanced to AUD 31.550, up AUD 0.920 or 3.00%. HomeCo Daily Needs REIT (ASX:HDN) gained 2.94% to AUD 1.400. Among the losers, Zip Co Limited (ASX:ZIP) fell 10.61% to AUD 2.950, Catapult Sports Ltd (ASX:CAT) dropped 9.13%, and Guzman y Gomez Limited (ASX:GYG) declined 4.35% to AUD 22.220.
Commodity Update: The U.S. dollar stayed weak on Tuesday after disappointing U.S. manufacturing data increased expectations of a Fed rate cut later this month. Gold edged down 0.44% to USD 4,255.35, silver dropped 2.05% to USD 57.92, and copper slipped 0.88% to USD 11,163. Brent crude rose 0.10% to USD 63.23, supported by OPEC+’s decision to pause production hikes and ongoing geopolitical supply concerns.
Our Stance: The S&P/ASX 200 ended slightly higher on Tuesday, but the modest rise masked underlying softness across most sectors. Energy provided the clearest support, extending a multi-day rebound, while Materials and Consumer Staples offered supplementary stability. However, weakness in Information Technology and several cyclicals signalled lingering caution, likely tied to broader macro signals. Globally, gold’s advance to a six-week high underscored persistent risk-off sentiment, driven by expectations of potential U.S. rate cuts and a softer dollar. Domestically, the latest ABS data painted a mixed picture: falling dwelling approvals, a wider current account deficit, and a deteriorating fiscal position suggest underlying economic pressures, even as public demand is set to contribute modestly to GDP. Market moves reflected this divergence, with gains in defensives like YAL and AUB contrasting sharp declines in ZIP and CAT. Overall, the tone remains cautious, with sentiment moving in response to shifting global policy expectations and weakening local indicators.
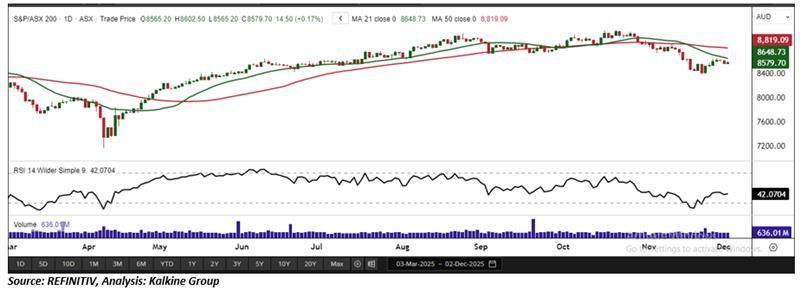
In its latest session, the S&P/ASX 200 Index advanced 14.50 points to close at 8,579.70, supported by a small bullish candlestick formation and strong trading volumes both signaling sustained investor confidence. On the daily chart, the index continues to trade below its 21-period Simple Moving Average (SMA), which remains a key dynamic resistance level. A critical support zone lies near 8,520, and holding above this area is essential to maintaining the current bullish structure. Successfully defending this level would allow the index to consolidate recent gains while strengthening confidence in the broader upward trajectory. From a weekly standpoint, the index trades comfortably above its 50-period SMA, reinforcing a constructive longer-term outlook. Overall, the technical setup points to the potential for continued upside momentum, provided near-term support levels remain intact.


 Nov 12, 2026





 Please wait processing your request...