
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 slipped on Friday, closing 11.50 points, or 0.13%, lower at 8,958.30. Over the past week, the index has fallen 0.32% and remains 1.06% below its 52-week high. Despite the broader decline, eight of the eleven sectors posted gains, with Information Technology leading the charge, climbing 1.11% as it recovered from recent losses. However, the sector is still down 2.34% over the past five days. The broader market pulled back amid risk-off sentiment linked to the Gaza peace plan, with oil and gold stocks falling, and major iron ore miners slipping amid renewed price dispute reports with China.
Macro Update: Australia’s monthly business turnover fell 2.2% in August (seasonally adjusted), marking the largest decline since April 2023, according to the Australian Bureau of Statistics (ABS). The downturn was broad-based, with nine industries recording falls. The most significant drop came from the electricity, gas, water and waste services division, down 14.1% as wholesale energy prices eased after strong gains in July. Manufacturing (-5.8%), information media and telecommunications (-3.7%), and mining (-1.9%) also contributed to the decline. Despite the monthly dip, overall turnover remained 4.5% higher than in August 2024, with 11 of 13 industries reporting annual growth.
In another update, Reserve Bank Governor Michele Bullock stated that unemployment is expected to rise further this year, warning that persistent household spending could reignite inflation. She noted the economy remains generally resilient despite “sticky” services inflation and a still-tight labour market.
Top Market Movers: Temple & Webster Group Ltd (ASX:TPW) led the ASX gainers on Friday, rising 5.70% to close at AUD 25.02, followed by Netwealth Group Ltd (ASX:NWL), up 5.31% to AUD 32.51, and Elders Limited (ASX:ELD), up 3.72% to AUD 7.53. On the downside, Genesis Minerals Ltd (ASX:GMD) fell 5.65% to AUD 5.85, Regis Resources Ltd (ASX:RRL) dropped 5.48% to AUD 5.69, and Ramelius Resources Ltd (ASX:RMS) slipped 5.45% to AUD 3.82, marking the week’s largest decliners.
Commodity Update: The yen hovered near 153.12 per U.S. dollar, set for its steepest weekly drop in a year as fading prospects of another Bank of Japan rate hike weighed on sentiment. Gold rose 0.71% to USD4,000.95, silver gained 0.84% to USD47.56, and copper slipped 0.54% to USD10,822.45. Brent crude was flat at USD65.22, steady after the Israel-Hamas ceasefire eased risk premium, offset by fresh U.S. sanctions on Iran and concerns over weak winter fuel demand.
Our Stance: Market sentiment remains cautious amid mixed signals. The S&P/ASX 200 ended the week slightly lower as investors weighed geopolitical risks and softer domestic data. Recent declines in business turnover and signs of easing energy prices highlight moderating economic momentum. Comments from the Reserve Bank suggest further labour market softening, reinforcing expectations of a cautious policy stance. Despite overall weakness, select growth and technology stocks showed resilience, recovering from earlier losses. Commodity markets remained volatile, with gold supported by safe-haven demand and oil steady amid geopolitical shifts. Overall, market focus remains on inflation persistence and near-term global growth prospects.
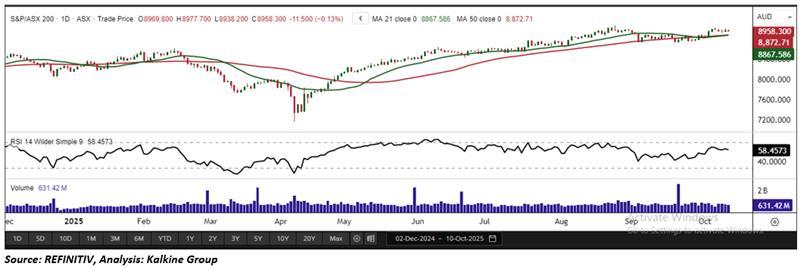
The S&P/ASX 200 Index declined by 11.50 points in its latest session, forming a bearish candlestick pattern accompanied by rising trading volumes. This setup indicates short-term caution among investors and highlights a prevailing bearish bias in the near term. Despite the pullback, the index continues to trade above its 21-period Simple Moving Average (SMA), which now serves as an immediate support zone. On the daily chart, key support is identified near 8,890. Sustaining levels above this threshold could enable the index to consolidate recent gains and reaffirm confidence in the broader uptrend. From a weekly perspective, the index remains positioned above its 21-period SMA, representing a constructive technical structure that supports the potential for sustained bullish momentum over the longer term, provided near-term support levels hold firm.


 Nov 12, 2026





 Please wait processing your request...