
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
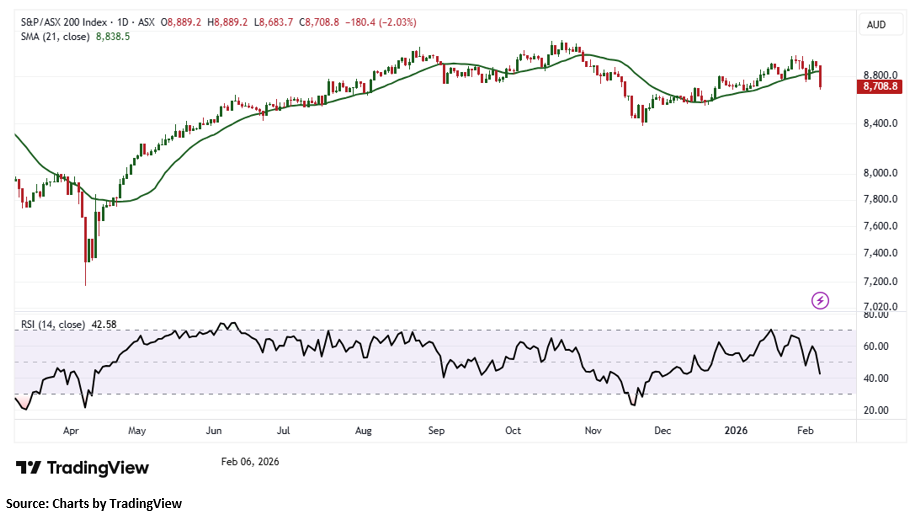
Index Update: The S&P/ASX 200 closed sharply lower on Friday, falling 180.40 points, or 2.03%, to 8,708.80, marking a new 20-day low. The index lost 1.81% over the past week but remains virtually unchanged year-to-date. The drop was driven by sliding commodity prices and concerns about the economic impact of artificial intelligence. All 11 sectors ended in the red, with the Health Care sector down 1.16%, continuing its 2.39% decline over the past five days.
Macro Update: Data released today by the Australian Bureau of Statistics reveals that, for 2024-25, the Australian market sector’s Multifactor Productivity (MFP) fell by 0.5%, while labour productivity decreased by 0.2%, following a 1.0% rise in 2023-24. MFP dropped in nine of the sixteen market sector industries, with the largest decline in Mining and the biggest increase in Agriculture, Forestry, and Fishing.
Meanwhile, in commodities, gold is expected to perform at record levels in 2026, according to a Reuters poll. Analysts have raised their forecasts due to ongoing geopolitical uncertainty and strong central bank buying. The median gold price forecast for 2026 reached USD 4,746.50 per troy ounce, marking the highest estimate since 2012, up from USD 4,275 in October.
Top Market Movers: The top gainers on the ASX included Brambles Limited (ASX:BXB), up 3.48% to AUD 23.51, ResMed Inc (ASX:RMD), which rose 1.23% to AUD 37.92, and Pexa Group Limited (ASX:PXA), gaining 1.10% to AUD 13.74. On the downside, Web Travel Group Limited (ASX:WEB) saw a sharp 29.52% drop to AUD 2.96, followed by Deep Yellow Limited (ASX:DYL), down 12.00% to AUD 2.20, and Paladin Energy Ltd (ASX:PDN), which fell 10.92% to AUD 11.01.
Commodity Update: The U.S. dollar hovered near a two-week high on Friday, on track for its strongest weekly gain since November as equity markets retreated amid concerns over AI-related spending. The Japanese yen firmed ahead of Sunday’s national election. Commodities weakened, with gold down 1.10% to USD 4,836.20, silver sliding 6.72% to USD 71.56, and copper easing 0.79% to USD 12,830.00. Brent crude fell 0.74% to USD 67.05 as Middle East supply fears eased and attention turned to U.S.–Iran nuclear talks in Oman.
Our Stance: The S&P/ASX 200’s sharp decline reflects growing caution amid falling commodity prices and uncertainty surrounding artificial intelligence’s economic impact. Weakness across all sectors, notably Health Care, signals broad-based investor nervousness. Productivity metrics reveal slowing momentum, with multifactor and labor productivity both declining, particularly in Mining. Gold’s strong forecast underscores continued demand driven by geopolitical tension and central bank activity. Currency movements highlight a stronger U.S. dollar and a firming yen, influencing commodity prices. Volatility among individual stocks reinforces a risk-off environment as markets weigh global economic and sector-specific developments.
In its latest session, the S&P/ASX 200 Index declined sharply by 180.40 points, forming a bearish candlestick on rising trading volume, a combination that reflects heightened investor caution and reinforces the prevailing short-term bearish bias. On the daily chart, the index continues to trade below its 21-period Simple Moving Average, which remains an important near-term resistance level and is capping upside attempts. Immediate support is located near the 8,600 mark, and holding above this zone will be critical to stabilising price action and limiting further downside pressure. From a broader perspective, the index remains above its 50-period SMA on the weekly timeframe, preserving a constructive medium- to longer-term outlook. Once near-term selling pressure subsides, the index may regain traction and attempt to re-establish its broader upward trend.


 Nov 12, 2026





 Please wait processing your request...