
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed lower on Friday, slipping 13.80 points or 0.15% to 9,019.00. Over the last five days, the index has gained 0.26% and currently sits 1.06% below its 52-week high. Sector performance was mixed, with six out of eleven sectors finishing in the red alongside the S&P/ASX 200 Index. Information technology stood out as the best-performing sector, rising 1.32% on the day and 1.71% over the week. Materials (+0.41%), A-REIT (+0.35%), Energy (+0.32%), and Industrials (+0.06%) also rose, while Health Care posted the sharpest sector decline at -1.23%. Other sectors underperformed with Consumer Staples (-0.75%), Financials (-0.54%), Consumer Discretionary (-0.17%), and Utilities (-0.11%) all ending in the red.
Macro Update: The Australian economy expanded by 1.4% in chain volume terms during 2024-25, as shown in the official percentage changes for GDP. Over this period, labour productivity declined by 0.7%, while the household saving ratio experienced a notable increase, rising to 6.1% from 3.0% in 2023-24. Additionally, the national net worth grew by AUD 0.8 trillion, reaching a total of AUD 21.4 trillion.
Top Market Movers: On Friday, top gainers included Liontown Resources Limited (ASX:LTR), up 10.41% to close at AUD 1.220, Pilbara Minerals Limited (ASX:PLS), rising 9.12% to AUD 3.230, and IGO Limited (ASX:IGO), climbing 7.98% to AUD 5.820. On the downside, Newmont Corporation (ASX:NEM) fell 4.42% to AUD 127.150, Deep Yellow Limited (ASX:DYL) dropped 4.00% to AUD 1.680, and Magellan Financial Group Limited (ASX:MFG) declined 3.73% to AUD 10.060.
Commodity Update: The U.S. dollar held steady on Friday, set for a modest weekly gain as markets awaited delayed inflation data ahead of next week’s expected Fed rate cut. Gold slipped 0.44% to USD 4,127.50, silver fell 0.96% to USD 48.23, and copper eased 0.29% to USD 10,815.70. Brent crude declined 0.80% to USD 65.45 but remained on track for a weekly rise amid U.S. sanctions on Russian oil majors.
Our Stance: Markets showed mixed signals, with modest gains in technology and resources offset by weakness in healthcare and staples. Economic growth is steady, but rising savings and selective sector performance suggest investors should remain cautious, focusing on quality opportunities and risk management amid ongoing market volatility. Currency fluctuations and commodity price movements add further uncertainty, making careful portfolio diversification and disciplined entry points essential. Close monitoring of sector trends and macroeconomic indicators will help navigate potential risks while identifying sustainable growth opportunities.
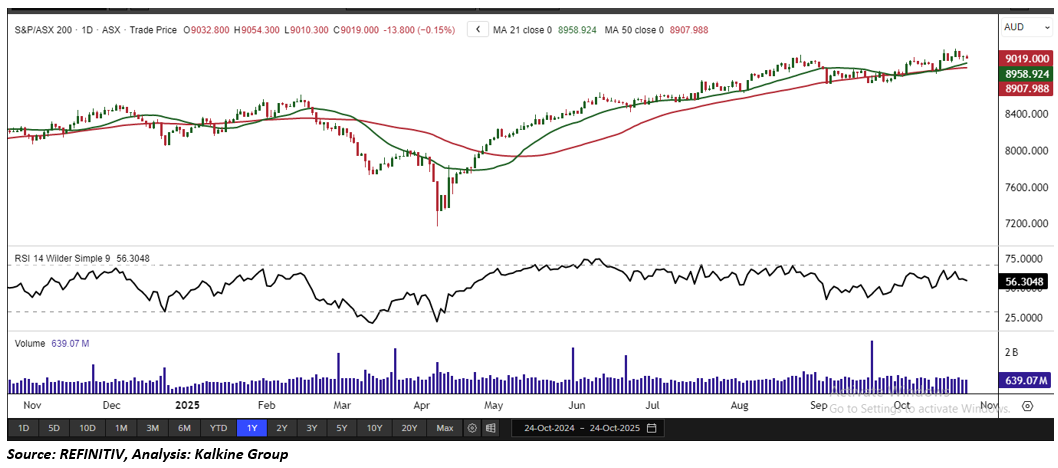
The S&P/ASX 200 Index declined 13.80 points in its latest session, forming a bearish candlestick pattern accompanied by higher trading volume, signaling short-term caution and a prevailing bearish bias among investors. Despite this pullback, the index remains above its 21-period Simple Moving Average (SMA), which now serves as immediate support. On the daily chart, a key support level is identified near 8,940.70; holding above this level could help consolidate recent gains and reinforce confidence in the broader uptrend. On the weekly chart, the index also continues to trade above the 21-period SMA, a constructive signal suggesting the potential for sustained momentum over the longer term.


 Nov 12, 2026





 Please wait processing your request...