
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
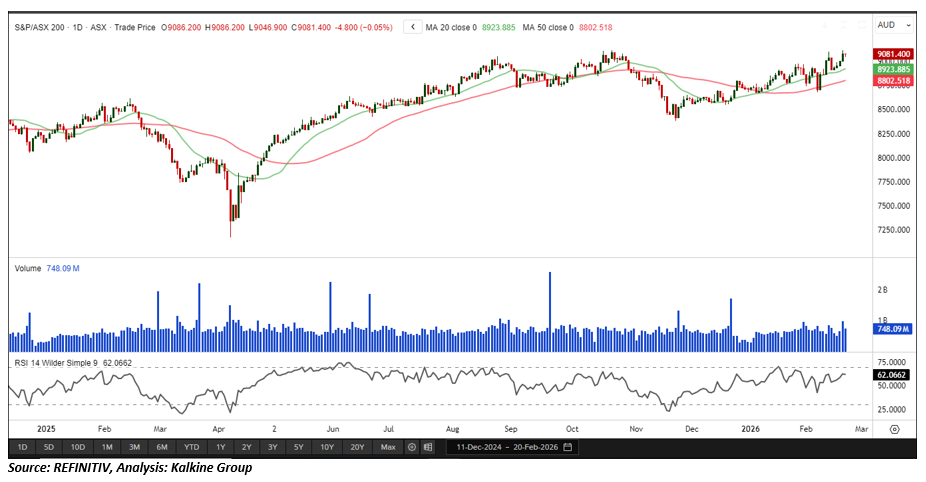
Index Update: The S&P/ASX 200 edged lower on Friday, slipping 4.80 points to close at 9,081.40, with market breadth remaining weak as 107 stocks declined compared to 80 gainers and 11 unchanged. Despite the modest daily fall, the benchmark has risen 1.84% over the past five sessions and now sits just 0.40% below its 52-week high. Sector performance was mixed, with six of the 11 sectors finishing in negative territory. Information Technology led the losses, while Utilities was the standout performer, advancing 0.73% on the day and 1.04% over the past week. Financials, Energy and A-REITs also posted gains, whereas Consumer Staples, Consumer Discretionary, Materials, Telecommunications Services and Health Care closed lower.
Macro Update: U.S. economic growth likely cooled in the fourth quarter, with GDP expected to rise at a still-solid 3.0% annualised pace after 4.4% in the prior quarter. Last year’s 43-day government shutdown and softer consumer spending weighed on activity, according to a Reuters survey. A wider trade deficit also prompted the Atlanta Federal Reserve to trim its estimate. Economists say the expansion remains uneven, with higher-income households faring better amid tariff-driven inflation and weak wage growth. The shutdown may have shaved 1.5 percentage points off GDP, though most losses are expected to be recovered.
Top Market Movers: Telix Pharmaceuticals (ASX:TLX) led the gains on Friday, surging 14.238% to AUD10.430, followed by QBE Insurance (ASX:QBE), which climbed 7.078% to AUD21.480, and Austal (ASX:ASB), up 5.527% to AUD6.300. On the downside, Guzman y Gomez (ASX:GYG) tumbled 13.943% to AUD17.530, Megaport (ASX:MP1) dropped 11.792% to AUD9.650, and Liontown (ASX:LTR) slipped 6.359% to AUD1.620.
Commodity Update: The U.S. dollar headed for its strongest weekly gain since October, supported by upbeat economic data and a firmer Federal Reserve stance, while geopolitical tensions between Washington and Tehran kept investors cautious. Fresh data showed U.S. jobless claims fell more than expected, highlighting labour market resilience. Gold rose 0.33% to USD 5,014.10, silver gained 0.49% to USD 78.01, copper edged up 0.09%, and Brent crude climbed 0.30% to USD 71.87.
Our Stance: The S&P/ASX 200 ended marginally lower at 9,081.40, pressured by weak breadth even as it remained close to its 52-week high after a solid five-day run. Overnight, U.S. growth expectations were trimmed to a still-healthy 3.0% annualised pace amid shutdown disruptions, softer consumption, and a wider trade deficit, signalling an uneven expansion. Commodity markets were firmer, with gold above USD5,000 and oil edging higher as the U.S. dollar posted its strongest weekly advance in months. Our stance: The index’s resilience near record levels suggests underlying strength, but mixed macro signals and narrow participation warrant a cautiously constructive outlook in the near term.
In its latest session, the S&P/ASX 200 declined by 4.80 points, forming a small bearish candlestick on rising trading volume a signal of increased investor caution and short-term weakness. On the daily chart, the index is trading just above its 21-period Simple Moving Average (SMA), which continues to act as an important near-term support level. Immediate support is seen near 8,990.60; holding above this zone will be crucial to stabilise price action and limit further downside pressure. On the weekly timeframe, the index remains above its 50-period SMA, preserving a constructive medium- to longer-term outlook despite near-term softness.


 Nov 12, 2026





 Please wait processing your request...