
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 ended Tuesday’s session higher, rising 49.10 points, or 0.56%, to close at 8,808.50, marking a fresh 20-day high. The benchmark has advanced 1.45% over the past five sessions and is now about 3.36% below its 52-week peak. Sector performance was mixed, with more sectors closing lower despite the overall gain. Materials led the market, climbing 2.02% on the day and posting a 1.90% rise over the past week.
Macro Update: Purchasing Managers’ Index (PMI) surveys from S&P Global signalled a continued expansion in global business activity at the end of 2025, although momentum weakened in December to the slowest pace in six months. The J.P. Morgan Global Composite PMI Output Index slipped to 52.0, indicating global GDP growth of around 2.4% on an annualised basis, below pre-pandemic averages. Business expectations remained subdued amid economic and political uncertainty, dampening spending plans. While the US and India continued to lead growth among major economies, their advantage narrowed as activity slowed.
Top Market Movers: On the ASX, IMDEX Limited (ASX:IMD) led the top gainers, rising to AUD 3.95, up AUD 0.25 or 6.76%, followed by Austal Limited (ASX:ASB), which climbed 6.72% to AUD 8.73. Iluka Resources (ASX:ILU) added 6.20% to close at AUD 6.68. On the downside, GQG Partners (ASX:GQG) fell 8.64% to AUD 1.64, while Zip Co (ASX:ZIP) and Catapult Sports (ASX:CAT) dropped 7.61% and 7.03%, respectively.
Commodity Update: The U.S. dollar stayed under pressure on Tuesday after the Trump administration opened a criminal investigation into Federal Reserve Chair Jerome Powell, raising concerns over central bank independence and confidence in U.S. assets. Gold slipped 0.19% to USD 4,608.30, while silver rose 0.85% to USD 85.78 and copper advanced 0.94% to USD 13,219.20. Brent crude oil remained higher, trading up at USD 63.87, after surging to seven-week highs, supported by concerns that Iran’s oil exports could decline amid heightened geopolitical tensions.
Our Stance: The ASX extended gains with the S&P/ASX 200 closing at a 20-day high, supported mainly by strength in Materials, even as broader sector participation remained uneven. This resilience contrasts with a softer global macro backdrop, where S&P Global PMI data point to slowing momentum and subdued business confidence amid ongoing economic and political uncertainty. Stock-specific moves dominated trading, with sharp gains in IMDEX and Austal offset by pronounced declines in GQG Partners and Zip. Commodities reflected mixed risk sentiment, with precious metals and oil supported by geopolitical factors. Our stance: near-term market direction may remain selective, driven more by sector and stock-level catalysts than broad-based growth optimism.
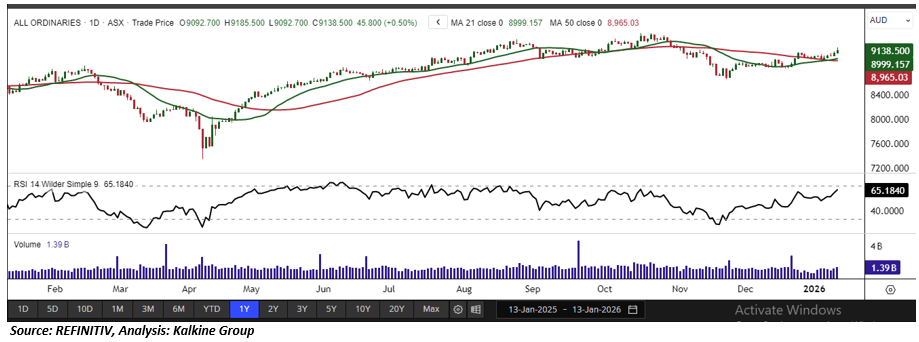
In the latest session, the S&P/ASX 200 Index advanced 45.80 points to close at 9,138.50, forming a modest bullish candlestick supported by strong trading volumes, reflecting sustained investor confidence. On the daily chart, the index continues to trade above its 21-period Simple Moving Average (SMA), which is acting as a key dynamic support and maintaining the short-term uptrend. The 8,920.50 support zone remains critical for preserving the current bullish structure, with a successful hold likely to encourage consolidation and further upside. On the weekly timeframe, prices remain well above the 50-period SMA, reinforcing a positive medium- to long-term technical outlook.


 Nov 12, 2026





 Please wait processing your request...