
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Source: Krish Capital Pty Ltd
Index Update: The Australian sharemarket closed higher on Wednesday, with the S&P/ASX 200 rising 26.90 points, or 0.31%, to finish at 8,830.40. The benchmark has gained 1.05% over the past five sessions but remains 2.48% below its 52-week high.
Sectors ended mostly positive, with nine of eleven closing in the green. Financials led the advance, climbing 1.32% on the day and 2.21% over the past five sessions. The rally in banking stocks helped offset the mining sector’s sharp declines (1.70% down), as concerns over the restart of a major Chinese lithium mine pressured sentiment around the struggling metal.
Macro Update: China’s consumer price index (CPI) came in weaker than expected, falling 0.4% year-on-year, compared with economist estimates of a 0.2% decline. This marks the first negative reading in three months.
Producer prices also remained under pressure, declining 2.9% year-on-year in August, following a 3.6% fall recorded in July.
Later tonight, the US Bureau of Labor Statistics will release its consumer price index and producer price index data for August, with the update scheduled for 10:30pm AEST.
Meanwhile, Reserve Bank of New Zealand governor Christian Hawkesby is set to speak at the Financial Services Council’s annual conference in Auckland tomorrow.
Top Market Movers: Clarity Pharmaceuticals Ltd (ASX: CU6) led the gains on Wednesday, advancing 7.09% to close at AUD 3.32. Judo Capital Holdings Ltd (ASX: JDO) followed with a 4.53% rise to AUD 1.73, while Telix Pharmaceuticals Ltd (ASX: TLX) added 4.34% to finish at AUD 14.42. On the downside, Liontown Resources Ltd (ASX: LTR) slumped 18.42% to AUD 0.775, Pilbara Minerals Ltd (ASX: PLS) declined 17.29% to AUD 1.985, and Iluka Resources Ltd (ASX: ILU) dropped 14.22% to AUD 5.55.
Commodity Update: The U.S. dollar held firm on Wednesday ahead of key inflation data that could shape upcoming Federal Reserve rate decisions. In commodities, gold slipped 0.23% to USD 3,674.10, while silver rose 0.73% to USD 41.64 and copper inched up 0.06% to USD 9,934.20. Brent crude gained 0.70% at USD 66.92, supported by Middle East tensions after Israel struck Hamas targets in Qatar and reports of potential new U.S. sanctions on Russian oil buyers.
Our Stance: The Australian sharemarket regained ground on Wednesday, with the S&P/ASX 200 closing at 8,830.40, lifted by gains in Financials that helped cushion heavy losses across lithium and mining names. Investor sentiment remained guarded, as concerns around China’s weakening inflation backdrop and renewed supply risks in lithium weighed on resources. Macro signals pointed to caution: China’s consumer prices fell 0.4% year-on-year, the first negative print in three months, while producer prices stayed in decline. Commodities were mixed, with gold easing while Brent crude advanced on heightened geopolitical tensions. With U.S. inflation data due tonight and regional central bank commentary ahead, markets are likely to navigate carefully, balancing global monetary signals against sector-specific pressures at home.
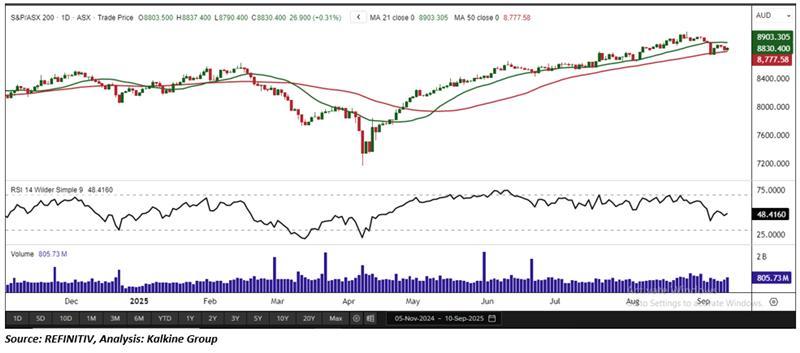
In its latest session, the S&P/ASX 200 Index gained 26.90 points to close at 8,903.30, supported by a bullish candlestick formation and strong trading volumes clear signs of sustained investor confidence. On the daily chart, the index continues to trade firmly above its 50-period Simple Moving Average (SMA), a dynamic support that underpins the short-term positive outlook. A key support zone is established at 8,740, with price stability above this level crucial to preserving the integrity of the uptrend. On the upside, a decisive breakout above this support-turned-resistance level would serve as strong bullish confirmation, potentially unlocking further momentum and shifting broader market sentiment firmly in favor of the bulls. From a broader perspective, the index’s sustained position above the 21-period SMA on the weekly chart reinforces its resilient long-term bullish foundation.


 Nov 12, 2026





 Please wait processing your request...