
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
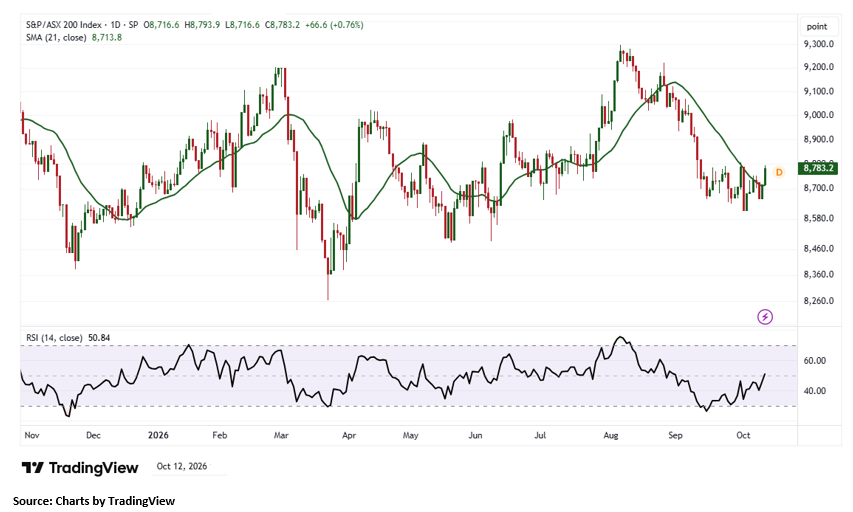
Index Update: Australia’s S&P/ASX 200 closed Monday 0.76% higher, gaining 66.60 points to reach 8,783.20. Financials (+1.56%) and Materials (+1.52%) outperformed, while Telecommunications Services (-1.94%) and A-REITs (-1.39%) recorded the steepest declines. Despite more sectors finishing lower, the benchmark extended its five-day gain to 1.11%. Financials also led weekly sector performance, rising 1.19%, while the broader index remained largely unchanged year-to-date, reflecting mixed market momentum amid uneven sector performance.
Macro Update: US consumer sentiment deteriorated further in October 2026 as persistent Inflation and rising living costs weighed on household confidence. The University of Michigan’s preliminary Consumer Sentiment Index declined to 46.3 from 48.1 in September, marking its third consecutive monthly fall. Short-term inflation expectations increased to 4.7%, while longer-term expectations rose to 3.5%. Lower-income households faced greater financial pressure amid elevated prices and borrowing costs. The weakening sentiment highlights growing economic uncertainty, with consumer spending patterns and future Federal Reserve policy decisions remaining key areas of focus.
Top Market Movers: IperionX (ASX:IPX) led the gainers, rising 5.909% to AUD 2.330, followed by Zip Co (ASX:ZIP), which advanced 5.555% to AUD 2.280. Megaport (ASX:MP1) gained 4.792% to close at AUD 19.680. Among the decliners, TPG Telecom (ASX:TPG) fell 4.897% to AUD 3.690, while Elevra Lithium (ASX:ELV) declined 4.802% to AUD 4.560. Deep Yellow (ASX:DYL) dropped 4.082% to AUD 0.940, completing the three largest declines among the stocks listed, with all six recording notable percentage movements during the trading session.
Commodity Update: The US dollar remained supported by expectations of further Federal Reserve tightening, despite a modest correction on Monday. Gold gained 0.20% to USD 4,228.80, silver advanced 0.48% to USD 61.35, and copper increased 0.31% to USD 14,593.80. Brent Crude oil fell 1.47% to USD 103.18 a barrel amid expectations of increased Russian supplies after Donald Trump said Russia and Ukraine had agreed to halt attacks on each other’s energy facilities following a US diesel-supply deal with Moscow.
Our Stance: The ASX 200’s positive close reflects underlying resilience, although uneven sector participation suggests the recovery remains selective. Strength in Financials and Materials provided support, while weakness in Telecommunications Services and A-REITs highlighted lingering caution. Gains in precious metals offered a constructive signal for commodity-linked stocks, although declining oil prices added uncertainty to the energy outlook. Meanwhile, deteriorating US consumer sentiment and elevated inflation expectations could complicate the global Interest Rate outlook. Investors may benefit from monitoring sector rotation, Commodity price movements and upcoming economic indicators, as sustained market momentum will likely depend on broader participation and improving macroeconomic confidence.
From a technical perspective, the S&P/ASX 200 Index advanced in the latest trading session, maintaining a constructive near-term outlook despite the recent pullback. The index continues to hold above key support at 8,730.50, which remains crucial for preserving the broader bullish structure. Sustained trading above this level could help stabilise market sentiment and support a recovery towards recent highs. On the upside, immediate resistance is positioned near 8,820, and a decisive breakout above this level could strengthen buying momentum and open the way for further gains towards the next target of 8,880. However, a sustained break below 8,730.50 could weaken the technical outlook and increase downside risks.


 Nov 12, 2026





 Please wait processing your request...