
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
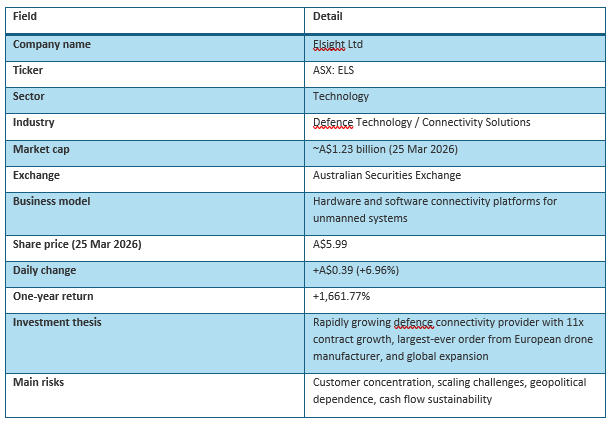
Elsight Ltd (ASX:ELS) is an ASX-listed technology company that develops proprietary connectivity solutions for unmanned systems, including drones, autonomous ground vehicles, and robotic platforms. The company's flagship product, the Halo platform, is designed to maintain reliable, secure communication links for mission-critical applications in contested or challenging environments.
As of 25 March 2026, Elsight's share price stood at A$5.99, up 6.96 per cent on the day, with a market capitalisation of approximately A$1.23 billion and a one-year return of 1,661.77 per cent. Those numbers place Elsight among the most dramatic growth stories on the ASX in recent memory.
At a Glance: Elsight
Business Model and Products
Elsight's core proposition is solving the connectivity problem for unmanned systems. When a military drone or autonomous vehicle is deployed in a remote, urban, or electronically contested environment, maintaining a stable and secure data link is critical. Dropped connections can mean lost assets, failed missions, or safety hazards.
The Halo platform addresses this by aggregating multiple communication channels, including cellular, satellite, and radio frequency links, into a single, resilient connection. The system automatically switches between available networks to maintain uptime, a capability that is increasingly valuable as militaries worldwide expand their use of unmanned systems.
In addition to Halo, the company offers the AllSight Management Platform for fleet-level monitoring and control, and HeatSight, a thermal sensing solution. The product suite positions Elsight as a full-stack connectivity provider for the unmanned systems market.
Defence Sector Catalysts
The catalysts behind Elsight's extraordinary price performance are concrete and substantial. In December 2025, the company secured a US$21 million order from a European defence drone manufacturer, which it described as the largest single order in the company's history. This was part of a broader trend: Elsight reported eleven-fold year-over-year growth in contract wins during 2025.
By March 2026, the company had over US$22 million in confirmed orders and projected that it would exceed A$30 million in revenue for the 2026 financial year. Management announced a global expansion of its sales leadership team across the United States, Europe, Israel, and Asia, signalling confidence in sustained demand.
The company claims more than 500,000 operational hours of its technology in contested environments globally, a track record that serves as a form of real-world validation that is difficult for competitors to replicate quickly.
These developments are occurring against a backdrop of rapidly increasing global defence spending, particularly in drone and unmanned systems technology. The Russia-Ukraine conflict, tensions in the Indo-Pacific region, and the broader shift toward autonomous military capabilities have created a structural tailwind for companies like Elsight.
Financial Profile
Elsight's financial trajectory has improved markedly. The company reported record revenue in the first half of the 2025 financial year and achieved cash flow breakeven, a critical milestone for a growth-stage technology company.
However, investors should recognise that a single half-year of cash flow breakeven does not equate to sustained profitability. Defence contracts can be lumpy, with large orders followed by quieter periods. Revenue recognition timing, delivery schedules, and customer payment terms can all create volatility in reported financial results.
The company's transition from early-stage development to commercial scale-up is promising but incomplete. Investors should monitor order book growth, revenue conversion rates, gross margins, and operating cash flow in upcoming reporting periods.
Risks
- Customer and contract concentration: A significant portion of revenue may depend on a small number of large defence contracts. Delays, cancellations, or renegotiations could materially impact financial performance.
- Scaling challenges: Rapidly expanding sales teams and production capabilities while maintaining product quality and customer satisfaction is operationally complex.
- Geopolitical risk: Defence spending is influenced by geopolitical dynamics that can shift rapidly. A de-escalation in global tensions, while positive for the world, could reduce demand for Elsight's products.
- Competition: The unmanned systems connectivity market is attracting significant investment from larger defence contractors and technology companies.
- Valuation: At a market capitalisation of A$1.23 billion, the stock is priced for aggressive growth. Any stumble in execution could lead to a sharp correction.
Section Recap
Elsight represents a compelling intersection of technology and defence, with real contracts, real revenue growth, and a credible path to profitability. The eleven-fold contract growth and blue-chip European defence customers provide substance behind the share price surge. However, the valuation leaves little room for disappointment, and beginner investors should be wary of chasing a stock that has already appreciated by more than 1,600 per cent in a single year.


 Nov 12, 2026





 Please wait processing your request...