
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Elsight shares are up 824% in a year, supported by rapid revenue growth and expanding defence exposure.
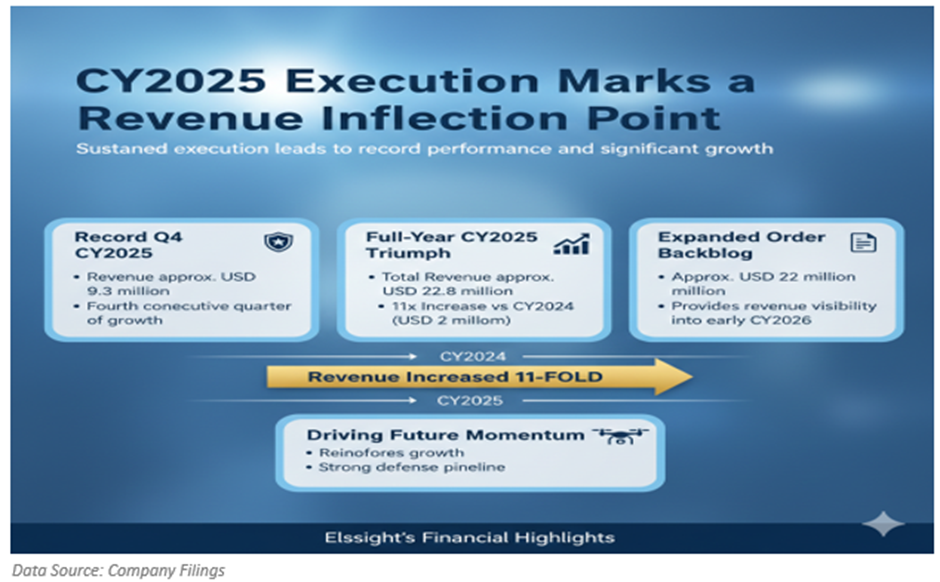
- The company’s CY2025 revenue climbed to USD 22.8 million, marking an eleven-fold increase from USD 2.0 million in CY2024.
- Company’s Order backlog expanded to approximately USD 22 million, providing revenue visibility into early CY2026.
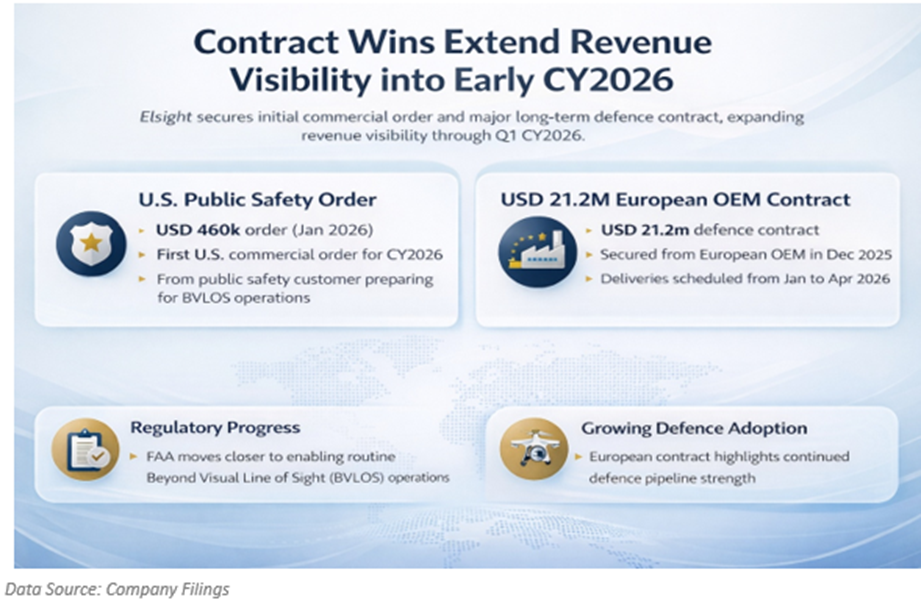
- Major contracts totalling over USD 21.6 million extend revenue visibility into early CY2026
- Elsight enters CY2026 with USD 59 million in cash, higher order backlog, and global expansion momentum.
Elsight Ltd (ASX:ELS) shares have surged by 824.39% over the past one year and trading at AUD 3.79 as on 9 February 2026. This performance reflects a period of sustained operational execution, supported by accelerating revenues, expanding contract wins, and deeper engagement across global defence and public safety markets
Although the share price has declined around ~11.24% over the past five days, its longer-term trajectory continues to draw investor attention as the company delivered a steady run of contract wins, expanded its operational footprint across key defence markets, and began reporting consistently higher revenues. Together, these developments have shifted the market’s focus toward Elsight’s ability to scale its business in line with rising demand for unmanned and autonomous systems.
Elsight Limited (ASX:ELS) is a provider of carrier-agnostic, multi-path connectivity solutions for drones and other unmanned systems. Its flagship product, Halo, combines cellular, satellite and RF communications through multi-link bonding to enable reliable Beyond Visual Line of Sight (BVLOS) operations in demanding environments. The Company serves defence, public safety and commercial applications globally and was founded in 2009.
Defence and Public Safety Demand Drives Market Opportunity
The broader defence landscape has played an important role in the Elsight’s upward trajectory. Governments across the U.S., Europe and Asia-Pacific are increasing spending on uncrewed and autonomous systems, supported by rising defence budgets and evolving operational doctrines.
Within this environment, Elsight has expanded its international presence, added regional capability across key defence markets, and moved toward a more locally embedded go-to-market approach. These developments have taken place alongside increasing engagement with defence contractors and government customers, setting the context for the company’s recent financial performance and operational updates discussed in the sections that follow.
Product and Platform Progress: Halo Traction and Aura Commercialization
Operational progress during the quarter extended beyond financial performance. Elsight delivered its first Aura units, transitioning the product from development into production and expanding the company’s addressable market beyond uncrewed platforms.
In parallel, Halo continued to gain traction within the U.S. defence ecosystem, with successful demonstrations to multiple Department of Defence units and selection by the Defence Innovation Unit for Phase 3 of Project G.I., supported by funding for final fielding and regulatory processes ahead of expected production procurement in the first half of CY2026.
Commercial and recurring revenue streams also continued to build. Software licences, cloud services and connectivity subscriptions generated approximately USD 2.6 million during 2025, accounting for 12% of total revenue and reflecting favourable year-on-year growth. This high-margin revenue mix, alongside software-like gross margins of around77%, underpins longer-term financial visibility.
With USD 59 million in cash at quarter end, Elsight enters CY2026 with balance sheet strength to support contract execution, global expansion and conversion of its growing pipeline into sustained multi-year growth.
Financial Performance Reflects Shift to a Scalable, Cash-Generating Model
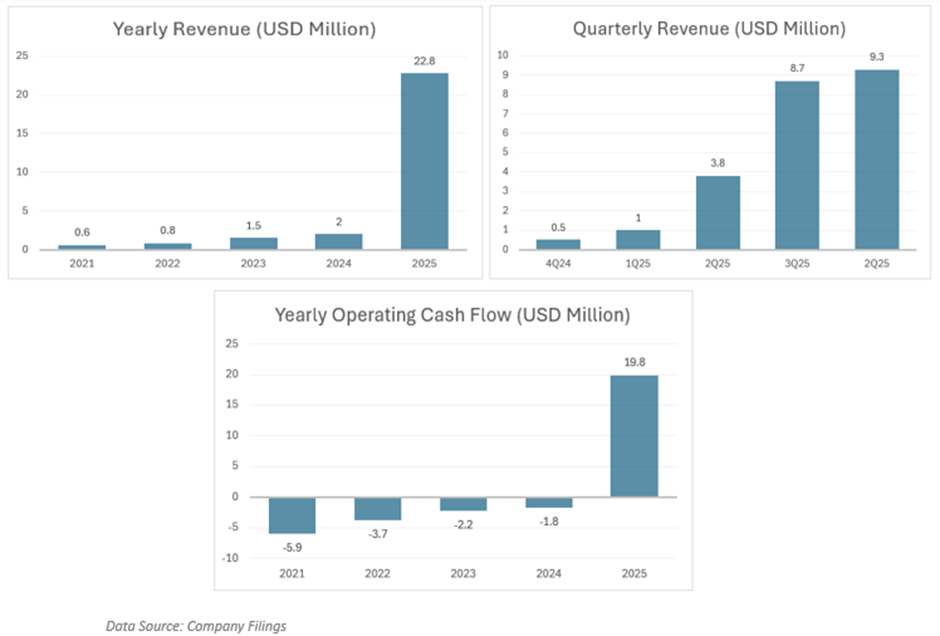
On a full-year basis, the revenue trajectory highlights a clear acceleration into CY2025 with total revenue reaching USD 22.8 million compared with USD 2.0 million in CY2024, representing an 1040% Y-o-Y increase.
The Company’s operating cash flow also improved from a negative USD 1.8 million in CY24 to a positive USD 19.8 million in CY25, representing a yearly increase of 1200%. This sharp improvement shows a clear shift from cash burn to cash generation within a yea
This favourable uplift reflects a year of sustained execution rather than isolated wins, as defence programs moved from early-stage engagement into scaled deliveries, supported by improving order visibility and repeat demand across key markets.
Quarterly performance further reinforces this momentum, with the latest quarter delivering the company’s highest ever revenue of USD 9.3 million, marking the fourth consecutive quarter of growth. This uplift was driven by a scalable, high-margin business model built around the Halo platform, favourable contract structures with upfront payments, and a growing mix of recurring software and hardware revenues. Together, these factors highlight a financially efficient growth profile as the company enters CY2026 with favourable operating leverage and revenue visibility.
Outlook: Scaling Execution Amid Higher Order Visibility
Looking ahead, Elsight enters CY2026 with higher order visibility, improving cash generation, and multiple products transitioning into scaled deployment. Key priorities include executing contracted deliveries, expanding regional presence, and converting late-stage pipeline opportunities into repeat programs.
Risks remain, including execution complexity as volumes scale, customer concentration within defence markets, and regulatory timing for broader commercial BVLOS adoption. However, the combination of contracted revenue, high-margin recurring streams, and balance sheet strength positions the company to navigate these challenges as demand for autonomous connectivity infrastructure continues to grow.
Stock Information
ELS has surged ~6.76% over the past one month, while posting a gain of approximately ~75.46% and ~824.39% over the past six months and one year respectively. The stock has a 52-week high and 52-week low of AUD 5.00 and AUD 0.32, respectively, and is currently trading above the average of 52-week high-low level.
From a technical perspective, ELS remains in a broader uptrend, though near-term momentum has softened following a pullback from recent highs. Price has slipped below the 21-day moving average, signalling short-term consolidation, but continues to hold above the rising 50-day moving average, which remains a key medium-term support. The RSI near 48.36 indicates cooling momentum rather than a bearish reversal. Provided price holds above the 50-day MA, the broader bullish structure remains intact, with a move back above the 21-day MA needed to restore upside momentum.
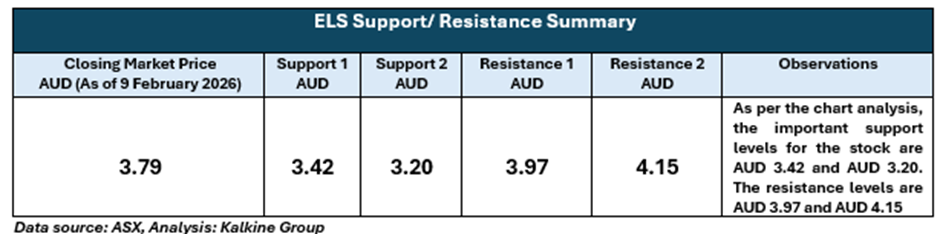
Note 1: Past performance is not a reliable indicator of future performance.
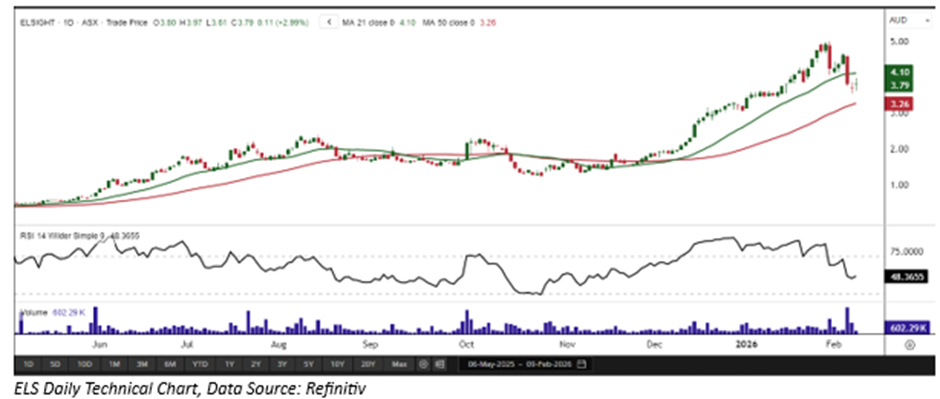
Note 2: The reference data for all price data, currency, technical indicators, support, and resistance levels is 9 February 2026. The reference data in this report has been partly sourced from EODHD/Others.
Technical Indicators Defined
Support: A level at which the stock prices tend to find support if they are falling, and a downtrend may take a pause backed by demand or buying interest. Support 1 refers to the nearby support level for the stock and if the price breaches the level, then Support 2 may act as the crucial support level for the stock.
Resistance: A level at which the stock prices tend to find resistance when they are rising, and an uptrend may take a pause due to profit booking or selling interest. Resistance 1 refers to the nearby resistance level for the stock and if the price surpasses the level, then Resistance 2 may act as the crucial resistance level for the stock


 Nov 12, 2026





 Please wait processing your request...