
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- The S&P/ASX 200 Information Technology Index is rising 2.84% to 1,907.4 points during trading on 5 August 2026.
- XIJ has advanced 10.17% over one week and 6.41% over one month, although it remains down 12.15% in 2026.
- WiseTech Global is leading the selected technology shares with a 6.45% gain, followed by Life360 at 3.46% and Codan at 2.99%.
- Buying is shifting towards companies with recurring revenue, visible earnings and contracted infrastructure demand after July’s correction.
Australian technology shares are moving back into focus as buyers return to some of the sector’s largest and more established businesses. The latest session is lifting software providers, data-centre operators and technology manufacturers, extending a recovery that has gathered pace over the past week.
The S&P/ASX 200 Information Technology Index is trading at 1,907.4 points, up 52.7 points or 2.84%. WiseTech Global, Xero, NEXTDC, TechnologyOne, Codan and Life360 are all advancing as the market reassesses companies that experienced substantial valuation pressure earlier in the year.
The rebound does not suggest that enthusiasm for artificial intelligence has disappeared. Instead, capital appears to be moving away from businesses relying mainly on future AI potential and towards companies that can connect technology adoption with recurring revenue, customer growth, earnings or contracted infrastructure demand.
Technology Buying Extends Beyond the Opening Rally
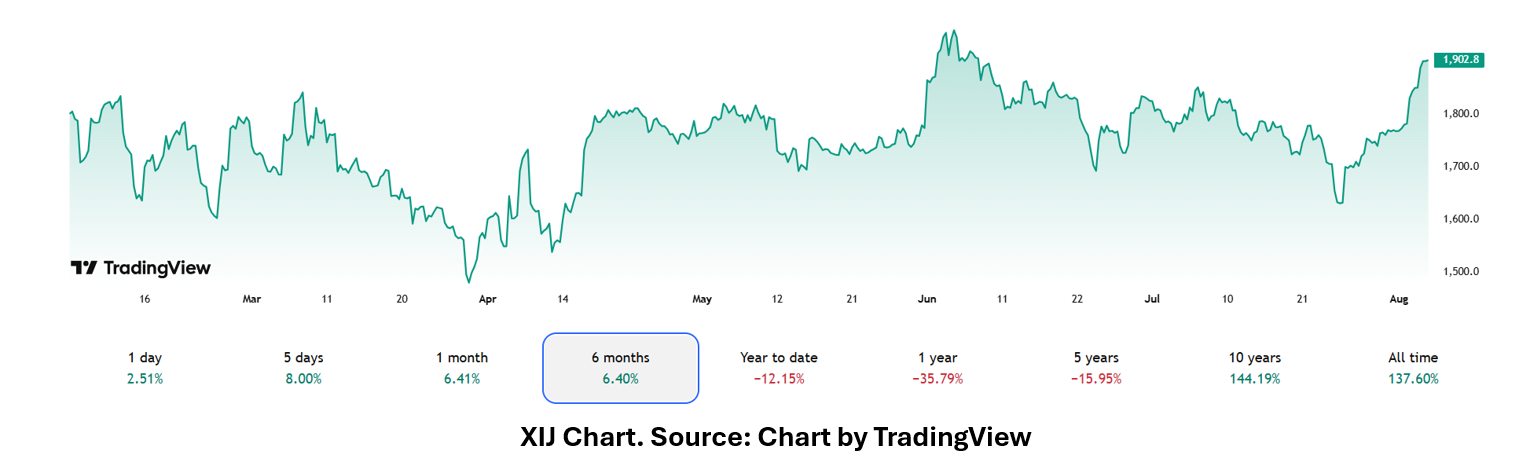
Technology shares opened sharply higher, briefly surrendered part of the advance and then resumed climbing through the morning. XIJ moved above 1,900 points and approached 1,911 before modest profit-taking brought it back towards 1,907.
The index is retaining most of its early gain, indicating that buying is extending beyond the opening move. Several brief consolidations have interrupted the advance, but sellers have so far failed to push the sector back towards its previous close of approximately 1,854.7 points.
The 1,900-point area is becoming an immediate marker for the session. Continued trading above that level would show that buyers are absorbing short-term selling. A reversal below the morning’s consolidation range, however, could suggest that part of the rally reflects short covering after July’s decline.
A Rapid Rebound Within a Wider Correction
The S&P/ASX 200 Information Technology Index covers 14 companies in the ASX 200 that are classified within the GICS Information Technology sector. Its constituents include software, technology services and computer-equipment companies, with the index rebalanced quarterly.
The immediate recovery is becoming increasingly visible:
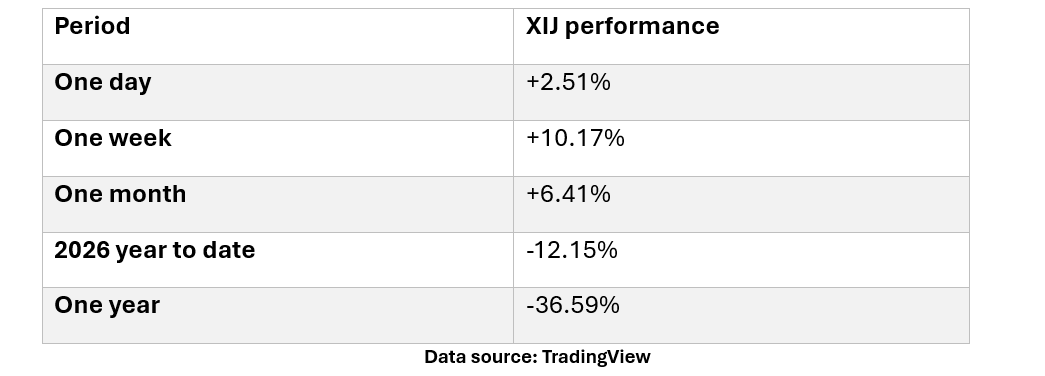
The 10.17% weekly gain indicates that the change in sentiment is not confined to one session. However, XIJ remains 36.59% lower over one year and 12.15% lower since the beginning of 2026.
That contrast defines the current rotation. The sector is recovering from heavily reduced valuations, but the longer-term trend has not yet been repaired. Earnings reports, guidance and cash-flow delivery will determine whether the latest rise develops into a sustained revaluation or remains a relief rally.
WiseTech Leads as the Market Revisits Logistics Software
WiseTech Global (ASX:WTC) is leading, rising 6.45% to AUD 40.30. The stock is trading close to its session high of AUD 40.32 after touching AUD 38.87, while volume has reached 1,548,555 shares. Its market capitalisation stands at approximately AUD 13.55bn.
The latest move follows a difficult period for the logistics software provider. WiseTech shares remain 65.01% lower over one year, leaving the company among the clearest examples of the valuation reset across Australian technology.
Operationally, WiseTech continues to expand its CargoWise logistics platform while integrating e2open. The company has guided to FY26 revenue of AUD 1.39–1.44bn and EBITDA of AUD 550–585mn. It serves more than 17,000 logistics customers across 193 countries, including 24 of the world’s 25 largest freight forwarders.
The recovery places greater attention on the approaching FY26 result. Revenue delivery, margins and progress integrating e2open will help determine whether the latest buying represents a durable reassessment of WiseTech’s earnings outlook.
Xero’s Recovery Hinges on Its US Expansion
Xero (ASX:XRO) is trading 2.41% higher at AUD 75.58 after moving between AUD 74.00 and AUD 75.80. Volume stands at 575,501 shares, while its market capitalisation is approximately AUD 12.9bn.
Despite the latest advance, Xero remains 57.18% lower over one year. Concerns surrounding acquisition costs, margin pressure and the company’s US expansion have weighed on the stock even as revenue continues to grow.
FY26 revenue increased 31% to approximately NZD 2.75bn. However, earnings absorbed costs associated with Xero’s acquisition of US payments platform Melio and its wider push into the American small-business market. The company has also announced a share-buyback programme.
Xero is developing artificial-intelligence functions across its accounting platform, including JAX, which is intended to automate financial and administrative workflows. The strategic direction gives Xero exposure to AI adoption, but the market is likely to judge progress through subscriber growth, payment revenue and operating margins rather than product announcements alone.
NEXTDC Offers Direct Exposure to AI Infrastructure
NEXTDC (ASX:NXT) is advancing 1.14% to AUD 14.20. The shares are trading between AUD 14.12 and AUD 14.33 on volume of 937,093, valuing the company at approximately AUD 10.79bn. Its one-year decline is limited to 1.66%, considerably narrower than those recorded by several software companies.
NEXTDC sits on the infrastructure side of the technology cycle. Its data centres provide the computing capacity, connectivity and physical systems required by cloud platforms, enterprises and AI workloads.
Net revenue increased 13% to AUD 189.2mn in 1H26, while total revenue rose 13% to AUD 231.8mn, according to the company’s half-year results. NEXTDC retained FY26 underlying EBITDA guidance of AUD 230–240mn and reported an expanding pipeline of contracted capacity, reservations and customer options.
The demand outlook is significant, but so is the investment requirement. Data-centre construction consumes substantial capital and depends on access to power, suitable land, equipment and timely project delivery. Investors will be watching whether contracted capacity converts into revenue quickly enough to support the company’s expansion programme.
TechnologyOne Puts Recurring Revenue at the Centre
TechnologyOne (ASX:TNE) is rising 1.84% to AUD 32.63 after trading between AUD 31.94 and AUD 32.79. Volume has reached 512,312 shares and market capitalisation stands near AUD 10.68bn.
The shares remain 19.99% lower over one year, despite continued growth across the enterprise software business. TechnologyOne supplies mission-critical software to government bodies, universities and other large organisations, creating a relatively visible subscription-revenue base.
Annual recurring revenue increased 17% in 1H26, while SaaS and recurring revenue rose 13% to AUD 299.2mn. Profit before tax advanced 9% to AUD 89.1mn and the interim dividend increased 21% to AUD 0.08 per share, according to the company’s FY26 half-year presentation.
TechnologyOne is also incorporating AI into its enterprise platform. Unlike early-stage AI developers, however, it can distribute new products through an existing customer network and recurring-revenue model. Adoption rates, contract expansion and progress towards its longer-term annual recurring revenue target will remain central to the outlook.
Codan Extends Its Earnings-Led Advance
Codan (ASX:CDA) is trading 2.99% higher at AUD 41.29, near its session high of AUD 41.36. The stock has touched a low of AUD 39.30, with 467,915 shares changing hands. Market capitalisation is approximately AUD 7.51bn.
Codan differs from most of the selected technology companies because its shares are already 83.76% higher over one year. Its latest rise is extending an earnings-led revaluation rather than recovering a deep annual loss.
The company operates across communications, metal detection and mining technology. First-half FY26 revenue increased 29% to AUD 393.5mn, while EBIT rose 52% to AUD 99.8mn. Codan subsequently indicated FY26 expectations of approximately AUD 170mn in net profit and AUD 235mn in EBIT.
Its upcoming full-year result will test whether these expectations have been met and whether growth can continue into FY27. The market will also assess margins across Codan’s communications and metal-detection businesses.
Life360 Balances User Growth With Profitability
Life360 (ASX:360) is gaining 3.46% to AUD 29.455. The shares are trading between AUD 29.37 and AUD 30.27, with volume reaching 1,486,325. The company is valued at approximately AUD 5.25bn and remains 25.30% lower over one year.
The family-safety platform is attracting attention as user growth increasingly translates into subscription and advertising revenue. First-quarter 2026 revenue increased 38% to USD 143.1mn, while monthly active users rose 17% to approximately 97.8mn.
Paying circles reached three million and advertising revenue increased to a first-quarter record of USD 19.7mn, according to Life360’s Q1 results. The company has also authorised a share-repurchase programme.
Life360’s next updates will show whether it can maintain user growth while improving monetisation and profitability. Advertising revenue, international subscriptions and operating cash flow are likely to receive particular attention.
What Investors May Watch Next
The technology rotation now faces an earnings test. WiseTech must demonstrate progress integrating e2open, while Xero needs to show that the Melio acquisition and US expansion can produce acceptable returns. NEXTDC’s contracted capacity must translate into revenue without allowing capital requirements to overwhelm future cash flow.
TechnologyOne’s recurring-revenue growth, Codan’s full-year earnings and Life360’s subscriber economics will provide further evidence about the quality of the sector recovery.
At the index level, holding above 1,900 points would preserve the constructive intraday structure. More importantly, sustained gains will require earnings and guidance to support the rapid 10.17% weekly advance.
Risks
- The rebound may reverse if company results or guidance fail to meet market expectations.
- XIJ remains substantially lower over one year despite its recent recovery.
- Acquisition integration may affect margins and management attention at WiseTech and Xero.
- Data-centre expansion requires significant capital and access to reliable power infrastructure.
- Elevated valuations may leave profitable technology companies sensitive to interest-rate expectations.
- AI investment may not generate revenue or productivity improvements as quickly as anticipated.
- Currency movements may affect companies earning a substantial proportion of revenue overseas.


 Nov 13, 2026





 Please wait processing your request...