
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Information Technology (XIJ) remained in the Leading quadrant, although its trajectory showed declining relative momentum.
- Consumer Discretionary (XDJ) stayed in the Leading quadrant, with its recent trajectory indicating a modest loss of momentum.
- Real Estate (XPJ) and Consumer Staples (XSJ) occupied the Leading quadrant, supported by improving relative momentum.
- Materials (XMJ) and Resources (XJR) were positioned in the Improving quadrant, indicating a recovery in relative momentum.
- Financials (XFJ), Industrials (XNJ) and Healthcare (XHJ) were in the Weakening quadrant, reflecting negative momentum conditions.
- Utilities (XUJ), Energy (XEJ) and Communication Services (XTJ) remained in the Lagging quadrant, although some trajectories suggested attempts to recover.
- The chart highlighted substantial differences in sector rotation, with technology maintaining a strong relative position while several sectors struggled to improve their momentum profiles.
The ASX sector relative performance visualisation dated 12 October 2026 presented a mixed momentum landscape, with Leadership concentrated in Information Technology, Consumer Discretionary, Real Estate and Consumer Staples. Materials and Resources occupied the Improving quadrant, suggesting a recovery in their relative momentum, while Financials, Industrials and Healthcare remained in Weakening territory.
The chart indicates that sector positioning and momentum direction should be assessed together. A sector in the Leading quadrant may still be losing momentum, while one in the Improving quadrant may be building strength without yet establishing leadership. This distinction is central to understanding the market's current rotation pattern.
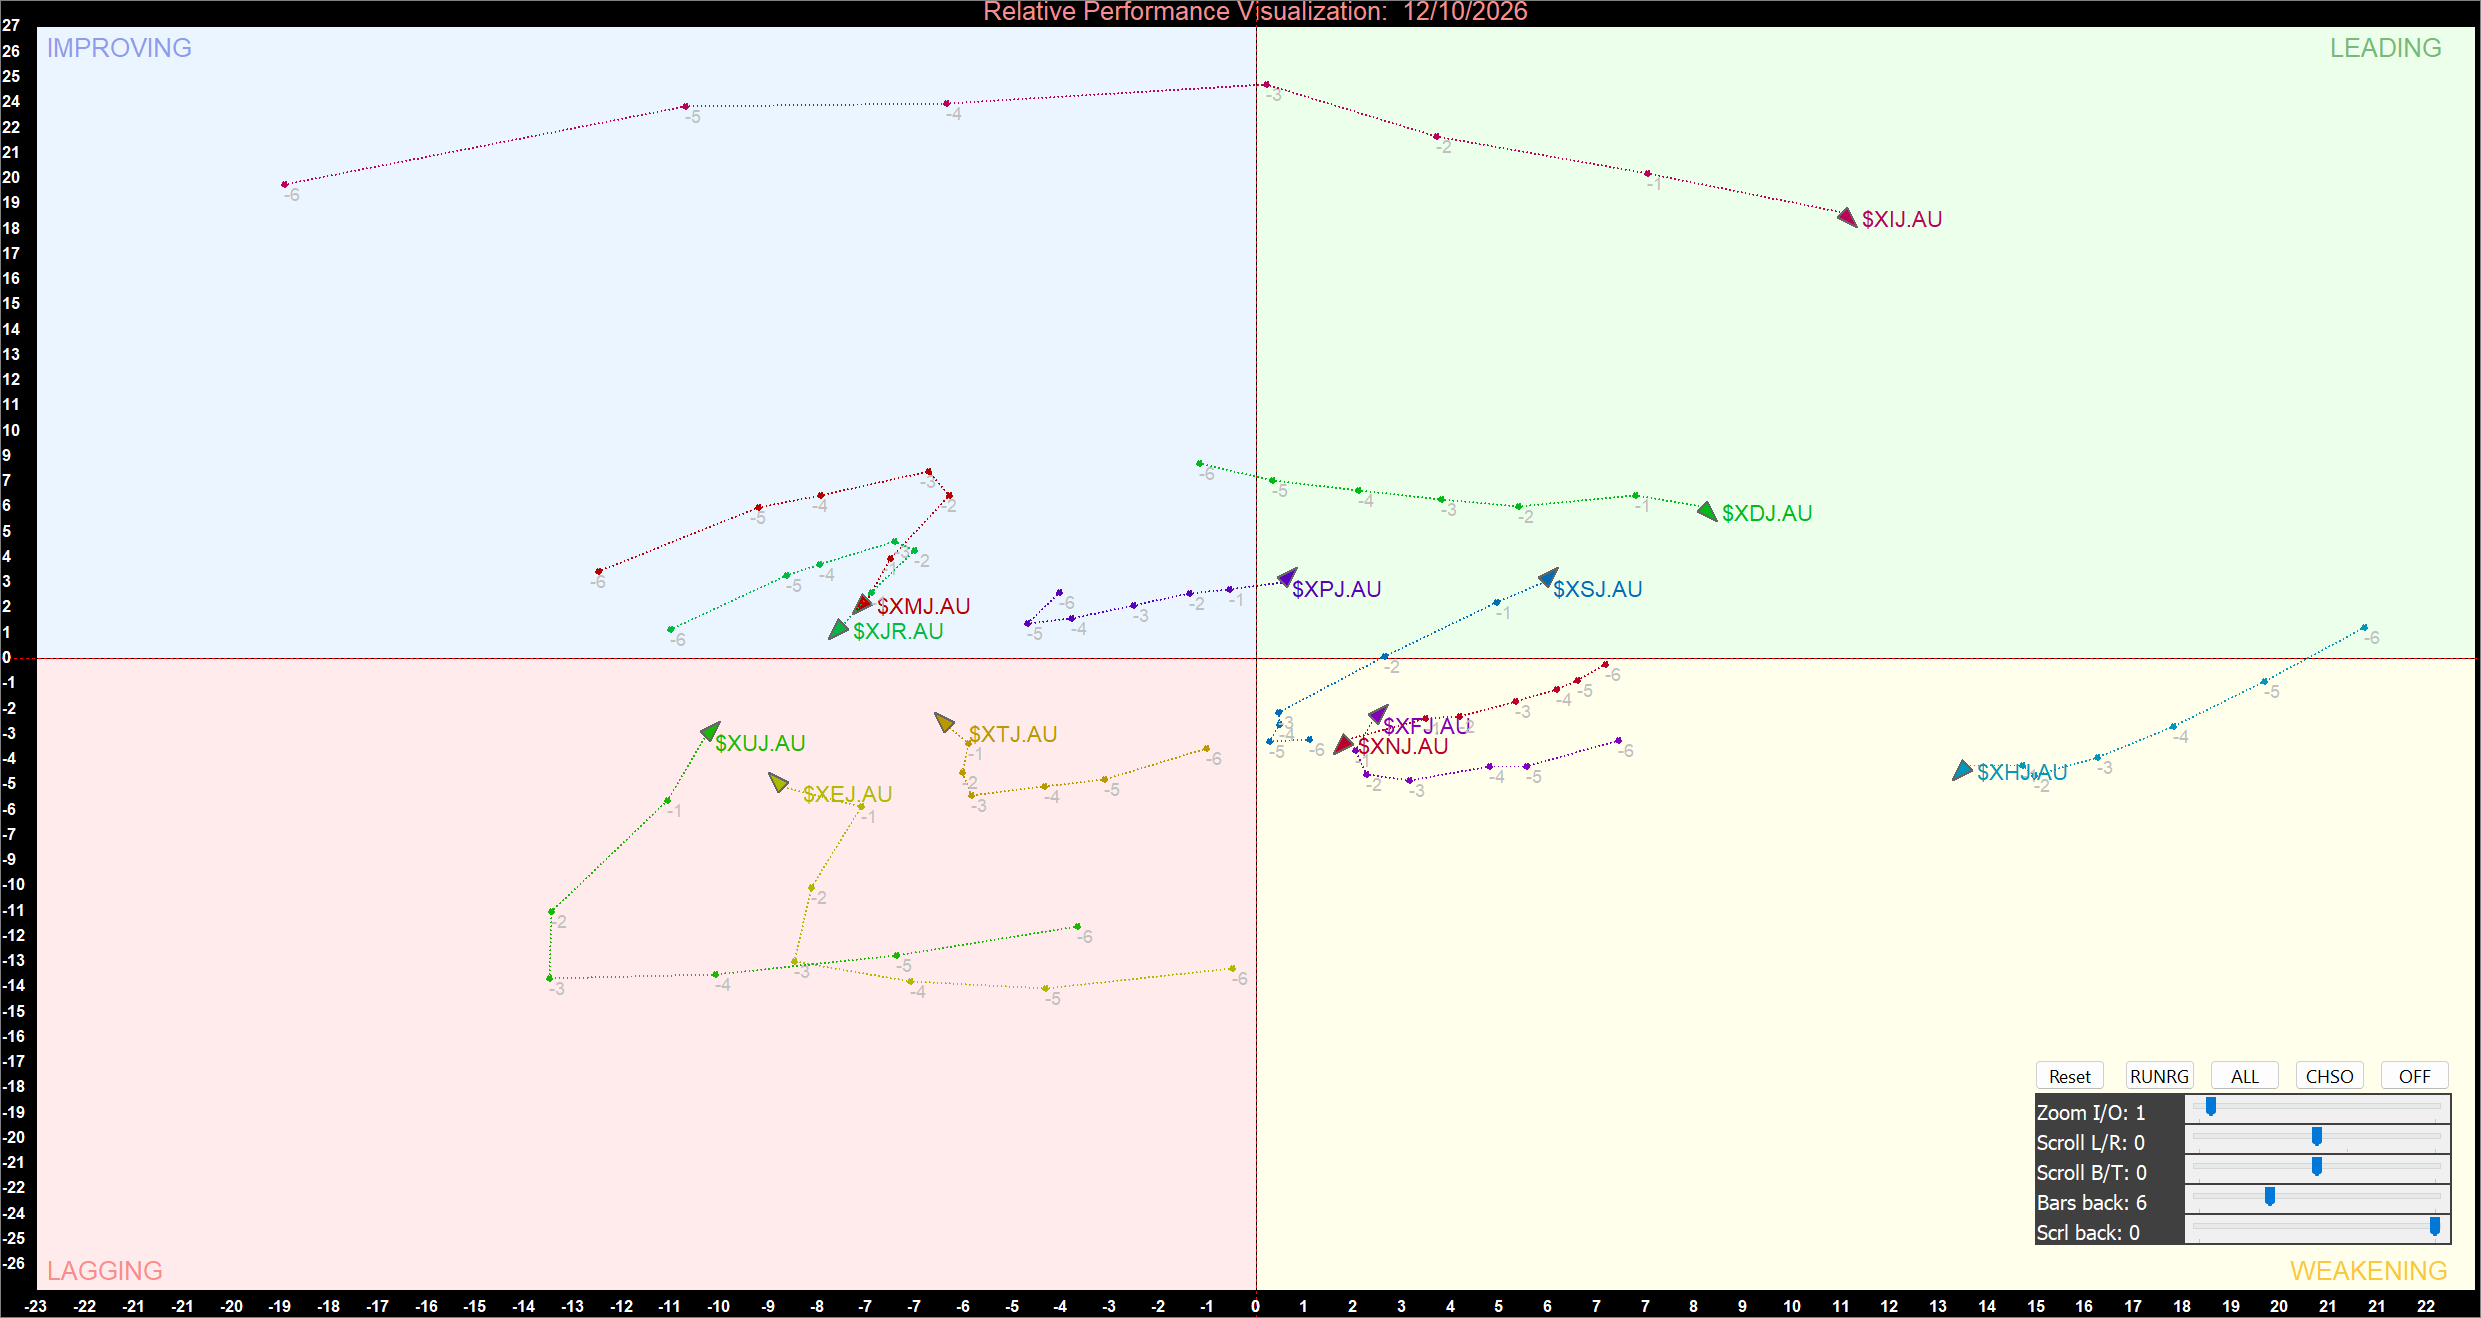
ASX Sector Relative Momentum Chart at the closing price of 12/10/2026. Powered by: amibroker.com
Information Technology Maintains Leadership
Information Technology was positioned well inside the Leading quadrant, making it one of the strongest sectors in the relative momentum landscape. However, its trajectory had moved downward from earlier observations, indicating that momentum was easing despite its favourable position.
This combination suggests that technology continued to demonstrate strong relative performance, but its leadership was becoming less forceful. Investors monitoring the sector should distinguish between continued leadership and accelerating momentum. A sustained downward trajectory could eventually lead to a transition into the Weakening quadrant if relative momentum deteriorates further.
Consumer Discretionary also remained in the Leading quadrant. Its trajectory showed a gradual decline from earlier readings, followed by a modest recovery near the latest observation. This suggests that the sector retained relative strength but had not established a decisive renewed acceleration.
Real Estate and Consumer Staples occupied the Leading quadrant as well. Both sectors were positioned above the horizontal zero axis, indicating positive relative momentum. Their trajectories suggested improving conditions near the latest observations, although continued movement would be needed to establish whether the improvement could be sustained.
Materials and Resources Show Improving Momentum
Materials and Resources were positioned in the Improving quadrant, making them important sectors to monitor for potential changes in leadership. Their trajectories indicated a recovery from earlier momentum weakness, suggesting that relative performance was improving.
Materials showed a sharp recovery in its recent trajectory, while Resources also moved toward stronger momentum readings. These developments indicate that both sectors were attempting to regain relative strength after weaker earlier observations.
However, the Improving quadrant does not automatically mean that a sector has become a market leader. It indicates that momentum is improving while relative strength remains below the leading threshold. A sustained move across the vertical zero axis would provide stronger evidence that these sectors were transitioning toward leadership.
Investors should therefore monitor whether Materials and Resources continue advancing toward the Leading quadrant or lose momentum before completing the transition.
Financials, Industrials and Healthcare Lose Momentum
Financials, Industrials and Healthcare were positioned in the Weakening quadrant. These sectors remained to the right of the vertical zero axis but below the horizontal zero axis, indicating that their relative position remained comparatively strong while momentum was weakening.
Financials clustered close to the central axes, suggesting a relatively modest but negative momentum profile. Its position makes the next directional move important: a recovery above the horizontal axis could signal renewed strength, while further deterioration could push the sector toward the Lagging quadrant.
Industrials also remained near the centre of the chart, with its trajectory indicating limited momentum and a weak relative momentum reading. A sustained improvement would be needed to restore a more favourable position.
Healthcare was positioned farther to the right and below the horizontal axis. This indicated relatively strong positioning on the horizontal dimension but negative momentum on the vertical dimension. Its trajectory suggested that the sector had experienced a deterioration in momentum despite retaining a comparatively favourable relative position.
Utilities, Energy and Communication Services Remain Lagging
Utilities, Energy and Communication Services occupied the Lagging quadrant, reflecting weak relative momentum conditions.
Utilities showed a notable upward trajectory from earlier negative readings toward the centre of the chart. This movement suggested that its momentum was recovering, although the sector remained in the Lagging quadrant at the latest observation.
Energy also displayed a recovery attempt after a period of deeper negative momentum. Nevertheless, its latest position remained below and to the left of the central axes, indicating that the recovery had not yet translated into a stronger relative position.
Communication Services continued to display weak momentum, with its trajectory remaining in negative territory. Although its position differed from those of Utilities and Energy, the sector had not demonstrated a convincing transition toward the Improving quadrant.
These sectors require evidence of sustained momentum recovery before their relative positions can be considered materially stronger.
Bottom Line
The ASX sector momentum chart for 12 October 2026 showed a market characterised by established leadership, emerging recoveries and persistent weakness. Information Technology and Consumer Discretionary remained in the Leading quadrant, while Real Estate and Consumer Staples also maintained favourable positions. Materials and Resources were the principal sectors in the Improving quadrant, suggesting potential future changes in leadership.
Meanwhile, Financials, Industrials and Healthcare remained in the Weakening quadrant, and Utilities, Energy and Communication Services occupied the Lagging quadrant.
The key signal is the direction of each sector's trajectory rather than its quadrant alone. Investors should monitor whether Materials and Resources continue improving, whether technology leadership stabilises, and whether the weakest sectors can generate sustained momentum recovery. A shift across quadrant boundaries would provide further evidence of changing sector leadership.


 Nov 12, 2026





 Please wait processing your request...