
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- The 2026 ASX reporting season marks a clear inflection point for technology and biotech penny stocks, with investor capital rotating away from narrative-driven names toward companies demonstrating tangible commercial progress.
- Clinical-stage biotech face intensifying scrutiny on cash runway and trial timelines, with binary outcomes continuing to define valuations.
- Industrial technology companies are entering a critical commercialisation phase — early revenue generation is now the primary differentiator for investor interest.
- Market repricing is ongoing: companies unable to articulate a credible path to profitability are experiencing multiple compression regardless of their technology's underlying merit.
Sector Overview
For much of the last decade, ASX-listed technology and biotech penny stocks thrived on the currency of potential. Compelling narratives — revolutionary drug platforms, next-generation manufacturing technologies, AI-powered wagering systems — were enough to attract speculative capital and sustain elevated valuations. In 2026, that dynamic has fundamentally shifted.
Following a reporting season that prioritised financial discipline over innovation storytelling, investors are applying a harder lens to the technology and biotech small cap space. The central question is no longer "What could this company become?" but rather "What has it delivered, and when will it generate sustainable cash flow?"
This recalibration is reshaping capital allocation across the sector. Companies with real — if early-stage — revenue streams are attracting disproportionate interest, while those with high cash burn and uncertain timelines are being systematically repriced. For penny stock investors, this environment rewards research depth and patience over momentum trading.
This article profiles three of the most-watched ASX technology and biotech penny stocks as of April 2026, examining their commercial trajectories, financial positions, management strategies, and price performance.
Company Profiles
Recce Pharmaceuticals (ASX: RCE)
Price: ~A$0.465 | Market Cap: ~A$133 million
Company Overview
Recce Pharmaceuticals is a clinical-stage biotechnology company developing a novel class of synthetic anti-infective compounds. The company's lead candidate, RECCE® 327, targets bacterial infections — including drug-resistant strains — positioning Recce within the fast-growing antimicrobial resistance (AMR) space, which the World Health Organisation has identified as one of the most significant global health threats of the coming decades.
Unlike traditional antibiotics derived from natural sources, Recce's synthetic polymer platform is designed to reduce the risk of bacterial resistance developing over time. This technological differentiation gives the company a credible scientific rationale that has attracted interest from both institutional investors and international research collaborators.
Recce maintains clinical operations across multiple trial sites, with regulatory engagement in Australia and the United States. The company has sought to build its clinical evidence base methodically, though investors are acutely aware that the path from clinical-stage to commercial approval is long, expensive, and uncertain.
Financial Insights
Recce Pharmaceuticals' financial profile is characteristic of a company at its stage of development:
- No meaningful commercial revenue — all funding flows from capital markets
- Sustained R&D expenditure — the primary use of cash, reflecting active clinical trial programs
- Cash runway management — a critical focus for management given the capital-intensive nature of clinical development
- Market capitalisation of ~A$133 million — implying the market assigns meaningful but not yet overwhelming probability to clinical success
The company's valuation is, at its core, a probability-weighted estimate of future royalty streams, licensing deals, or acquisition premiums contingent on positive trial data. Any unexpected clinical setback would likely trigger a sharp valuation reset.
Management Outlook
Recce's management team has consistently framed 2026 as a year of clinical data generation, with key trial readouts expected to define the company's near-term trajectory. The focus is on:
- Advancing RECCE® 327 through clinical phases with robust data packages
- Broadening the application pipeline to include wound care and systemic infection indications
- Exploring partnership and licensing opportunities with larger pharmaceutical companies to de-risk the commercialisation pathway
Management acknowledges the binary nature of clinical-stage investing and has sought to maintain investor confidence through transparent communications around trial design and progress. The appointment of experienced regulatory and clinical advisers reflects a maturing operational structure.
Price Performance
RCE trades at approximately A$0.465, a level that reflects both cautious optimism around clinical progress and the inherent uncertainty of trial outcomes. The stock has historically exhibited sharp volatility around data announcements — a pattern investors should anticipate will continue. For traders, this creates defined event-driven opportunities. For long-term investors, position sizing relative to conviction in the clinical thesis is the critical variable.
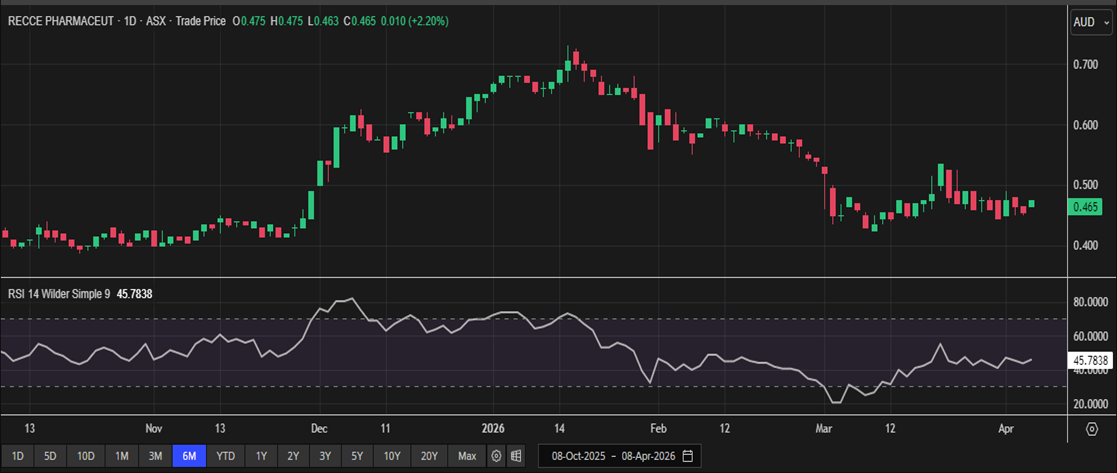
Technical Price Chart (as of 8 April,2026). Source: REFENITIV
AML3D (ASX: AL3)
Price: ~A$0.22 | Market Cap: ~A$119 million
Company Overview
AML3D is an Australian industrial technology company operating at the intersection of advanced manufacturing and additive technology. The company's proprietary Wire Additive Manufacturing (WAM®) process enables the production of large-format metal components with significantly reduced material waste and lead times compared to traditional manufacturing methods.
The company's primary focus markets are defence, oil and gas, and maritime industries — sectors that require large, complex metal components where quality, reliability, and delivery timelines are paramount. AML3D has secured contracts with both Australian and international clients, including defence and energy companies, giving its revenue base a degree of strategic defensibility.
In 2026, AML3D occupies a uniquely interesting position among ASX technology penny stocks: it is actively generating revenue. While volumes remain modest relative to the company's ambitions, the transition from pre-revenue to commercial operation is one of the most critical milestones a small technology company can achieve — and AML3D has crossed it.
Financial Insights
AML3D's financials reflect a company in active commercialisation mode:
- Early-stage revenue generation — contract revenues are growing but not yet at the scale required for profitability
- Investment in operational capacity — expanding its production facility and workforce to support pipeline growth
- Improving contract pipeline — a backlog of signed and pending contracts provides near-term revenue visibility
- Market capitalisation of ~A$119 million — pricing in successful scaling over the next 12–24 months
The company is not yet profitable, and like most scaling industrial technology companies, it is investing ahead of its revenue curve. The key financial metric to monitor is revenue growth rate relative to overhead cost structure — the point at which these curves cross will determine when, and whether, the company achieves sustainable profitability.
Management Outlook
AML3D's management team has been consistent in articulating a growth strategy anchored in defence and energy sector contract expansion, geographic diversification, and operational efficiency improvements. Key priorities for 2026 include:
- Securing additional Tier 1 defence contracts in Australia and internationally
- Expanding WAM® production capacity to reduce lead times and improve margins
- Pursuing strategic partnerships that could accelerate market penetration in the United States and Europe
Management has also indicated interest in exploring the space sector as an additional application vertical — a high-profile growth avenue that could attract incremental investor interest if converted into commercial engagements.
Price Performance
AL3 trades at approximately A$0.22, a level that reflects the market's cautious assessment of the company's scaling timeline. The stock has been range-bound in recent periods, typical of commercialisation-phase companies where near-term financials are not yet compelling but the medium-term thesis is being actively monitored. A significant contract announcement — particularly in defence or international markets — would be expected to trigger a material re-rating.
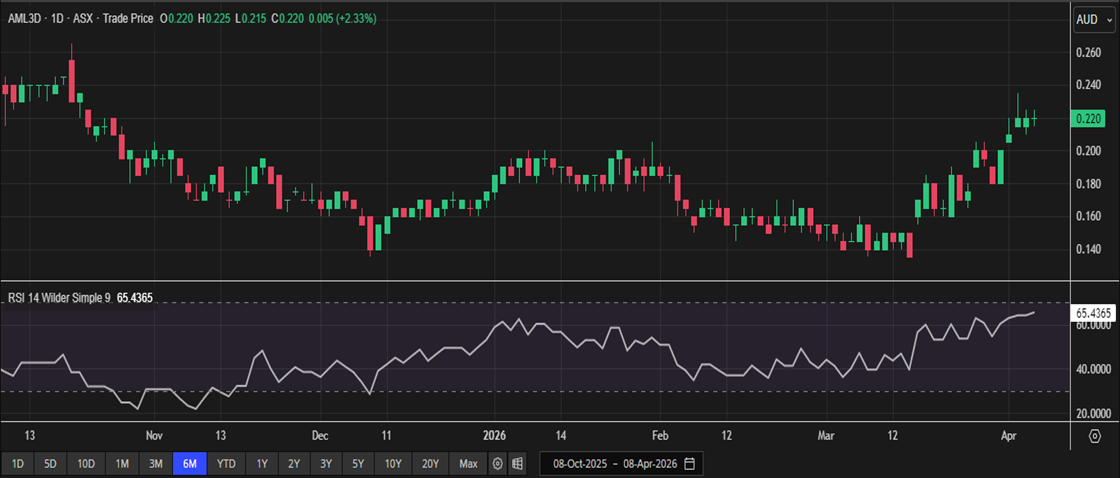
Technical Price Chart (as of 8 April,2026). Source: REFENITIV
BetMakers Technology Group (ASX: BET)
Price: ~A$0.185 | Market Cap: ~A$207 million
Company Overview
BetMakers Technology Group is a wagering technology and data services provider with a genuinely global footprint — a distinction that sets it apart from most of its ASX penny stock peers. The company supplies technology infrastructure, data analytics, and managed services to racing bodies, wagering operators, and regulators across multiple jurisdictions, including North America, Europe, and Australia.
BetMakers' business model is built on recurring revenues from long-term contracts, which provides a degree of revenue predictability uncommon among ASX small caps. The company has invested heavily in building its North American presence, recognising that the ongoing legalisation of sports wagering across US states represents a multi-year structural growth opportunity.
Financial Insights
BetMakers sits at a more advanced stage of commercial development than most of its peers in this peer group:
- Growing international revenue — particularly from North American markets following regulatory tailwinds
- Ongoing cost restructuring — management has been actively right-sizing the cost base to improve path to profitability
- Margin pressure persists — the competitive dynamics of the wagering technology space keep pricing under pressure
- Market capitalisation of ~A$207 million — reflecting a business with real revenues but unresolved profitability questions
Investors are closely watching the trajectory of EBITDA margin improvement. Revenue growth alone is no longer sufficient to command a premium valuation; the pace at which BetMakers converts top-line growth into meaningful operating leverage is the central financial question.
Management Outlook
Management's strategic agenda in 2026 is focused on three areas: deepening penetration in existing North American markets, improving unit economics across product lines, and selectively pursuing additional contract opportunities in regulated European markets. The company has moved past the early land-grab phase of international expansion and is now focused on extraction — converting its established relationships into profitable long-term revenue streams.
There is also ongoing market speculation about potential corporate activity, given BetMakers' technology stack and international customer relationships. Management has not commented on such matters, but the company's profile as a potential acquisition target is not lost on the market.
Price Performance
BET trades at approximately A$0.19, a modest valuation that reflects the market's impatience with the pace of profitability improvement. Despite having a more established revenue base than most ASX tech penny stocks, the stock has underperformed expectations over recent periods, weighed down by cost restructuring charges and competitive pressures. A clear inflection toward positive operating cash flow would likely be the most powerful catalyst for a sustained re-rating.
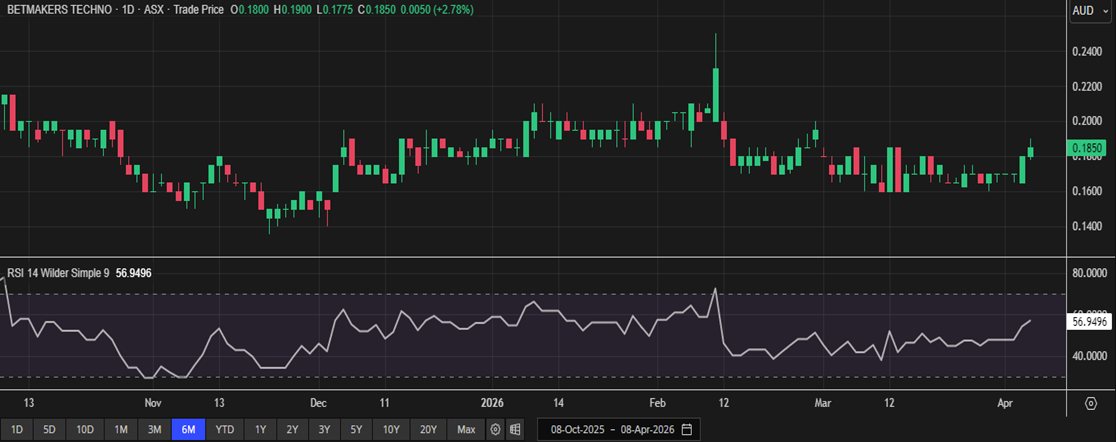
Technical Price Chart (as of 8 April,2026). Source: REFENITIV
Frequently Asked Questions (FAQs)


 Nov 11, 2026





 Please wait processing your request...