
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Wildcat Resources is advancing its Definitive Feasibility Study (DFS) for the Tabba Tabba lithium project, targeting higher throughput and improved Capital efficiency.
- The DFS incorporates lithium, tantalum, and petalite streams, expanding the project beyond its original spodumene-only scope.
- The company is progressing toward a 4.5Mtpa processing expansion with optimised mine scheduling and earlier underground development.
Wildcat Resources Limited (ASX:WC8) has delivered one of the more pronounced share price performances among emerging lithium developers, with its stock trading around A$0.60 and recording gains of approximately 271% over the past year. This strong upward trajectory reflects heightened investor interest in early-stage lithium Assets within Australia’s Pilbara region, particularly as global Demand expectations for battery materials remain structurally elevated.
However, today, WC8 share price dropped 3.28% on 18 May, during the Trading session.
Wildcat’s valuation re-rating has been closely tied to its progression from exploration-stage drilling toward feasibility-level development, particularly at its flagship Tabba Tabba Project.
The latest Definitive Feasibility Study (DFS) update adds another layer of complexity to the company’s growth narrative, shifting the project from a single-Commodity lithium focus toward a broader multi-metal development strategy.
DFS Progress and Strategic Repositioning of Tabba Tabba
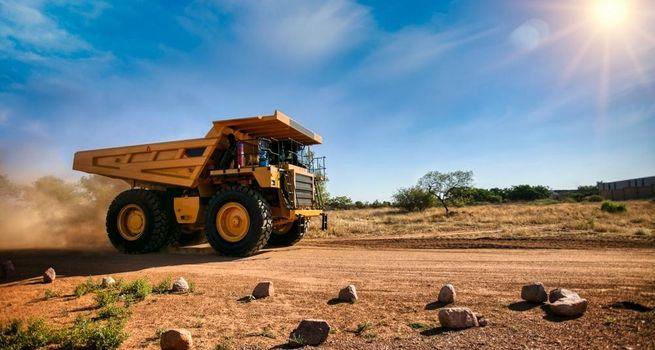
The core development in the announcement is the ongoing advancement of the DFS for the Tabba Tabba Project in Western Australia’s Pilbara region. The study is being designed not merely as a refinement of earlier feasibility work, but as a significant optimisation exercise aimed at improving both capital efficiency and long-term production scalability.
A key strategic adjustment is the proposed acceleration of Stage 2 expansion to 4.5 million tonnes per annum processing capacity. This represents a shift toward earlier-scale operations, supported by mine planning adjustments that aim to reduce pre-production strip requirements and overall capital intensity.
The DFS also incorporates a broader resource base than the earlier Preliminary Feasibility Study (PFS), which focused primarily on spodumene-bearing ore bodies. The updated study now includes additional processing streams for tantalum and petalite, materially expanding the project’s economic optionality.
This evolution signals a transition from a single-product lithium development model to a multi-product critical minerals platform, potentially enhancing long-term Revenue Diversification.
Multi-Commodity Strategy: Lithium, Tantalum, and Petalite Integration
One of the most significant structural changes in the DFS is the integration of multiple mineral streams within the processing framework. The inclusion of tantalum and petalite introduces additional revenue pathways alongside traditional spodumene concentrate production.
Tantalum, in particular, has emerged as a notable by-product opportunity. Historical drilling results from the Tabba Tabba deposit have indicated high-grade intersections, with mineralisation supporting both tantalum pentoxide and associated niobium and tin content. These results suggest that the project may contain economically meaningful secondary mineral value that was not fully captured in earlier studies.
Similarly, petalite resources from the Chewy, Han, and Hutt deposits are now being incorporated into processing design considerations. This diversification has the potential to improve overall plant utilisation and enhance the robustness of project Economics under varying lithium price scenarios.
The inclusion of these additional mineral streams reflects a broader trend in lithium project development, where developers seek to optimise resource utilisation and reduce dependency on a single commodity price cycle.
Mining and Production Optimisation Strategy
The DFS introduces a revised mine planning framework aimed at improving operational efficiency and accelerating production ramp-up. The updated schedule incorporates earlier underground development of the Luke orebody, alongside integration of the Chewy resource into the production sequence.
A key objective of the optimisation work is to bring forward higher throughput levels while maintaining manageable Capital Expenditure profiles. The original PFS outlined a staged approach to production, but the DFS suggests a more compressed development timeline, particularly for achieving higher processing capacity.
Mine scheduling work has been supported by advanced modelling tools to optimise material movement, ore stockpiling strategies, and production sequencing. This reflects an increasing emphasis on operational flexibility, particularly in response to fluctuating lithium market conditions.
Additionally, open pit development of the Han and Hutt resources is expected to proceed independently of the main Leia orebody, providing supplementary feed sources that could support earlier production diversification.
Processing Plant Design Evolution and Technical Adjustments
The DFS has introduced several key changes to the processing plant design, particularly for the spodumene circuit. A major technical decision involves the selection of a two-stage crushing circuit with closed-loop configuration, replacing the three-stage crushing approach considered in earlier studies.
This change is expected to reduce capital intensity and simplify operational complexity, while maintaining processing efficiency at the targeted 4.5Mtpa throughput level.
The expansion philosophy remains anchored in a dual-train configuration, allowing for operational flexibility during ramp-up phases and potential production modulation during periods of weaker lithium pricing.
Additional process design refinements include increased ROM ore size capacity, incorporation of ore sorting technology for high-iron material management, and enhanced comminution efficiency. These adjustments collectively aim to improve recovery rates and reduce processing bottlenecks.
Importantly, the inclusion of ore sorting technology reflects an effort to improve feed quality consistency, which can have Downstream benefits for plant performance and product quality stability.
Metallurgical Advances and Resource Confidence Building
Metallurgical testwork has progressed significantly, with large-scale sampling programs conducted across multiple ore types. The results from spodumene flotation tests have demonstrated consistent performance across different composites, supporting the robustness of the process design.
Petalite testwork is also advancing, with diagnostic studies confirming mineral distribution across key deposits. Meanwhile, tantalum processing testwork has delivered promising recovery rates, indicating potential for viable by-product production.
These metallurgical results are critical in de-risking the DFS, as they provide empirical validation for processing assumptions and recovery expectations. The completion of bulk-scale flotation tests and water chemistry optimisation studies further strengthens confidence in the technical feasibility of the project.
Environmental Approvals and Regulatory Progress
Environmental and regulatory workstreams have progressed in parallel with technical studies. Engagement with both state and federal regulatory authorities has been initiated ahead of formal application submissions under the Environmental Protection Act 1986 and the Environment Protection and Biodiversity Conservation Act 1999 frameworks.
The completion of environmental surveys and monitoring programs represents a key milestone in the approvals pathway. These datasets are essential for supporting construction and operational approvals, as well as informing closure planning requirements.
Regulatory progress remains a critical component of the project timeline, particularly given the scale and multi-commodity nature of the proposed development.
Funding Strategy and Market Interest
The company has also initiated funding discussions with a range of potential capital providers, including government agencies, banking institutions, and specialist mining finance groups. These discussions are occurring alongside ongoing engagement with potential offtake partners.
Market conditions for spodumene concentrate have been described as supportive, contributing to increased interest in the project from strategic counterparties. This external interest is particularly relevant as the DFS moves toward completion, where financing structures and offtake agreements typically become central to project execution.
The combination of multi-metal exposure, expanded production scale, and improved process efficiency may enhance the project’s appeal to a broader set of investors and industrial partners.
Conclusion
Wildcat Resources Limited is advancing a materially expanded Definitive Feasibility Study for its Tabba Tabba Project, marking a transition from a lithium-focused development into a broader critical minerals platform. The inclusion of tantalum and petalite alongside spodumene, combined with optimised mine scheduling and processing redesign, reflects a strategic shift toward scale efficiency and resource diversification.
While the project remains in development stage, the DFS evolution highlights increasing technical sophistication and a more integrated approach to resource utilisation. The outcome of this study will be pivotal in determining the project’s positioning within Australia’s emerging lithium and critical minerals landscape, particularly as global demand for battery-related materials continues to evolve.

 Nov 13, 2026
 Please wait processing your request...