
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Takeaways
- Rio Tinto has launched the sale of its Pilbara power Assets.
- KKR is among suitors preparing for the first round of offers.
- The sale is part of broader asset recycling at major resource companies.
- Implications for Rio Tinto's Balance Sheet and Shareholder returns.
- Australian infrastructure assets remain attractive to global Capital.
- Investors should watch the price achieved and the structure of the eventual deal.
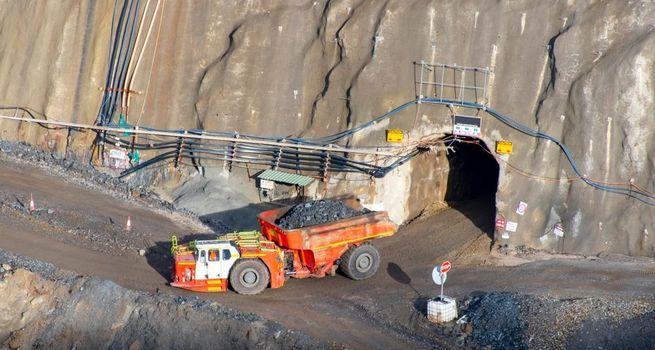
Rio Tinto (ASX:RIO) has formally launched the sale of its Pilbara power assets, with global Private Equity giant KKR among suitors preparing for the first round of offers, according to the Australian Financial Review's Street Talk column. The transaction is one of the most significant Australian infrastructure deal launches of 2026 and carries direct implications for ASX 200 investors.
By selling non-core power assets while retaining operational control of its iron ore powerhouse, Rio Tinto is following a familiar major-miner playbook: recycle capital, focus on core operations and free up balance-sheet capacity for shareholder returns or higher-priority investments.
This article unpacks what is being sold, who the likely buyers are, and what the eventual transaction could mean for Rio Tinto, the broader resource sector and Australian infrastructure investors.
What Happened
Rio Tinto has launched the selldown of its Pilbara power assets, infrastructure that supports the company's iron ore operations in Western Australia. According to AFR Street Talk, KKR is among suitors preparing for the first round of offers.
The structure of the sale is likely to involve long-term power Supply agreements that preserve Rio Tinto's operational continuity while transferring economic ownership of the underlying generation and transmission infrastructure to the buyer.
Why This Matters for ASX Investors
Rio Tinto is one of the largest companies on the ASX 200, with iron ore as its dominant Earnings driver. Any transaction that materially affects the company's balance sheet, capital allocation flexibility or Dividend capacity is therefore important to ASX investors.
A successful sale could free up capital that Rio Tinto could deploy in growth projects, balance sheet management or shareholder returns. It could also crystallise the value of an Asset Class — Pilbara power infrastructure — that is otherwise opaque to public-market investors. Conversely, a difficult sale process or a disappointing price could signal weaker infrastructure investor appetite for Australian assets.
Current Market Context
Asset recycling is a recurring theme among major Mining companies. By divesting non-core infrastructure to long-term institutional owners while retaining service contracts, miners can streamline their portfolios and improve return on capital employed. KKR and other private equity firms have been active acquirers of such assets globally.
In Australia, Pilbara infrastructure has long been seen as a strategic asset class. Long-life iron ore mines, supported by dedicated rail, port and power infrastructure, generate stable cash flows that pension funds and infrastructure investors find attractive.
Relevant Background
Rio Tinto's Pilbara iron ore operations are among the largest and most profitable mining systems in the world. The company has progressively invested in renewable energy infrastructure, including solar and battery assets, to support its decarbonisation goals and reduce reliance on diesel and gas for power generation.
The Pilbara power assets that are now being divested span generation, transmission and supporting infrastructure. The sale is expected to include both existing capacity and a pipeline of renewable projects under development. Long-term power supply agreements are likely to be embedded into the transaction.
KKR has a strong global infrastructure track record and has previously been active in Australian energy and infrastructure deals. Other likely contenders include Brookfield, Macquarie's Asset Management arm, IFM Investors, BCI and Superannuation-backed consortia.
Latest News and Recent Developments
First-round bids are reportedly being prepared, suggesting the sale process is at an early but substantive stage. Pricing expectations, deal structure and the inclusion of decarbonisation-related capex commitments will be key features of competing offers.
Broader context for the deal includes the ongoing global appetite for high-quality infrastructure, the structural Demand for renewable power and the increasing relevance of energy infrastructure to mining decarbonisation roadmaps.
Share Price and Capital Markets Sentiment
Rio Tinto investors typically welcome asset-recycling transactions that release capital without undermining operational control. The market is likely to focus on three things: the price achieved, the structure of the power supply arrangements that Rio Tinto retains and the use of proceeds.
A premium price would support Rio Tinto's balance sheet and could open the door to incremental shareholder returns. A modest price could signal weaker infrastructure appetite. The structure of the power supply contracts will determine how much economic exposure Rio Tinto retains to power costs and decarbonisation outcomes.
Risks and Uncertainties
Risks include regulatory scrutiny, native title and environmental approvals, foreign Investment review board (FIRB) considerations and broader Australian political sensitivity around critical infrastructure ownership. KKR's involvement, while signalling deep capital markets interest, may also attract political and stakeholder attention.
From Rio Tinto's perspective, key risks include locking into long-term power supply terms that may not optimise for future technology shifts, and any reputational issues around perceived loss of control over critical operational infrastructure. A failed process — for example, if first-round bids disappoint — would be a negative catalyst.
What Investors Should Watch Next
Investors should watch the AFR Street Talk and other primary sources for updates on the bidder field, expected timing of binding offers and any indicative valuation ranges. Rio Tinto's own investor communications will be the most authoritative source for the company's perspective.
Broader signposts include the use of proceeds (shareholder returns, growth capex or balance sheet repair), the structure of power supply agreements and any read-across to BHP, Fortescue or other miners considering similar divestments.
Conclusion
Rio Tinto's Pilbara power asset sale is one of the most significant Australian infrastructure transactions to launch in 2026. With KKR among early suitors and a structurally attractive backdrop for power infrastructure, the process has the potential to crystallise meaningful value for Rio Tinto and to set a benchmark for similar transactions across the resource sector. ASX investors should treat each procedural update as a potentially market-moving event.


 Nov 13, 2026




 Please wait processing your request...