
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Pilbara Minerals shares advanced $0.300 or 5.281% to $5.980 on 24 April 2026, with 3,346,213 shares traded and a market capitalisation of $19.07 billion, as the company released a comprehensive Q3 FY26 quarterly activities report that beat expectations across production, revenue, cash margin, and balance sheet metrics simultaneously.
- Record quarterly spodumene concentrate production of 232.4kt was achieved at the Pilgangoora Operation, up 12% on the prior quarter and 25% year-on-year, driving revenue of $567 million (up 52% quarter-on-quarter), a cash margin from operations of $461 million (up 178%), and a closing cash balance of $1.455 billion (up 52%).
- Post quarter, PLS completed the issuance of US$600 million in 6.875% senior unsecured notes due 2031 — the company’s debut in the international bond market — and announced a series of milestones at the Mid-Stream Demonstration Plant including ARENA grant funding of up to $38.1 million and commencement of commissioning.
Pilbara Minerals Limited (ASX:PLS) recorded an encouraging session on 24 April 2026, with shares trading at $5.980, up $0.300 or 5.281% from the prior session. Volume of 3,346,213 shares was well above average daily trading levels, reflecting broad-based institutional and retail participation in response to the quarterly report release. The tight bid-offer spread of $5.980 to $5.990 indicated a well-supported and liquid market. With a market capitalisation of $19.07 billion, PLS is one of the largest lithium producers listed globally and its share price response on 24 April signalled that the market interpreted the report not merely as a strong operational quarter but as a potential inflection point in the lithium market pricing cycle, following an average realised price increase of 61% quarter-on-quarter.
Record Production: 232.4kt Sets a New Quarterly Benchmark
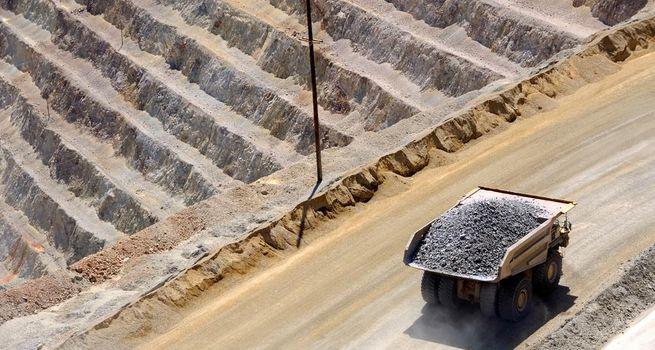
The standout operational result of the March 2026 quarter was spodumene concentrate production of 232.4kt, a record for the Pilgangoora Operation and a 12% improvement on the December 2025 quarter. The performance was driven by improved plant reliability, increased processing run time, and consistently high lithium recovery of approximately 75% across the period. Total material mined rose to 9.9 million wet metric tonnes, up from 8.1 million in the prior quarter, with waste stripping activity elevated as the operation positions for the planned restart of the Ngungaju Plant. Ore sorter performance remained strong despite elevated contact ore in the feed stream, providing operational flexibility in managing variability in feed quality without compromising throughput or recovery outcomes.
On a year-to-date FY26 basis, production of 665.2kt is 25% above the comparable period in FY25, demonstrating the operational maturity and consistency that the Pilgangoora Operation has achieved. The full-year FY26 guidance has been reaffirmed across all metrics, providing investors with confidence that management retains visibility over the full-year production trajectory despite some cost headwinds expected in the June quarter associated with the Ngungaju Plant restart preparations.
Revenue and Cash Margin: Pricing Rebound Transforms the Financial Profile
The financial transformation of the quarter relative to the prior period was primarily driven by the 61% increase in the average estimated realised price to US$1,867 per tonne (CIF China, approximately SC5.2 basis), equivalent to US$2,155 per tonne on an SC6 basis. The prior quarter average price of US$1,161 per tonne had constrained margins significantly, and the rebound in pricing — supported in part by the execution of a multi-year offtake agreement with Canmax Technologies including a US$100 million unsecured prepayment and a floor price of US$1,000 per tonne (SC6 basis) — drove a near-tripling of the cash margin from operations to $461 million.
Revenue for the quarter was $567 million, up 52% on the prior quarter’s $373 million. The unit operating cost on a FOB basis decreased 11% to $520 per tonne (US$362 per tonne), driven by higher production volumes and the benefit of higher capitalised waste stripping. On a year-to-date basis, the FOB unit cost of $550 per tonne remains on track to meet full-year guidance. Management cautioned that unit costs are expected to rise in the June 2026 quarter as Ngungaju Plant restart-related costs are expensed ahead of production contributions from that facility.
Balance Sheet: $1.455 Billion Cash and US$600M Bond Debut
PLS closed the March 2026 quarter with a cash balance of $1.455 billion, a 52% increase from the $954 million at the end of December 2025. This uplift was driven by the strong operating cash margin and the receipt of the US$100 million Canmax offtake prepayment. Cash margin from operations less mine development and sustaining capital was $394 million, with capital expenditure of $71 million on a cash basis comprising mine development of $52 million, infrastructure of $28 million, and sustaining capital of $16 million.
Subsequent to quarter end, PLS completed the offering of US$600 million in 6.875% senior unsecured notes due 2031, its debut issuance in the international capital markets. A portion of the proceeds refinanced the $375 million drawn balance on the revolving credit facility, which was simultaneously reduced in size from $1 billion to $500 million. The notes offering represents a meaningful financing maturation milestone, aligning PLS’ funding sources with the scale and long-term nature of its operations while providing additional capital allocation flexibility.
Ngungaju Plant Restart and Growth Portfolio
The PLS Board approved the restart of the Ngungaju Plant for early July 2026, with a ramp to steady-state production targeted through the September 2026 quarter. Recruitment is underway and key operational staff are already relocating to site. The P2000 Feasibility Study, targeting expansion of concentrate production capacity to approximately 2.0 Mtpa, continues to progress with outcomes expected in the December 2026 quarter. Management is also evaluating whether pre-FID capital expenditure in FY27, including detailed engineering and procurement of long-lead items, could expedite the project timeline.
In chemicals, the Mid-Stream Demonstration Plant achieved a series of milestones post-quarter: completion of the JV restructure with Calix, securing up to $38.1 million in ARENA government grant funding, execution of an offtake agreement with Ronbay for lithium phosphate, and commencement of commissioning with first product expected in the September 2026 quarter. In South Korea, the POSCO Pilbara Lithium Solution joint venture restarted both trains in the March quarter following idling in December 2025, with Train 1 and Train 2 producing battery-grade lithium hydroxide at quality rates of 99% and 98% respectively.
Conclusion
Pilbara Minerals’ 5.28% share price gain on volume of 3.35 million shares on 24 April 2026 was a broad and decisive market response to a quarterly report that delivered across every key metric: record production, a near-tripling of cash margin, a 52% increase in cash balance, a transformational bond market debut, and a series of downstream and growth milestones. With full-year FY26 guidance maintained, the Ngungaju restart imminent, the P2000 feasibility study progressing, and the Mid-Stream Demonstration Plant commissioning underway, PLS enters the final quarter of FY26 carrying the strongest combination of operational, financial, and strategic momentum it has held in several years.


 Nov 13, 2026





 Please wait processing your request...