
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Yangibana: Advanced NdPr-focused project in WA, feasibility complete, financing key bottleneck.
- Targets mid-tier producer role, leveraging EV demand for offtake.
- Re-rating on finance close, construction start.
Hastings Technology Metals (ASX:HAS) occupies a specific and important position in the ASX rare earth landscape: it is neither an early-stage explorer nor an established producer, but a late-development-stage company working through the most capital-intensive and execution-sensitive phase of the project lifecycle. The Yangibana Project in Western Australia is one of the country's most advanced rare earth developments, with significant feasibility work completed and a clear technical pathway to NdPr oxide production.
The investment case hinges on Hastings' ability to navigate project financing — the most commonly cited reason that development-stage rare earth projects fail to reach production — and execute construction within cost and schedule parameters.
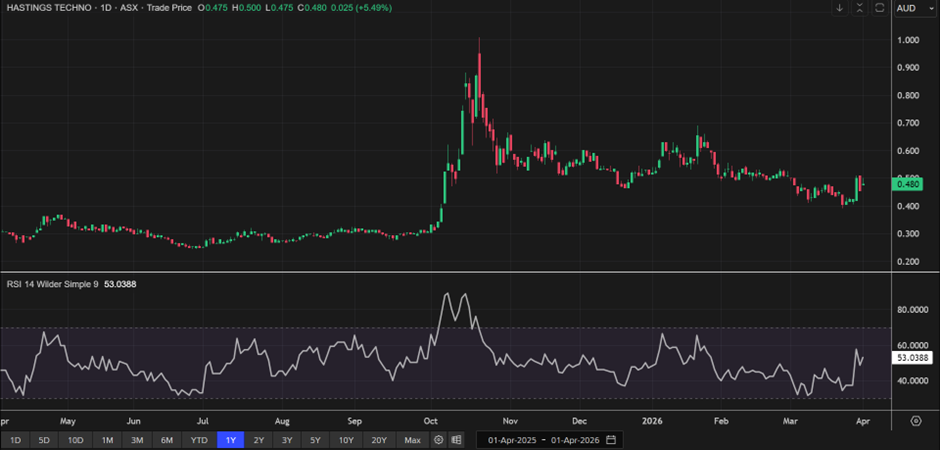
Hastings Technology Metals gained 5.494% to $0.480, volume 398,244 shares.
Bid/offer at $0.475-$0.480 signals progress toward Yangibana financing and construction.
The $100.95M market cap highlights late-stage NdPr developer upside.
Source: EODHD/Others
- Business Model & Strategic Positioning
Hastings' stated strategic objective is to become a reliable mid-tier supplier of NdPr oxide, occupying the commercial space between Lynas — the globally dominant ex-China producer — and smaller developers yet to reach production. This positioning is deliberate and commercially rational.
Western OEMs and magnet manufacturers are actively seeking to diversify their NdPr supply beyond Lynas and Chinese sources. A second credible, operating, Western-aligned producer would command strong commercial interest from these customers. If Hastings can successfully reach production, the demand environment is arguably the most supportive in the history of the sector.
- Core Asset: Yangibana Project, Western Australia
The Yangibana Project is located in the Gascoyne region of Western Australia and represents one of the most advanced NdPr-focused developments in the country.
Key project characteristics:
- Explicit focus on NdPr production — the highest-value fraction of the rare earth oxide basket — improving project economics relative to TREO-weighted peers
- Long mine life with a well-defined resource base supporting multi-year production planning
- Advanced feasibility studies completed, providing a foundation for financing discussions
- Western Australian jurisdiction — one of the world's premier mining regulatory environments with established infrastructure and skilled workforce access
The NdPr focus is a deliberate product strategy. By targeting the magnet rare earth fraction specifically, Yangibana's revenue profile is more directly linked to EV and renewable energy demand than deposits with a broader, less valuable rare earth basket.
- Development Stage & Financing
Hastings is at the stage where technical risk has been substantially reduced but financial risk is at its peak. The company has:
- Completed significant feasibility and engineering work
- Defined a clear technical pathway to production
- Initiated discussions with potential project financiers and strategic partners
The primary near-term challenge is securing the financing package required to commence construction. This is the bottleneck that defines the Hastings investment thesis — the project is technically ready, but capital market conditions, NdPr pricing, and lender appetite must align to close the financing gap.
- Financial Profile
Hastings is pre-revenue, with expenditure focused on:
- Ongoing project development and engineering
- Financing and partnership discussions
- Corporate overhead
The balance sheet position and the company's ability to manage its cash runway while financing discussions progress is a key variable for existing and prospective investors. Extended financing timelines increase dilution risk through additional equity issuance.
- Investment Catalysts
|
Catalyst |
Expected Impact |
|
Project financing announcement |
Very High — primary re-rating event |
|
Construction commencement |
High — confirms execution pathway |
|
Offtake agreement with Western OEM |
High — validates commercial demand |
|
First production milestone |
Very High — transition to revenue-generating entity |
|
NdPr price appreciation |
High — improves project economics and lender confidence |
- Risk Assessment
|
Risk Factor |
Description |
Severity |
|
Financing Risk |
Inability to close project finance on acceptable terms |
High |
|
Execution Risk |
Cost overruns or delays during construction |
High |
|
NdPr Price Sensitivity |
Project economics and lender appetite tied to NdPr pricing |
High |
|
Dilution Risk |
Extended pre-production period may require equity raises |
Moderate |
|
Competitive Risk |
Lynas and other producers expanding simultaneously |
Low–Moderate |
- Bull & Bear Case
Bull Case: Hastings secures a project finance package — potentially including government concessional funding and strategic offtake-linked financing — and commences construction within a defined timeline. NdPr prices remain supportive, improving project economics. First production is achieved in line with guidance, and Hastings transitions to a mid-tier producer multiple, delivering a significant re-rating from the current development-stage discount.
Bear Case: Project financing proves elusive as lenders require higher NdPr price assumptions or more substantial offtake security than Hastings can provide in the near term. Construction is deferred, equity raises dilute existing holders, and the development-stage discount persists. A deterioration in NdPr pricing further weakens the financing case.
- Investment Conclusion
Hastings is a technically credible, strategically well-positioned developer at the most difficult stage of the project lifecycle. The Yangibana Project is real, advanced, and commercially relevant. The NdPr demand environment supports the long-term case. But the near-term investment outcome is almost entirely a function of financing execution — a variable that depends on lender appetite, NdPr pricing, and strategic partner engagement as much as on management quality.
For investors who believe the financing will close and construction will proceed, Hastings offers a meaningful re-rating opportunity as the market transitions from a development discount to a production multiple. For those uncertain about financing timelines, the risk profile may be better addressed through more advanced peers.
Best suited for: Growth investors comfortable with late-stage development risk, with particular conviction in the NdPr demand outlook and Hastings' financing pathway.


 Nov 13, 2026





 Please wait processing your request...