
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
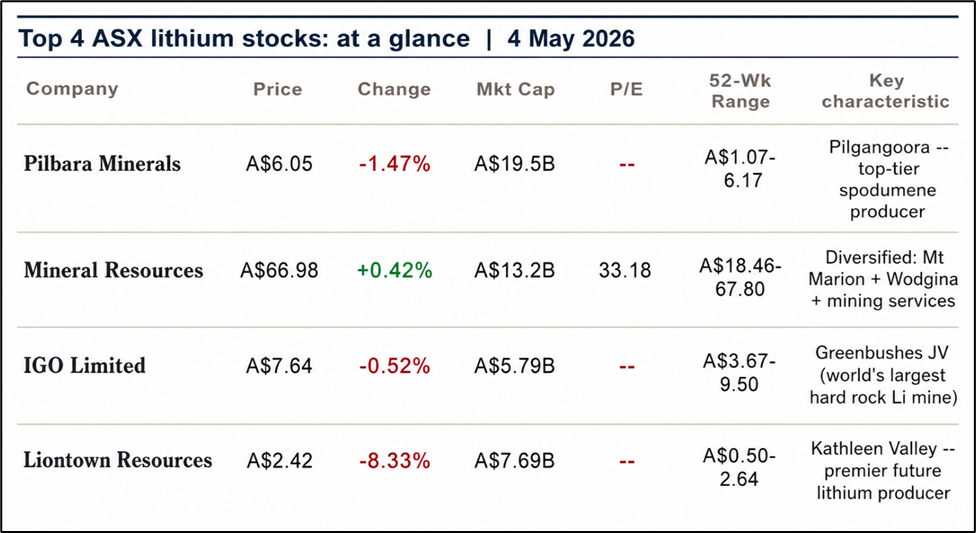
The lithium cycle turned hard. Now it's turning back. Four ASX-listed lithium stocks including Pilbara Minerals (ASX:PLS), Mineral Resources (ASX:MIN), IGO (ASX:IGO) and Liontown (ASX:LTR) analysed for battery metals investors in 2026.
The world's lithium: why Australia matters and what these four companies represent
Australia is the world's largest hard rock lithium producer, mining spodumene concentrate from the Pilbara and South-West regions of Western Australia. These four companies -- Pilbara Minerals, Mineral Resources, IGO and Liontown -- collectively represent the full spectrum of the lithium investment landscape: established high-volume producer, diversified miner with lithium exposure, world-class joint-venture partner, and emerging developer turning into producer.
Lithium's investment story in 2026 is one of price recovery from a severe trough. The lithium carbonate price peaked above $80,000 per tonne in late 2022, collapsed to below $10,000 per tonne through 2024, and has been recovering as EV demand growth reasserts itself and oversupply concerns moderate. Australian spodumene concentrate prices followed a similar pattern. The four companies on this list all experienced dramatic share price declines from their 2022-2023 highs -- PLS from above A$5 to its 52-week low of A$1.07, LTR from above A$3 to its 52-week low of A$0.50 -- and are now rebuilding as the lithium cycle turns.
Australia's geological endowment in hard rock lithium is unmatched. The Pilgangoora, Greenbushes and Wodgina deposits are among the largest and highest-grade hard rock lithium deposits in the world. That endowment is owned and operated by the four companies on this list, making the Australian lithium sector one of the most concentrated and significant battery materials investment opportunities globally.
|
|
Business Analysis |
What Pilbara Minerals does: Pilbara Minerals Limited is Australia's largest pure-play lithium company and one of the world's largest producers of spodumene concentrate. The company owns and operates 100 per cent of the Pilgangoora lithium-tantalite project in the Pilbara region of Western Australia -- one of the world's largest and highest-grade hard rock lithium deposits. Pilgangoora produces lithium spodumene concentrate (SC5.5 and SC6.0 grade) which is sold to chemical converters, primarily in China, for processing into battery-grade lithium carbonate and lithium hydroxide.
Pilgangoora -- the asset: The Pilgangoora deposit sits approximately 120 kilometres south of Port Hedland in Western Australia's Pilbara region. The operation comprises the Pilgan Plant (the original processing facility) and the Ngungaju Plant (a second facility acquired from Altura Mining in 2021), creating a combined processing capacity that can produce several hundred thousand dry metric tonnes of spodumene concentrate per year. Pilbara Minerals has been the fastest-growing spodumene producer globally, expanding production capacity multiple times since first production in 2018.
Battery material exchange -- the BMX: Pilbara Minerals operates the Battery Material Exchange (BMX) -- an innovative online auction platform for spodumene concentrate. Rather than selling all production via fixed offtake agreements at negotiated prices, Pilbara uses the BMX to discover spot market prices for a portion of its production. BMX auction results have become a closely watched barometer for real-time spodumene market sentiment, providing price transparency unprecedented in the historically opaque battery materials market.
P680 and P1000 expansion projects: Pilbara Minerals has been executing a staged expansion of Pilgangoora's production capacity. Project P680 targeted 680,000 dry metric tonnes per year of spodumene concentrate production; the subsequent P1000 stage targets one million tonnes per year. These expansions are funded from the strong cash flows generated during the 2022-2023 lithium price boom and represent a deliberate strategy to increase volume ahead of the next price upcycle.
POSCO joint venture -- downstream lithium: Pilbara Minerals holds a 21.25 per cent interest in the POSCO-Pilbara Lithium Solution (P2LS) joint venture in South Korea with POSCO Holdings. The JV processes Pilgangoora spodumene concentrate into battery-grade lithium hydroxide in South Korea, providing Pilbara with downstream exposure beyond the raw spodumene concentrate business. This positions Pilbara along the full battery supply chain and provides diversified revenue in the lithium chemicals segment.
|
|
Financial Analysis |
Pilbara Minerals' financial profile reflects the extreme cyclicality of lithium prices. In FY2023, the company generated record revenue and net profit as spodumene prices reached all-time highs -- cash and liquid assets exceeded A$3 billion. In FY2024 and into 2025, as lithium prices collapsed, revenue and profit fell sharply.
The company's strong balance sheet -- built during the windfall years of 2022-2023 -- provides the financial resilience to withstand the current lower-price environment. Pilbara has been funding its P680 and P1000 expansion projects from this accumulated cash rather than equity capital, which is strategically sound: building volume capacity when costs are lower and capital markets are less receptive, positioning for higher volumes when prices recover.
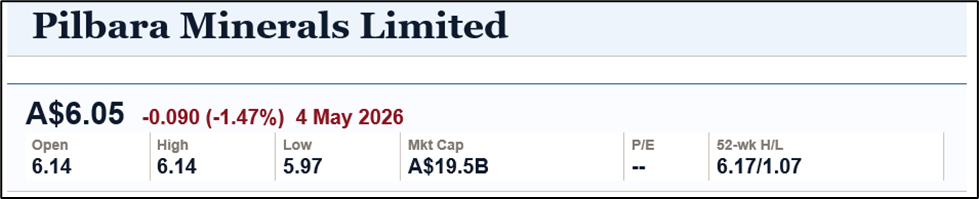
The 52-week range of A$1.07 to A$6.17 is among the widest on the ASX in percentage terms -- a 477 per cent range from low to high. The current A$6.05 price, near the 52-week high, indicates the market has already substantially re-rated PLS from its trough, pricing in a significant portion of the anticipated lithium price recovery. The -1.47 per cent decline on 4 May 2026 from an open of A$6.14 is modest daily volatility relative to the stock's historical range.
|
|
Price Performance |
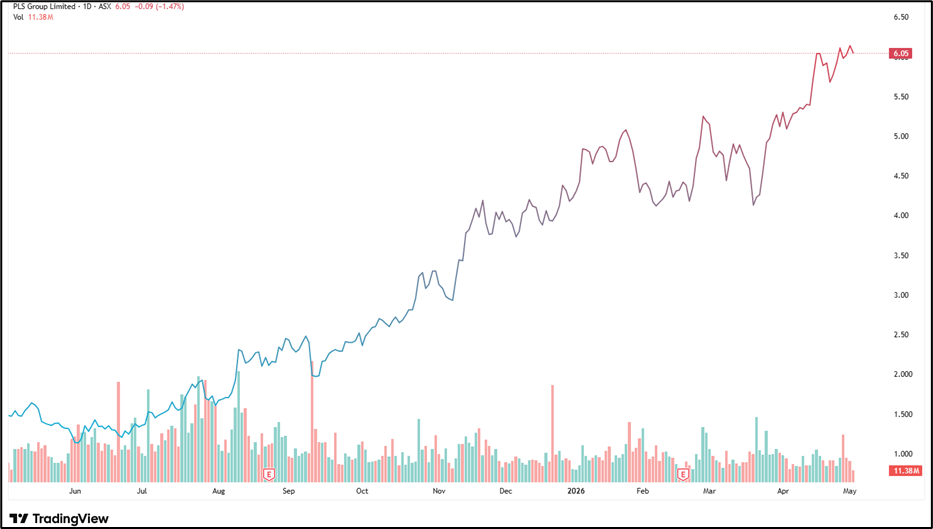
Pilbara's price chart tells the lithium cycle story in a single visual. From a 52-week low of A$1.07 to the current A$6.05 -- a recovery of approximately 466 per cent -- the stock has been driven by a combination of lithium price recovery optimism, the P1000 expansion progress, and the BMX auction data showing improved spot prices. The 52-week high of A$6.17 is very close to the current price, indicating the stock is testing the top of its recent range.
|
|
Valuation and Risks |
Pilbara Minerals is primarily valued on a price/net asset value basis, with NAV driven by the assumed long-term lithium price applied to Pilgangoora's reserve base. At lower assumed lithium prices ($10,000-12,000/t spodumene), the NAV is modest; at mid-cycle assumed prices ($20,000-25,000/t), the NAV is substantially higher. The current A$6.05 share price implies the market is pricing in a significant spodumene price recovery from recent lows.
Key risks: Lithium price is the overwhelmingly dominant risk -- any sustained weakness in spodumene or lithium carbonate prices directly reduces earnings and NAV. Chinese demand for EVs and energy storage is the primary demand driver, creating geopolitical and macroeconomic sensitivity. Processing expansion execution risk (P1000 ramp-up). Competition from new low-cost lithium sources, particularly South American brine operations and Indonesian laterite projects, could cap the upside in the next price cycle.
|
|
Outlook |
Pilbara Minerals is the most direct way to access the lithium price cycle from the ASX. When spodumene prices recover -- driven by accelerating EV adoption, grid-scale battery storage deployment and the structural undersupply that follows the current investment drought -- Pilbara's expanded production base will be available to capture maximum volume at improved prices. The P1000 expansion positions it as the highest-volume pure-play hard rock lithium producer in the world.
|
|
FAQs -- Pilbara Minerals |
Q: What is spodumene concentrate?
A: Hard rock lithium ore that has been processed into a concentrated form (typically SC5.5 or SC6.0, meaning 5.5-6.0% lithium oxide content). It is the primary product from hard rock lithium mines like Pilgangoora and is sold to chemical converters who process it into battery-grade lithium carbonate or lithium hydroxide. [Source: PLS Annual Report FY2024]
Q: What is the BMX?
A: The Battery Material Exchange -- Pilbara Minerals' online auction platform for selling spodumene concentrate. BMX auction results are watched globally as a real-time indicator of spodumene spot prices. [Source: PLS ASX announcements]
Q: Why does PLS have no P/E ratio?
A: In lower lithium price environments, Pilbara's earnings may be minimal or negative, making the P/E ratio not meaningful. This does not indicate financial distress -- the company had A$3B+ cash at the peak cycle.
Q: Why is PLS's 52-week range so wide (A$1.07-6.17)?
A: Lithium stocks are among the most volatile on the ASX because lithium prices are extremely cyclical. The 52-week range reflects the trough of the lithium downturn (A$1.07) and the subsequent recovery as prices improved (A$6.17).
|
|
Business Analysis |
What Mineral Resources does: Mineral Resources Limited is a diversified Australian miner and mining services company with major lithium assets alongside iron ore and mining services operations. The company was founded by executive chairman Chris Ellison and has grown from a mining services provider into a significant commodity producer through a series of acquisitions and developments. MinRes's lithium business encompasses two of Australia's largest hard rock lithium operations: Mt Marion and Wodgina.
Mt Marion -- the joint venture: Mt Marion is one of the world's largest hard rock lithium deposits, located approximately 40 kilometres south of Kalgoorlie in Western Australia. MinRes holds a 50 per cent interest in Mt Marion, with the balance held by Ganfeng Lithium (China's largest lithium producer). Mt Marion produces spodumene concentrate from its open-cut and underground operations, processing ore through the on-site Dense Media Separation (DMS) plant. Production has been increasing through successive capacity expansion programmes.
Wodgina -- the world-class asset: The Wodgina lithium project in the Pilbara, operated by MARBL (a 50:50 joint venture between MinRes and Albemarle, the world's largest lithium producer), is one of the world's largest hard rock lithium deposits by resource size. Wodgina was placed on care and maintenance in 2019 when lithium prices fell, restarted in 2022 as prices surged, and has been progressively increasing production. Albemarle's involvement provides deep technical and marketing expertise in the global lithium supply chain.
Mining services -- the foundation: Before its transformation into a commodity producer, MinRes built one of Australia's largest and most profitable mining services businesses. The services division -- providing crushing, processing and infrastructure services to third-party miners -- generates recurring, contract-based revenue that provides earnings diversification independent of commodity prices. This services base is a material differentiator from pure-play lithium companies.
Iron ore: MinRes also operates iron ore operations in the Pilbara, shipping direct-shipping ore through its Onslow Iron infrastructure. The company's iron ore business adds commodity diversification to the lithium-exposed portfolio. The Onslow Iron project represented a significant capital commitment and has added material tonnage to MinRes's production profile.
|
|
Financial Analysis |
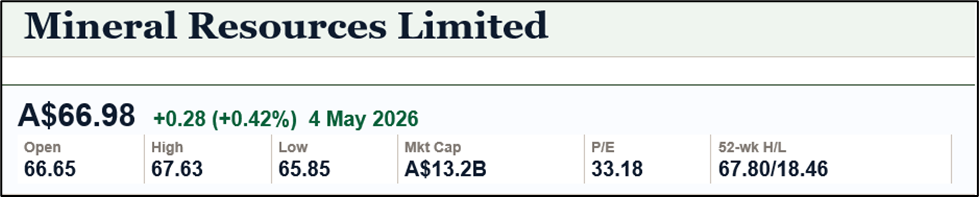
MinRes presents a complex financial profile because it operates across multiple commodity and services segments with distinct economics. The P/E ratio of 33.18 -- the only positive P/E among the four stocks -- reflects the earnings contribution from mining services and iron ore that supports profitability even when lithium prices are below cost. This diversification is MinRes's key financial differentiator from Pilbara, IGO and Liontown.
MinRes has been a significant capital deployer in recent years -- the Onslow Iron project and ongoing lithium expansions have absorbed substantial capital. The company's balance sheet carries meaningful debt associated with these investments. The higher interest cost environment of 2024-2025 has increased debt service costs, which in combination with lower lithium prices has put pressure on earnings relative to the company's peak years.
The 52-week range of A$18.46 to A$67.80 for a stock currently trading at A$66.98 illustrates the dramatic recovery MinRes has experienced from its recent lows. The stock was as low as A$18.46 within the past 52 weeks and has recovered to near its 52-week high -- reflecting both broader lithium sector recovery and specific MinRes-related developments including the resolution of governance concerns raised in FY2024.
|
|
Price Performance |
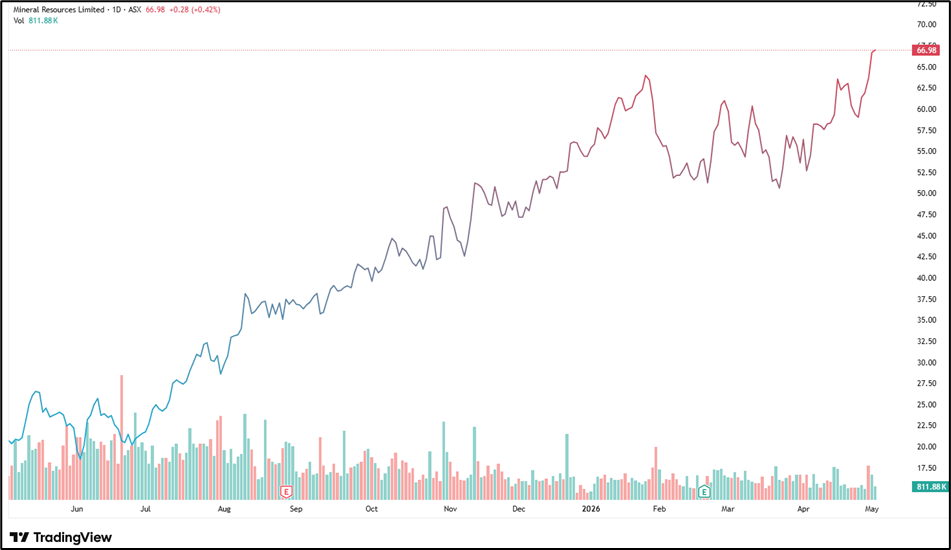
MinRes's price performance has been one of the most dramatic on the ASX over the past 52 weeks -- a move from A$18.46 to A$67.80 (a 267 per cent rally) followed by consolidation near the high. The +0.42 per cent positive close on 4 May 2026 (from A$66.65 open to A$66.98 close, with an intraday high of A$67.63) indicates positive momentum. The 52-week high of A$67.80 is the primary near-term technical resistance level.
The extraordinary 52-week range reflects multiple factors: the general lithium sector recovery, MinRes's specific governance and management issues that temporarily depressed the share price to A$18 levels, and the subsequent stabilisation and recovery as those issues resolved. Investors entering at current A$66.98 face a very different risk-return calculation from those who entered at A$18.
|
|
Valuation and Risks |
At P/E 33.18 and A$66.98, MinRes trades at a premium that reflects market anticipation of earnings recovery as lithium prices improve, mining services revenue growth, and full-ramp Onslow Iron contributions. The services business provides a floor valuation that pure-play lithium companies lack.
Key risks: Lithium price risk (as for all four stocks). Debt: MinRes carries material debt from Onslow Iron and lithium expansion capital; higher interest rates increase service costs. Governance risk: the company experienced significant governance scrutiny in FY2024 related to executive conduct; investor confidence in corporate governance remains an ongoing consideration. Iron ore price risk (additional commodity exposure). Key-person risk: Chris Ellison's central role in MinRes's strategy and culture is a material key-person dependency.
|
|
Outlook |
MinRes's outlook benefits from the same lithium price recovery tailwind as Pilbara Minerals, plus the additional levers of mining services revenue growth and Onslow Iron production contribution. If lithium prices recover materially in the second half of 2026, MinRes has significant operational leverage through both Mt Marion and Wodgina. The diversification of earnings across services and iron ore provides greater resilience to a delayed lithium recovery than pure-play peers.
|
|
FAQs -- Mineral Resources |
Q: What is Wodgina?
A: One of the world's largest hard rock lithium deposits by resource size, located in the Pilbara region of WA. Operated by MARBL -- a 50:50 joint venture between MinRes and Albemarle (world's largest lithium producer). Currently producing spodumene concentrate. [Source: MIN Annual Report FY2024]
Q: Why does MinRes have a positive P/E when the others don't?
A: MinRes has a diversified earnings base -- mining services and iron ore contribute alongside lithium. Even when lithium margins are low, the services business generates reliable earnings. Pure-play lithium companies (PLS, IGO lithium, LTR) are loss-making or marginal at current prices. [Source: MIN Annual Report FY2024]
Q: How does MinRes differ from Pilbara Minerals?
A: MinRes is diversified: lithium (Mt Marion JV, Wodgina JV) plus mining services plus iron ore. PLS is a pure-play spodumene producer at Pilgangoora. MinRes offers lower lithium leverage but more earnings resilience; PLS offers maximum lithium price leverage. [Source: Company annual reports]
Q: What were the governance issues at MinRes in FY2024?
A: MinRes disclosed in FY2024 that Executive Chairman Chris Ellison had personal financial dealings that were investigated under the company's related party policies. The board's response and subsequent management changes affected investor confidence and contributed to the share price decline to A$18. The company has since undertaken governance reforms. [Source: MIN ASX announcements FY2024]
|
|
Business Analysis |
What IGO does: IGO Limited is an ASX-listed battery minerals and gold company whose primary lithium exposure comes through its 24.99 per cent interest in Tianqi Lithium Energy Australia (TLEA) -- the joint venture that holds a 51 per cent stake in the Greenbushes lithium mine, the world's largest hard rock lithium operation. IGO also holds the suspended Nova-Bollinger nickel-copper-cobalt mine in the Fraser Range and exploration assets across Australia.
Greenbushes -- the world's largest hard rock lithium mine: The Greenbushes lithium mine in the South-West of Western Australia is the most important hard rock lithium operation on earth. Operated by Talison Lithium (a TLEA company), Greenbushes has been producing lithium for over 30 years and holds the world's highest-grade and largest lithium reserves. TLEA holds 51 per cent of Talison; the remaining 49 per cent is held by Albemarle. Through its 24.99 per cent stake in TLEA, IGO holds an effective economic interest of approximately 12.7 per cent in Greenbushes' production.
TLEA -- the ownership structure: Tianqi Lithium Energy Australia (TLEA) is itself a joint venture -- IGO holds 24.99 per cent, Tianqi Lithium Corporation (the Chinese lithium major) holds 75.01 per cent. This structure means IGO benefits from Greenbushes' production economics as a minority partner in a JV controlled by Tianqi, which in turn controls 51 per cent of Talison (which operates Greenbushes). The layered ownership structure means IGO's economics from Greenbushes are defined by the TLEA shareholders' agreement.
Nova-Bollinger suspended: IGO's Nova-Bollinger nickel-copper-cobalt sulphide mine in the Fraser Range was suspended in February 2025 following the collapse in nickel prices. Nova was a significant earnings contributor during its operational period. Its suspension -- alongside Greenbushes operating in a lower-price lithium environment -- has removed both major operating profit sources from IGO's current earnings, explaining the absence of a P/E ratio.
Kwinana lithium hydroxide refinery: IGO's 24.99 per cent interest in TLEA includes exposure to the Kwinana lithium hydroxide refinery in Western Australia -- the first lithium hydroxide refinery in Australia, processing Greenbushes spodumene into battery-grade lithium hydroxide. The Kwinana refinery has experienced ramp-up challenges but represents a downstream processing capability that adds value beyond raw spodumene concentrate.
|
|
Financial Analysis |
IGO's financial position is unusual among the four: it has no current operating earnings from its two key assets (Greenbushes earnings are impacted by lower lithium prices and the TLEA financial structure; Nova is suspended), yet it has a strong balance sheet with substantial cash and no requirement for near-term capital. The P/E ratio of '--' reflects current period earnings weakness, not financial distress.
The TLEA joint venture distributes earnings to IGO based on Greenbushes' profitability. When lithium prices were high, TLEA distributed substantial cash to IGO -- the company accumulated significant cash reserves during FY2022-FY2023. At current lower lithium prices, TLEA distributions are reduced. The strength of IGO's balance sheet provides it with strategic flexibility to invest in new opportunities while waiting for the lithium cycle to improve.
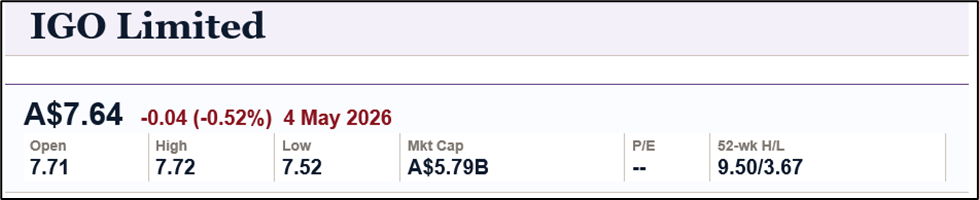
The 52-week range of A$3.67 to A$9.50 for a stock at A$7.64 shows IGO has recovered substantially from its lows but remains well below its highs. The -0.52 per cent move on 4 May 2026 from an open of A$7.71 is modest. The stock is in the upper half of its 52-week range, reflecting lithium sector recovery sentiment rather than current earnings delivery.
|
|
Price Performance |
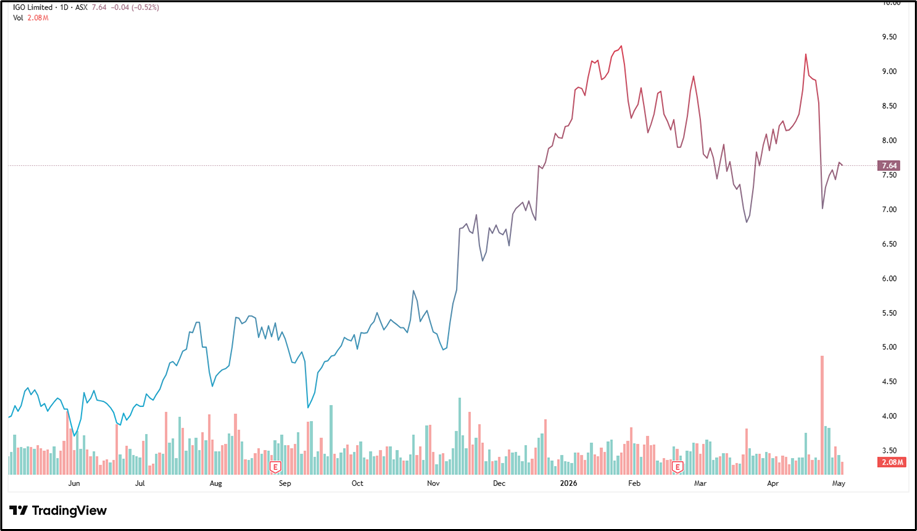
IGO's price performance mirrors the broader lithium sector: a dramatic decline from highs as lithium prices collapsed (the 52-week low of A$3.67 is testament to this) and a subsequent recovery as sentiment improved. The current A$7.64, while well above the low, is below the 52-week high of A$9.50 -- the stock has not fully recovered to prior highs, reflecting the ongoing uncertainty about Nova-Bollinger restart and TLEA distribution levels at current lithium prices.
|
|
Valuation and Risks |
IGO is valued primarily on the NPV of its Greenbushes economic interest (via TLEA), with Nova-Bollinger valued as a restart option contingent on nickel price recovery. At long-run assumed lithium prices, Greenbushes' reserve quality and low production cost make IGO's TLEA stake a high-quality asset. The valuation debate is the appropriate long-term lithium price assumption and the discount for the layered JV ownership structure that limits IGO's direct control.
Key risks: Lithium price is the primary risk for the TLEA/Greenbushes value. Nickel price for Nova-Bollinger restart. The JV ownership structure (minority stake in TLEA, which itself controls Greenbushes via Talison) means IGO has limited operational control. Kwinana refinery ramp-up risk -- the refinery has not yet operated at design capacity. Titanqi Lithium's financial health affects TLEA governance and strategic decisions.
|
|
Outlook |
IGO's outlook is tied to two recovery stories running in parallel: the lithium price recovery (which benefits Greenbushes earnings and TLEA distributions) and the nickel price recovery (which determines the Nova-Bollinger restart economics). The company has the balance sheet to be patient on both. Any Nova restart announcement or material lithium price improvement would be significant positive catalysts.
|
|
FAQs -- IGO Limited |
Q: How does IGO get exposure to Greenbushes?
A: IGO owns 24.99% of TLEA (Tianqi Lithium Energy Australia), which holds 51% of Talison Lithium, which operates Greenbushes. This gives IGO an effective economic interest of approximately 12.7% in Greenbushes production economics. [Source: IGO Annual Report FY2024]
Q: What is Greenbushes and why is it significant?
A: The world's largest and highest-grade hard rock lithium mine, located near Bridgetown in WA's South-West. Has been producing lithium since 1983. Its reserves and grade are unmatched among hard rock lithium operations globally. [Source: IGO Annual Report FY2024; Talison Lithium disclosures]
Q: Why is Nova-Bollinger suspended?
A: Nickel prices collapsed in 2023-2025 due to a flood of Indonesian nickel supply. At the resulting LME nickel prices, Nova-Bollinger's all-in sustaining costs were above revenue, making it uneconomic to operate. Restart depends on sustained nickel price recovery. [Source: IGO ASX Announcement, 21 February 2025]
Q: Why does IGO have no P/E?
A: With Greenbushes operating at lower lithium-price margins and Nova-Bollinger suspended, IGO's current period earnings are minimal or negative. This doesn't mean financial difficulty -- IGO has substantial cash -- but current earnings don't support a meaningful P/E calculation.
|
|
Business Analysis |
What Liontown does: Liontown Resources is an ASX-listed lithium developer and emerging producer, primarily focused on the Kathleen Valley lithium project in the Goldfields-Esperance region of Western Australia. Kathleen Valley is widely regarded as one of the world's premier new hard rock lithium deposits -- high grade, large resource, excellent infrastructure access and a positive development pathway. Liontown made the transition from explorer to producer in 2024 as Kathleen Valley achieved first production.
Kathleen Valley -- the flagship: The Kathleen Valley lithium deposit is located approximately 680 kilometres north of Perth and 60 kilometres north of Leinster in WA. The deposit contains a large JORC-compliant resource and reserve of high-grade lithium-bearing spodumene. Kathleen Valley's open-cut mine feeds a Dense Media Separation processing plant producing spodumene concentrate. Underground mining was incorporated into the mine plan to access higher-grade ore at depth, adding long-life production from a premium ore zone.
Offtake agreements -- major customer validation: Kathleen Valley's production quality and volume was validated by a portfolio of major offtake agreements signed prior to production commencement. These include agreements with Tesla (a landmark deal for direct battery supply chain integration), LG Energy Solution and Ford. These agreements -- with three of the world's most important battery and EV companies -- are not merely commercial arrangements: they represent strategic endorsements of Kathleen Valley's product quality and Liontown's long-term supply reliability.
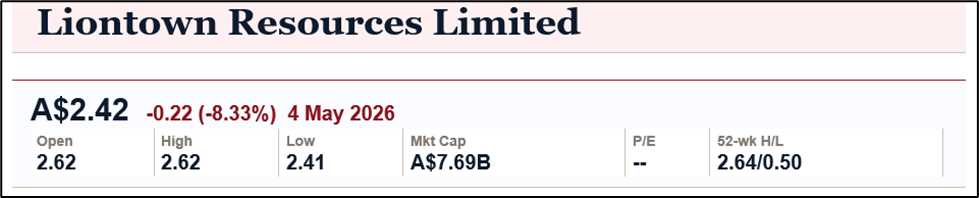
The Albemarle takeover approach: In 2023, Albemarle Corporation -- the world's largest lithium producer -- made a series of takeover approaches for Liontown, ultimately reaching a binding scheme implementation deed at A$3.00 per share (approximately A$6.6 billion implied equity value). The deal was subsequently withdrawn by Albemarle following its own stock price decline and financing constraints. The A$3.00 takeover price establishes a reference point: a major, sophisticated lithium producer assessed Kathleen Valley to be worth A$3.00 per share in 2023. At A$2.42 in May 2026, the stock remains below that reference.
Ramp-up phase: As of FY2024, Kathleen Valley was in the production ramp-up phase, progressively increasing throughput toward nameplate processing capacity. First production milestones were achieved in 2024. Achieving design throughput, consistent ore grade delivery and meeting offtake specification requirements are the operational milestones that will convert Liontown from a developer into a fully operational producer and unlock earnings from the currently loss-making balance sheet.
|
|
Financial Analysis |
Liontown's financial profile is that of an early-stage producer: capital expenditure heavy, revenue growing but not yet offsetting costs, and a balance sheet shaped by the A$895 million in funding raised for Kathleen Valley's development. The P/E ratio of '--' reflects the current loss-making or pre-earnings phase of the business -- Liontown is investing now for earnings in subsequent years.
The company's financial health hinges on: (1) achieving planned production volumes at Kathleen Valley; (2) selling spodumene at prices sufficient to cover all-in sustaining costs; and (3) maintaining adequate liquidity through the ramp-up period. The A$760 million credit facility arranged for the project provides financial support alongside operating cash flows.
The 52-week range of A$0.50 to A$2.64 -- with the current price at A$2.42 near the top of the range -- reflects the dramatic re-rating as Kathleen Valley moved from development to production. At the 52-week low of A$0.50, the market was pricing in severe lithium downturn risk and production execution uncertainty; at A$2.42, it is pricing in a successful ramp-up and lithium price recovery.
|
|
Price Performance |
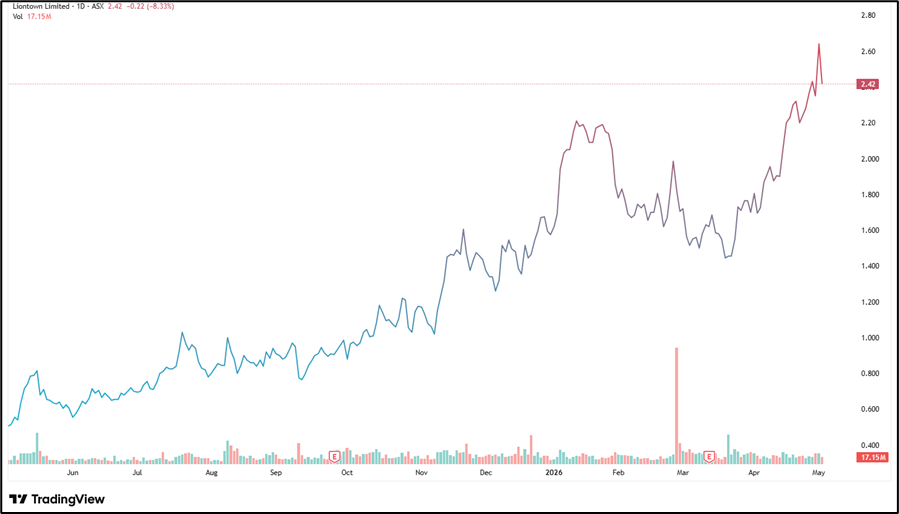
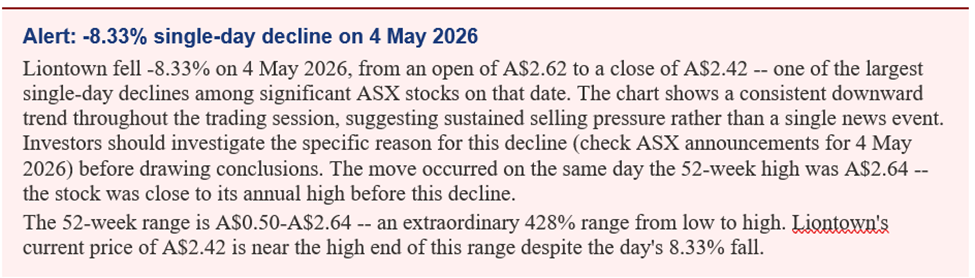
The -8.33 per cent decline on 4 May 2026 is the largest single-day fall of the four stocks on this date and warrants specific attention. At the time of writing, no specific company announcement explaining the move is cited in the source data. Possible explanations include: a broader lithium sector re-rating event, news from a major offtake customer, production guidance update, or market-wide risk-off selling amplified by Liontown's smaller market cap and higher-beta profile. Investors should check the ASX announcements for 4 May 2026 before drawing conclusions.
Abstracting from the day's move, Liontown's broader 52-week performance is strong: from A$0.50 to the current A$2.42 represents a recovery of 384 per cent. The stock has been one of the strongest performers in the lithium sector as Kathleen Valley de-risked into production.
|
|
Valuation and Risks |
Liontown is valued on a development/early-production basis: a combination of NPV of Kathleen Valley's reserve at assumed long-run spodumene prices, plus an option value for the underground mine development and further resource upside. The Albemarle A$3.00 reference price from 2023 provides a useful anchor -- at A$2.42, the stock is approximately 19 per cent below the price a major strategic buyer assessed as fair value in a different lithium price environment.
Key risks: Lithium price is the primary risk for all four stocks, but is most acute for Liontown as an early-stage producer without a diversified earnings base. Production ramp-up execution risk -- failing to achieve nameplate throughput on schedule could require additional capital or offtake renegotiation. Offtake price risk -- agreements with Tesla, LG and Ford are at prices linked to market pricing mechanisms; if market prices remain depressed, realised prices may be below development assumptions. No dividend: Liontown pays no dividend and is unlikely to do so until Kathleen Valley generates sustained free cash flow.
|
|
Outlook |
Liontown's outlook is the most binary of the four stocks: if Kathleen Valley ramps to full production, lithium prices recover to mid-cycle levels, and the Tesla/LG/Ford offtakes generate the anticipated revenue, Liontown should generate significant free cash flow at scale. If any of those three conditions is absent -- delayed ramp-up, sustained low prices, or customer issues -- the financial position becomes more challenging. The Albemarle A$3.00 reference price, lithium price recovery, and the strategic importance of the Kathleen Valley asset to three of the world's largest EV and battery companies all support the medium-term investment case.
|
|
FAQs -- Liontown Resources |
Q: What is Kathleen Valley?
A: One of Australia's premier new hard rock lithium deposits, located in WA's Goldfields region. Liontown developed it from explorer to producer between 2021 and 2024. It produces high-grade spodumene concentrate with offtake agreements with Tesla, LG Energy Solution and Ford. [Source: LTR Annual Report FY2024]
Q: Why did Albemarle try to acquire Liontown?
A: Albemarle -- the world's largest lithium producer -- made multiple approaches in 2023 and reached a binding SID at A$3.00/share. The deal collapsed when Albemarle withdrew, citing its own financing constraints following a decline in its share price. The A$3.00 price is a reference for the strategic value of Kathleen Valley. [Source: LTR ASX Announcements, 2023]
Q: What is the significance of the Tesla, LG and Ford offtakes?
A: Three of the world's most important EV and battery companies have signed offtake agreements to purchase Kathleen Valley spodumene. This validates the product quality, confirms a customer base for initial production volumes, and provides some revenue certainty during ramp-up. [Source: LTR Annual Report FY2024; LTR ASX Announcements]
Q: Why did LTR fall -8.33% on 4 May 2026?
A: The specific reason is not confirmed in the source data provided. Liontown's higher-beta, early-production status makes it susceptible to larger single-day moves than diversified majors. Investors should check ASX announcements for 4 May 2026 for any company-specific news that explains the movement.
COMPARATIVE ANALYSIS
The four stocks compared: a framework for lithium investors
The four ASX lithium stocks span the full development spectrum -- from world-scale established producer to early-stage ramp-up. Each offers distinct risk-return characteristics within the same underlying commodity cycle.
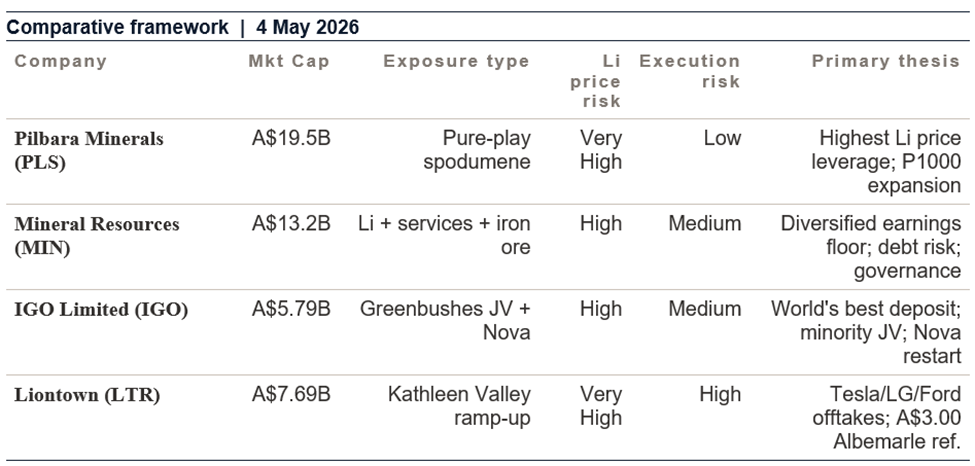
For maximum lithium leverage: Pilbara Minerals offers the most direct, concentrated exposure to the spodumene price cycle. When prices recover, PLS earnings will surge; when prices are low, the balance sheet provides resilience. The P1000 expansion maximises volume exposure to the next up-cycle.
For diversified resources exposure with lithium: Mineral Resources offers lithium upside alongside mining services earnings resilience and iron ore. At P/E 33.18, it is currently priced for recovery -- investors are paying for the lithium upside within a business that can survive a prolonged low-price environment.
For exposure to the world's best deposit: IGO's Greenbushes economic interest (via TLEA) provides access to the world's highest-grade and largest hard rock lithium mine. The JV structure limits control but the asset quality is unmatched. Nova-Bollinger restart is the additional optionality.
For the development/early-production growth story: Liontown offers the highest execution risk and the highest potential reward for investors who believe Kathleen Valley will deliver its design production profile into a recovering lithium price environment. The Albemarle A$3.00 reference price and major customer endorsement (Tesla, LG, Ford) provide strategic anchors for the investment case.


 Nov 13, 2026





 Please wait processing your request...