
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- FEX shares down 7.04% despite record 1.2M wet metric tonnes shipped in December quarter
- FY26 guidance reconfirmed: 4.2-4.8Mt iron ore sales at C1 cost of A$70-80/t
- Weld Range Project acquisition: Largest undeveloped iron ore resource in Western Australia Mid-West
- Growth path: Ramp to 6Mtpa by 2028, with A$79M cash position providing financial flexibility
- Third mine (Beebyn-W11) imminent, with Sinosteel partnership expanding expansion optionality
FENIX Resources (ASX:FEX) stock declined 7.04% despite record production quarter and reconfirmed growth guidance, reflecting broader iron ore sector sentiment and profit-taking following recent strength. The company's established production operations, clear growth pathway, and strategic Weld Range acquisition provide strong fundamental support. This FENIX Resources stock analysis examines near-term concerns and medium-term value drivers.
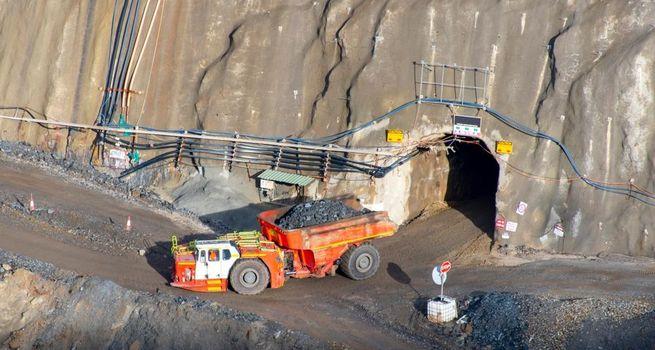
FENIX operates three iron ore mines in Western Australia's Mid-West region, producing high-quality lump and fines ore for export. The recent Weld Range acquisition positions the company for significant production growth through 2028. Understanding why FEX shares are declining despite operational excellence requires examining market sentiment toward mid-tier iron ore producers.
About FENIX Resources Ltd
FENIX Resources Limited operates three iron ore mines in Western Australia's Mid-West region: Scattered Islands, Pilbara Minerals, and Beebyn. The company shipped record 1.2 million wet metric tonnes in the December quarter, demonstrating operational excellence. Recent acquisition of the Weld Range Project—one of the largest undeveloped iron ore resources in the region—provides multi-year production growth pathway.
The company targets production growth from current levels to 4.2-4.8Mt in FY26, ramping to 6Mtpa by 2028. Strong cash position of A$79M provides financial flexibility for growth investments and shareholder distributions. Partnership with Sinosteel for Weld Range development creates strategic optionality.
Why FEX Stock Is Moving Today
The 7.04% decline reflects profit-taking following strong recent performance and market assessment of iron ore sector dynamics. Iron ore prices remain elevated but show near-term volatility creating sentiment uncertainty. Market participants are reassessing growth investment capital requirements ahead of Weld Range development announcements.
Broader concerns about Chinese steel demand growth rates and construction activity create cyclical caution. However, FEX's strong operational execution and clear cost advantage position it well relative to marginal producers. This weakness is likely temporary given demonstrated operational excellence.
Industry Trends and Market Context
Global iron ore demand remains strong despite near-term economic uncertainties, with infrastructure development and steel production requirements supporting baseline demand. Supply constraints from major producers create pricing power for efficient mid-tier operators. China's continued urbanization supports long-term demand growth despite cyclical weakness.
Energy transition demand for steel in renewable energy infrastructure and EVs provides structural support. Margin compression risks exist if iron ore prices decline materially, but FEX's low-cost position provides downside protection.
Financial Performance Analysis
FENIX maintains A$79M cash position enabling Weld Range development without requiring external capital raises. C1 cash cost of A$70-80/t provides substantial margin cushion at current prices. FY26 revenue guidance of 4.2-4.8Mt at premium pricing supports strong EBITDA generation.
Operating leverage accelerates as production ramps through Weld Range development. Capital discipline combined with operating cash generation supports potential shareholder distributions. Debt-free position provides financial flexibility.
Investment Risks to Consider
Cyclical iron ore price exposure creates earnings volatility, though FEX's cost position provides downside protection. Growth capex requirements for Weld Range ramp could impact near-term cash distributions. Execution risk on third mine (Beebyn-W11) commissioning remains present despite strong track record.
Competition from larger producers with greater resources could impact pricing or market share. Environmental or permitting delays could extend production ramp timelines. Sinosteel partnership structure creates governance complexity.
Future Growth Drivers
Primary growth driver is Weld Range development targeting 6Mtpa production by 2028, representing significant scale-up from current operations. Partnership with Sinosteel provides capital and market access supporting growth. Third mine commissioning (Beebyn-W11) adds capacity and operational optionality.
Operational improvements and efficiency gains support margin expansion across the production base.
Analyst Outlook and Market Sentiment
Analyst sentiment reflects confidence in FEX's operational execution and cost position despite near-term iron ore sector concerns. Growth guidance is viewed as achievable with current capital deployment plans. Weld Range success represents significant value inflection point.
Key catalysts include quarterly production reports, Weld Range development announcements, and iron ore price movements.
Long-Term Investment Perspective
Over 5-10 year horizons, FENIX Resources benefits from established production base combined with low-cost growth optionality. If Weld Range ramp succeeds, FEX becomes a top-tier mid-tier iron ore producer with significant cash generation. Market typically assigns premium valuations to proven producers with clear growth pathways.
Operational excellence demonstrated to date supports confidence in growth execution. Margin resilience in downcycles positions the company well for commodity cycles.
Conclusion
FENIX Resources' 7.04% decline despite record operational performance reflects typical mid-tier producer volatility during commodity uncertainty rather than operational deterioration. The company's established production, low-cost position, and clear Weld Range growth pathway remain compelling fundamentals. Understanding why FEX shares are declining contextualizes near-term sentiment versus long-term value.
For iron ore investors seeking mid-tier producer exposure, FENIX stock analysis suggests current weakness offers accumulation opportunity. Demonstrated operational excellence and clear growth pathway to 6Mtpa by 2028 support long-term value creation. Accumulating during commodity sector weakness typically rewards patient investors in quality producers.


 Nov 13, 2026





 Please wait processing your request...